

What Guaranteed Interest Crediting Rate Means
A guaranteed interest crediting rate is the minimum rate an insurer promises to credit to your annuity’s account value for a specified period. It’s the floor under your growth—so even if markets or the insurer’s portfolio underperform, your contract credits at least this rate to the portion covered by the guarantee.
Where You’ll See It (And How It Works)
- Traditional Fixed Annuities (Declared-Rate): The insurer sets a fixed rate for a period (often 1–3 years) and guarantees it for that term. At renewal, a new declared rate applies, subject to the contract’s minimum guarantee.
- Multi-Year Guaranteed Annuities (MYGAs): Compare multi-year guaranteed annuity rates to see the interest guarantees available for different terms.
- Fixed Index Annuities (FIAs): Most of your value earns interest based on an index strategy (with caps and spreads/participation). Many FIAs also include a fixed account with its own declared, guaranteed rate—useful when you want certainty for part of your balance.
- Variable Annuities (Fixed Account Option): Some VAs offer a fixed account sleeve with a declared, guaranteed rate. It behaves like a traditional fixed pocket inside the VA.
Why It Matters
- Predictability: It sets a floor so you can plan cash flow and timelines.
- Renewal Discipline: Knowing the guaranteed minimum helps you judge renewal offers—stay, ladder, or 1035-exchange.
- Downside Protection: In mixed strategies (like FIAs), parking dollars in the fixed account can stabilize overall results.
Quick Example
You place $100,000 in a MYGA with a 5-year guaranteed rate. If the contract rate is 5% and credited annually, your value compounds at 5% each year for all five years. In a declared-rate fixed annuity, if the insurer declares 4.7% for Year 1 and your contract’s minimum guaranteed rate is 1.0%, then even if Year 2’s renewal falls, it can’t go below 1.0% while that minimum applies (per your contract’s terms).
Smart Ways To Use Guaranteed Rates
- Ladder Terms: Split money across 2–5 year terms so part of your cash renews each year—useful if you expect rates to change.
- Blend FIA + Fixed Pocket: Keep a portion in the FIA’s fixed account to stabilize results while the rest participates in index strategies.
- Match Term To Goal: Pick a term that matures right before you need funds (home project, RMD planning, retirement date).
- Use Tax Placement Wisely: Hold fixed growth in IRAs for tax-deferral or consider non-qualified annuities for tax-deferred compounding.
- Upgrade Via 1035 Exchange: If you’re sitting in a low declared rate with no surrender charges, move to better rates or terms when the math clearly improves.
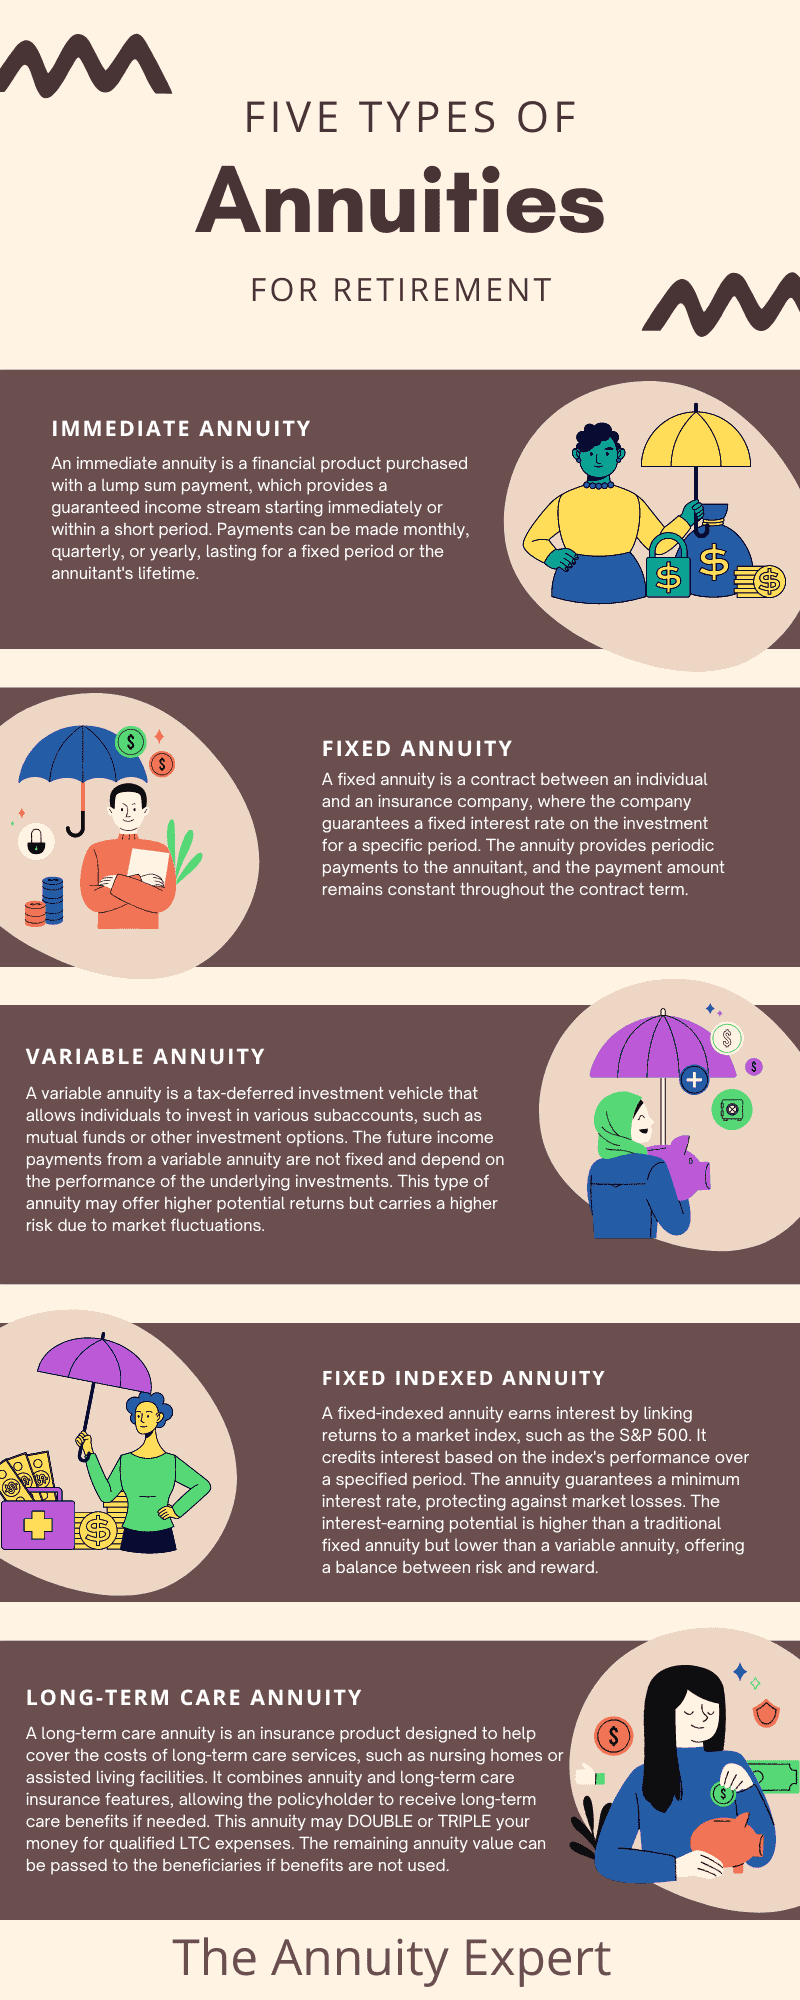
Your Best Options We Sell (Side-By-Side)
1) Multi-Year Guaranteed Annuity (MYGA)
- What it is: A fixed annuity with one guaranteed interest crediting rate locked for the entire term.
- Who benefits:
- Savers who want a CD-like experience with tax-deferred growth and often higher rates than CDs.
- Those with a specific date-driven goal (bridge to retirement, near-term purchase).
- Who doesn’t:
- Anyone needing frequent liquidity beyond free-withdrawal allowances.
- Investors seeking market-linked upside.
- Pros:
- Rate guaranteed for the full term.
- Simple, predictable, tax-deferred growth.
- Often higher yields than CDs for similar terms.
- Cons:
- Early withdrawals may incur surrender charges (and IRS penalties if under 59½ for qualified funds).
- No market-linked upside.
2) Traditional Fixed (Declared-Rate) Annuity
- What it is: An insurer declares a fixed rate for a period (often 1–3 years), subject to a contract minimum guaranteed rate.
- Who benefits:
- Savers who want flexibility to accept new declared rates or reposition at renewals.
- Those who value guaranteed crediting with periodic rate resets.
- Who doesn’t:
- Anyone who wants a single, multi-year rate locked for the whole term.
- Investors prioritizing equity-linked growth.
- Pros:
- Guaranteed floor with periodic opportunities to adjust.
- Often includes free withdrawal features.
- Cons:
- Renewal rates can change.
- Typically, lower long-term potential than market-linked strategies.
3) Fixed Index Annuity (FIA) With Fixed Account
- What it is: An FIA that offers index strategies plus a fixed account sleeve with a declared, guaranteed interest rate.
- Who benefits:
- Risk-aware savers who want some growth potential without market losses.
- Blended allocators who like a stabilizing fixed bucket.
- Who doesn’t:
- Investors seeking full liquidity or uncapped market returns.
- Short-term savers who dislike surrender schedules.
- Pros:
- No market-loss risk to principal due to index declines.
- Ability to dial your fixed/index split.
- Cons:
- Index strategies have caps and spreads/participation limits.
- More moving parts than MYGAs or pure fixed.
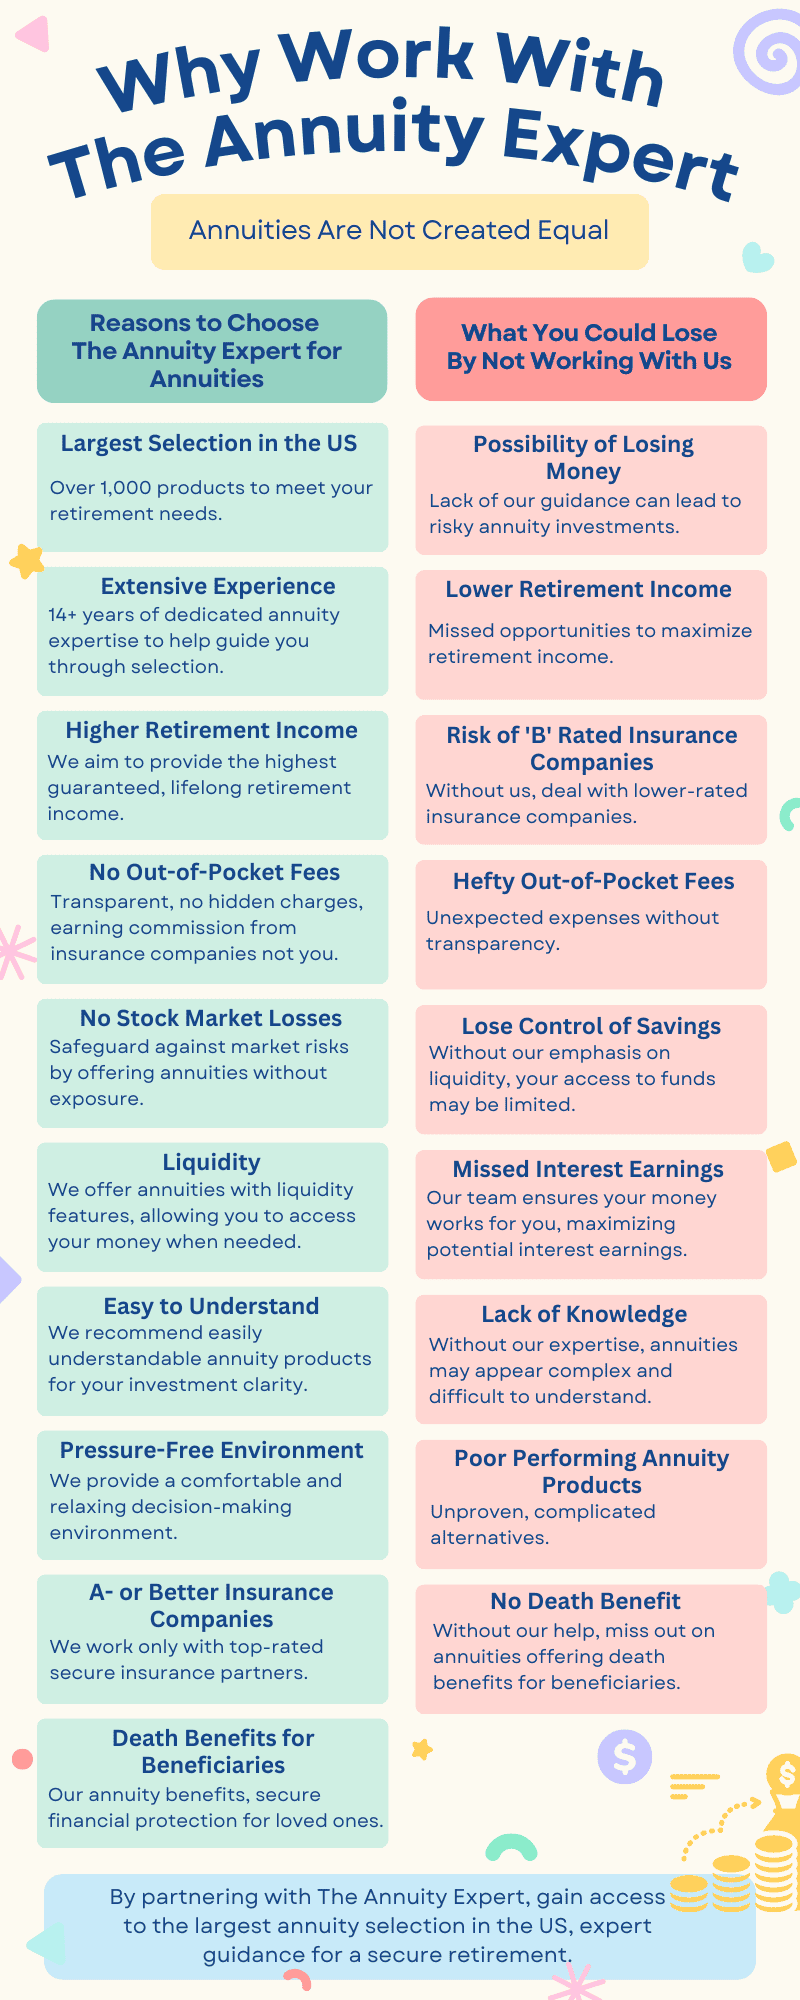
How We Help You Compare
At The Annuity Expert, we’re an independent annuity broker. We shop top-rated carriers, compare guaranteed interest crediting rates and contract terms side-by-side, and help you choose the right mix of term length, liquidity, and income options for your goals.
Next step: Tell us your timeline and liquidity needs. We’ll build a ladder or single-term strategy and show you the best quotes available today.
Want a side-by-side of today’s best guaranteed crediting options? Compare quotes and talk to an advisor at The Annuity Expert.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.