

What is an Annuity Illustration?
An annuity illustration is a comprehensive document that projects an annuity’s performance over time. It takes into account various factors, such as interest rates, fees, and potential scenarios that might affect the annuity’s growth. This document allows you to visualize how your investment will evolve, helping you make more informed decisions about your financial future.
Example: If you’re considering a fixed annuity with a 3% annual return, the illustration will show how your investment could grow each year, accounting for any fees or costs.
When planning how to read annuity illustrations when buying, compare annuity quotes so the comparison reflects your age, state, premium amount, income start date, and the specific guarantee you actually want.
The Types of Annuity Illustrations You’ll See
- MYGA (Multi-Year Guaranteed Annuity)
- Shows a fixed rate for a set term, surrender period, and cash values over time.
- Fixed Indexed Annuity (FIA)
- Project growth using crediting strategies (caps, spreads, participation rates). Often includes an income rider (GLWB) illustration with guaranteed withdrawal values.
- Immediate Income (SPIA) & Deferred Income (DIA)
- Focuses on payout options (life only, period certain, joint life) and the income start date.
- Variable Annuity (VA)
- Uses hypothetical subaccount returns and fee assumptions; may include a rider with a benefit base for guaranteed withdrawals.
Why Request an Annuity Illustration?
Requesting an annuity illustration is crucial for understanding your investment. This document provides insights into potential returns, associated costs, and the impact of different market conditions on your annuity.
It is vital to understand why annuity illustrations can often set you up for failure if you rely on them as guarantees.
Example: Sarah, interested in investing in an annuity, used illustrations to compare different providers, ensuring she got the best value for her money.
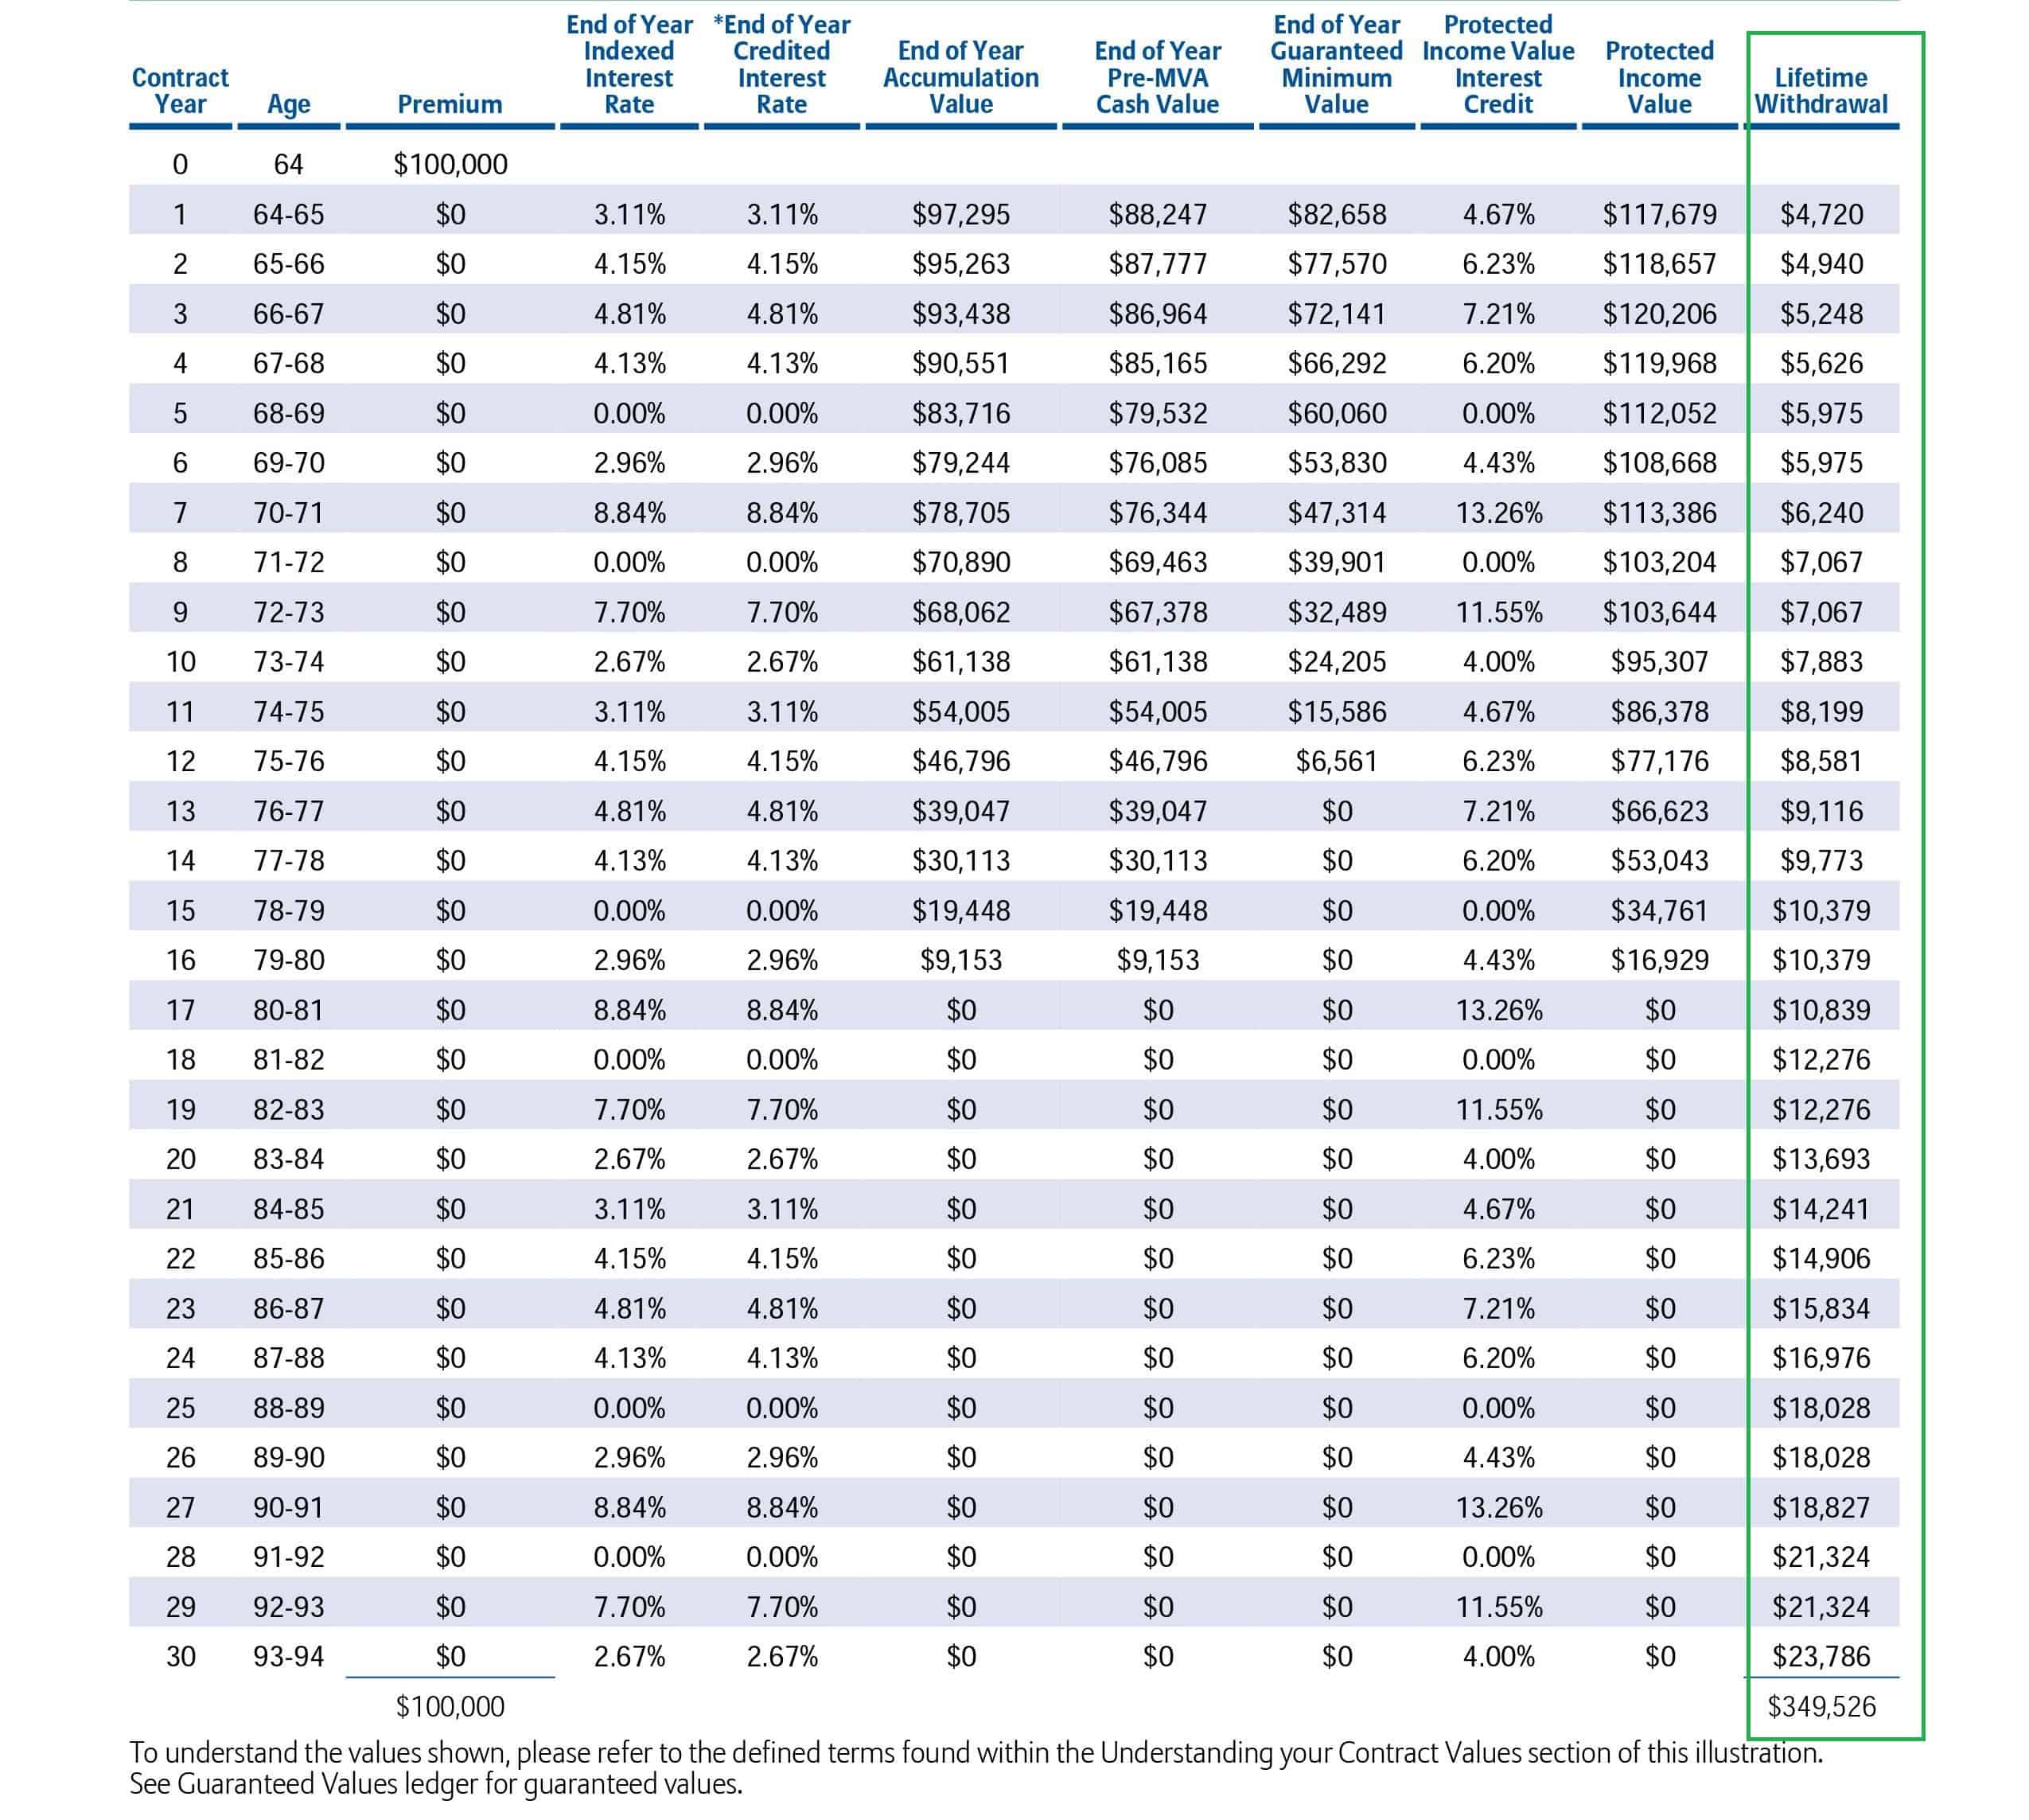
How Does an Annuity Illustration Work?
An annuity illustration works by projecting the future performance of the specific annuity contract you’re considering. It includes:
- Inputs: Initial investment, additional contributions, interest rates, and specific terms.
- Projections: Expected payouts after the accumulation phase ends.
- Scenarios: Economic conditions showing potential growth impacts.
Example: Tom, considering a 10-year annuity, illustrated how his investment might grow under different conditions.

Who Needs an Annuity Illustration?
Anyone considering an annuity should ask for an illustration, whether you’re a new investor, an experienced investor, or a financial advisor.
Example: Rita, a seasoned investor, found subtle nuances in an illustration that helped her make a more informed choice.
Why Do People Rely on Annuity Illustrations?
Annuity illustrations provide a clear picture of potential investment outcomes. People rely on them for:
- Transparency: Clear outline of terms, fees, and potential returns.
- Planning: Helps create a robust retirement strategy.
- Peace of Mind: Confidence in making informed decisions.
Example: Carlos felt confident in his investment after reviewing his annuity illustration, which clarified potential returns and fees.

How To Read Any Annuity Illustration (Step-By-Step)
- Confirm Owner/Annuitant Basics
Ages, state, tax status (qualified/non-qualified), premium amount, and issue date all affect rates and features. - Separate Guarantees From Non-Guarantees
- Guaranteed values: What the carrier must provide (e.g., minimum values, guaranteed income schedule).
- Current/non-guaranteed values: Based on today’s caps, participation rates, or hypothetical returns—they can change.
- Scan Fees and Riders
Look for GLWB rider charges, M&E charges (VAs), strategy charges (FIA enhanced strategies), and any other policy fees. Know what you’re paying and what benefit you receive. - Check Crediting Assumptions
- FIA: Caps, participation, or spreads used; whether a volatility-controlled index is assumed; if back-tests are shown, remember they’re hypothetical.
- VA: Gross return assumptions minus all fees; ask to see multiple return scenarios (e.g., 0%, 3%, 5%, 7%) for realism.
- Understand the Income Math (If Using a GLWB or SPIA/DIA)
- Benefit base vs. cash value: The benefit base is a calculation ledger for withdrawal percentages; it’s not cash you can walk away with.
- Note deferral bonuses, roll-ups, and payout percentages at your target start age. Compare income at the same age across carriers.
- Review Surrender Terms
- Schedules, Market Value Adjustment (MVA), free withdrawal amounts, and how partial withdrawals affect guarantees.
- Ask for Sensitivity Tests
- Lower caps and participation rates for FIAs
- Lower/higher return scenarios for VAs
- Earlier/later income start ages for GLWBs/SPIA/DIA

How Hypothetical Returns Can Distort Expectations
Common Traps (And How To Avoid Them)
- Comparing different start ages
Standardize age, premium, timing, and payout option across all illustrations. - Falling in love with the “best case” column
Always compare guaranteed values and run conservative scenarios. - Confusing benefit base with cash value
Your income can be significant even if your cash value isn’t growing—know which number matters for your goal. - Ignoring rider costs
A 1.0%–1.4% rider can be worth it for guaranteed lifetime income—but only if the payout percentage and deferral credits beat alternatives. - Chasing complex indices
Fancy index names don’t guarantee better results. Ask for comparisons using simple S&P 500 point-to-point alongside any exotic index.

How We Work (Independent & Comparison-Driven)
The Annuity Expert is an independent insurance agency, annuity broker, and retirement planner. We shop multiple top-rated carriers and deliver clear, side-by-side illustrations—so you see fees, guarantees, and income differences without sales pressure.
- Step 1: Free consult
Share your age, state, premium, timeline, and goal (income now/later, or growth). - Step 2: Custom illustration pack
We produce apples-to-apples comparisons (FIA with a GLWB, SPIA/DIA, MYGA). You’ll see guaranteed and non-guaranteed columns, rider fees, and surrender terms. - Step 3: Implement and review
We implement the policy, establish income timelines, and review annually to keep caps/strategies optimized and benefits aligned with your life.
Contact The Annuity Expert for a free, multi-carrier illustration pack and quotes. We’ll compare your options, explain the trade-offs, and help you buy the best coverage—without overpaying.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
Is an annuity illustration a contract?
An annuity illustration is not a contract but a document that estimates how a particular annuity product might perform under various conditions. It outlines potential payouts, fees, and other elements to help you understand the annuity’s features. The actual contract will contain the annuity’s legally binding terms and conditions. Always read the contract carefully before committing.
At what age do you have to start drawing from your annuity?
The age at which you must start drawing from your annuity depends on the terms of your specific contract and the type of annuity you have. Some annuities allow for immediate payouts, while others have a deferral period. Some may have age-related stipulations for withdrawals, but this varies. Always consult your contract and financial advisor for personalized guidance.
Do annuities have illustrations?
Yes, many annuity providers offer illustrations, which are documents that project potential growth, payouts, and fees under various scenarios. However, these illustrations are estimates and not guarantees. Always read the actual contract for the annuity’s legally binding terms and conditions.
What is a variable annuity illustration?
A variable annuity illustration is a visual representation provided by insurance companies to project potential returns. It demonstrates the growth of the annuity’s value based on various investment options and market conditions. These illustrations assist individuals in making informed decisions about their investments and long-term financial goals.
How is annuity illustration software used?
Illustration software shows how a proposed premium, allocation, rider, and income start date could affect an annuity over time. Use it to compare guaranteed contract values, projected values, cash surrender values, and any separate income-benefit base. Ask for matching assumptions across contracts and a low-growth scenario, because a projected benefit-base increase is not necessarily spendable account growth.