

Protect Your Income Without Overpaying
At The Annuity Expert, we’re an independent disability insurance agency dedicated to protecting your income when life takes an unexpected turn. If illness or injury keeps you from working, disability insurance replaces part of your paycheck so you can continue paying bills and supporting your family. Our role is to help you shop the market, compare quotes from top insurers, and customize coverage to fit your budget — making sure you never pay more than necessary for the protection you need.
Navigating policy riders can be overwhelming. As your disability insurance broker, we do the heavy lifting by comparing top carriers to find your best fit—completely free of charge.
How to Compare Disability Insurance Quotes
Work with a Licensed Broker or Agent
- How it works: A broker compares quotes from multiple insurers and explains the differences in definitions of disability, elimination periods, benefit periods, and riders.
- Pros: Personalized advice, access to multiple insurers, help with underwriting and claims.
- Cons: Takes more time than online tools, and broker quality varies.
- Best for: Professionals with specialized jobs (doctors, pilots, attorneys), people with health issues, or anyone who wants guidance.
- Not ideal for: Simple cases where you want a quick estimate.
Use an Online Marketplace
- How it works: Marketplaces let you fill out one form and see side-by-side quotes from several insurers.
- Pros: Quick comparisons, easy to use, suitable for getting a baseline.
- Cons: Limited to the insurers they partner with, may lack depth on definitions and riders.
- Best for: First-time buyers wanting a broad market overview.
- Not ideal for: Complex health or job situations.
Get Quotes Directly from Insurers
- How it works: Many insurance companies offer online quote calculators.
- Pros: Direct from the source, sometimes more accurate, and may offer company discounts.
- Cons: Only shows one option, easy to miss better policies.
- Best for: If you already like or trust a specific insurer.
- Not ideal for: Shoppers who want to compare multiple carriers.
Explore Employer or Group Plans
- How it works: Employers sometimes provide short- or long-term disability coverage.
- Pros: Often subsidized or guaranteed issue with no medical underwriting.
- Cons: Coverage is usually limited, and it is not portable if you change jobs.
- Best for: Everyone should at least review employer coverage.
- Not ideal for: High-income earners or anyone who needs coverage that moves with them.
Consider Specialty Disability Insurers
- How it works: Some insurers tailor coverage for specific professions, such as physicians, dentists, or pilots.
- Pros: Stronger “own-occupation” definitions and higher benefit amounts.
- Cons: Available only to certain professions.
- Best for: High-earning professionals with unique risks.
- Not ideal for: General occupations or moderate incomes.
Disability Insurance Calculator
A disability insurance calculator estimates the amount of income protection needed in the event of a disability. You can use this as a guide to determine the coverage amount you would need.
Key Factors That Impact Quotes
- Benefit amount: The monthly income you want protected.
- Benefit period: How long benefits last (5 years, to age 65, or lifetime).
- Elimination period: Waiting period before payments begin.
- Definition of disability: Own-occupation vs. any-occupation.
- Riders: Add-ons like cost-of-living increases or future purchase options.
- Factors include age, health, job, and state regulations.
How Much Disability Insurance Do I Need?
The coverage amount is a crucial aspect of disability insurance. It determines the benefit you’ll receive if you become unable to work. Typically, it’s a percentage of your current income, often around 60-70%.
For example, if your monthly income is $5,000, a 60% coverage plan would provide a $3,000 monthly benefit. Ensuring this amount aligns with your financial needs is essential.
Who Needs Disability Insurance and Why
- Who needs it: Working adults who support themselves or their families, high-earning professionals, self-employed individuals, and people without strong employer coverage.
- Who doesn’t: Retirees, people with passive income that replaces their paycheck, or those already financially independent.
Helpful Tip: If you are a senior but not yet retired, we have specific disability policies built for seniors.
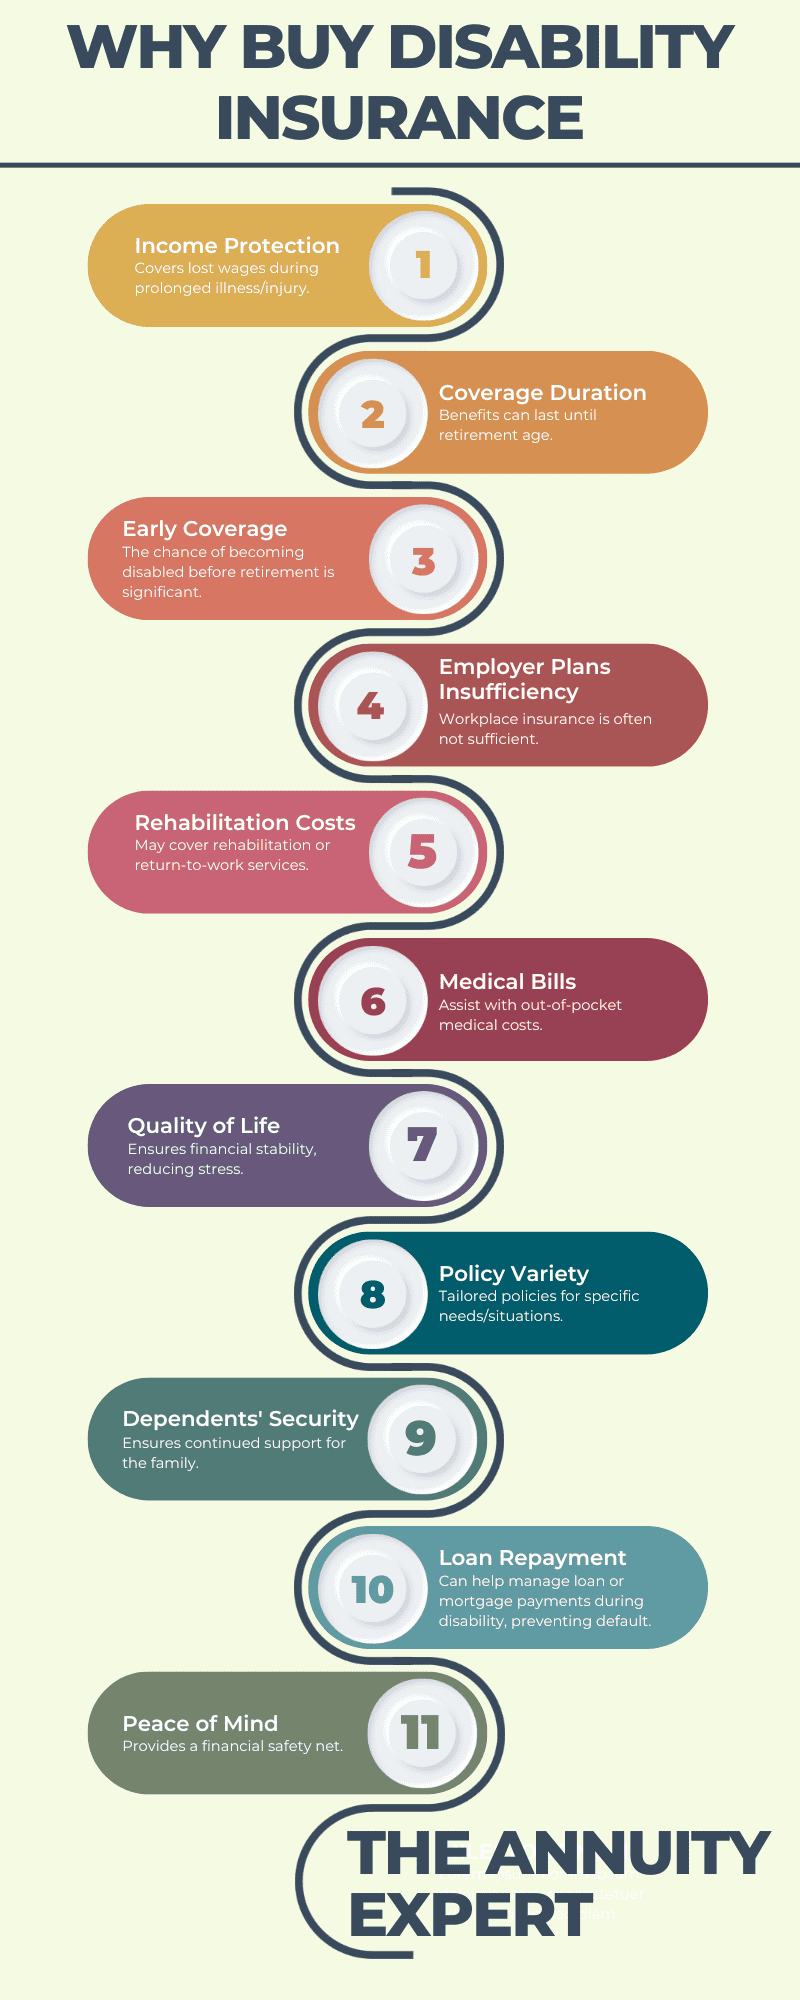
Types Of Disability Insurance We Sell
By Duration
- Short-Term Disability Insurance (STD): Covers temporary disabilities, paying benefits for 3–6 months.
- Long-Term Disability Insurance (LTD): Provides benefits for years or until retirement age, covering chronic or severe conditions.
By Coverage Type
- Individual Disability Insurance: Purchased personally and customizable to your needs.
- Group Disability Insurance: Offered through employers, usually cheaper but less flexible.
By Special Provisions
- High-Limit Disability Insurance: For high earners needing larger monthly benefits.
- Key Person Disability Insurance: Protects a business if a key employee becomes disabled.
- Business Overhead Expense (BOE) Insurance: Pays rent, salaries, and operating costs if the owner is disabled.
- Mortgage Disability Insurance: Ensures your mortgage payments are covered during disability.
Integrated with Other Insurance
- Life Insurance with Disability Riders: Add income protection or premium waivers if you become disabled.
- Annuities with Disability Riders: Waive contributions or add extra income if you’re disabled.

Disability Insurance vs. Accident Insurance vs. Long-Term Care Insurance
Disability Insurance
- Replaces a portion of your income if you cannot work due to illness or injury.
- Pays monthly benefits until you recover or reach the end of the benefit period.
- Protects your paycheck and lifestyle.
Accident Insurance
- Pays a lump sum or reimbursement for medical costs from accidents only.
- Does not cover illness or long-term conditions.
- Works best as a supplement, not a replacement for disability insurance.
Long-Term Care Insurance
- Covers expenses for custodial or nursing care if you cannot perform activities of daily living.
- Pays for services like in-home care, assisted living, or nursing homes.
- Protects retirement savings from being drained by long-term care needs.
Key Takeaway:
- Disability insurance = income protection.
- Accident insurance = medical expense help from accidents.
- Long-term care insurance = retirement asset protection.
How to Save Money on Disability Insurance Quotes
- Choose a longer elimination period: Waiting 90 or 180 days before benefits begin lowers premiums compared to 30 or 60 days.
- Shorten the benefit period: If you only need coverage for 5 or 10 years (instead of to age 65), your cost drops.
- Buy while young and healthy: Rates rise as you age, and health issues can lead to exclusions or higher premiums.
- Use group coverage as a base: Employer-provided insurance is cheaper. You can add an individual policy to “top up” your protection.
- Skip unnecessary riders: Only add riders like COLA or future purchase if you need them. Otherwise, they increase the cost.
- Work with a broker: Brokers can access discounts and policies that aren’t advertised online.
- Shop multiple insurers: Premiums vary widely; one insurer may charge double another for the same coverage.
- Pay annually instead of monthly: Some insurers offer discounts if you pay once a year.
Real-World Example
Sarah, a 35-year-old marketing manager earning $80,000 per year, wants to protect her income until retirement. She applies for a long-term disability policy with a 90-day elimination period and benefits lasting to age 65. Her monthly premium comes to about $120 per month. If she becomes disabled, she’ll receive roughly $4,000 per month (60% of her salary) until recovery or retirement age.
This example shows how affordable coverage can be compared to the income it protects.
Final Thoughts
Disability insurance is income protection. Without it, even a short-term illness or injury could devastate your finances. With the right policy, you’ll have peace of mind knowing your bills and lifestyle are secure.
👉 Contact The Annuity Expert today for free disability insurance quotes. We’ll help you compare top-rated insurers, identify coverage gaps, and secure the best protection at the lowest cost.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Glossary of Disability Insurance Terms
- Own-Occupation: Pays benefits if you can’t work in your specific job, even if you could work in another occupation.
- Any-Occupation: Pays benefits only if you can’t work in any job suited to your education, training, or experience.
- Elimination Period: The waiting period (often 30–180 days) before benefits begin after you’re disabled.
- Benefit Period: How long the policy will pay benefits (5 years, to age 65, or lifetime).
- Residual/Partial Disability Rider: Provides partial benefits if you can still work but at reduced capacity or pay.
- Cost-of-Living Adjustment (COLA) Rider: Increases benefits each year to keep up with inflation.
- Future Purchase Option: Lets you increase coverage later without new medical underwriting.
- Guaranteed Renewable: The insurer must continue your policy if you pay premiums, though rates can rise by class.
- Non-Cancellable: The insurer cannot raise your rates or change terms as long as you pay premiums.
Questions From Our Readers
What medical conditions qualify for disability?
Medical conditions that qualify for disability often include chronic illnesses, severe physical injuries, mental health disorders, and conditions causing significant functional limitations.
Why are disability insurance premiums higher for women?
Women generally have higher premiums because they statistically file more claims and have longer claim durations compared to men.
Is disability taxable?
Disability benefits may be taxable depending on the source of the payments and the individual’s overall tax situation.
Who is best suited for long-term care disability insurance?
Individuals with high-risk jobs or those seeking extended coverage until retirement are best suited for long-term care disability insurance.
What are acceptable pre-existing conditions for disability insurance?
Acceptable pre-existing conditions for disability insurance vary by insurer but often include controlled conditions like hypertension, mild asthma, and some mental health disorders.
When does disability insurance stop paying benefits?
Disability insurance stops paying benefits at the end of the policy term, which could be a specified number of years or until retirement age.
How many disability plans can you purchase?
You can purchase multiple disability plans, but the total benefit amount typically cannot exceed your current income or a specific percentage of it, as defined by insurers.
Does disability insurance run out?
Disability insurance can run out if the benefit period, the predetermined time during which you receive payments, expires.
What happens when you cancel disability insurance?
When you cancel disability insurance, coverage stops, future benefit payments cease, and you typically don’t receive refunds for prior premiums.
What are the differences between disability insurance and Social Security disability benefits?
Disability insurance provides personally funded, often quicker access to benefits, while Social Security disability offers government-funded support with typically stricter qualification criteria and longer processing times.
What are disability insurance coordinated benefits?
Disability insurance coordinated benefits are reduced payments from a policy when a policyholder receives additional disability income from other sources, ensuring combined benefits don’t exceed pre-disability earnings.
Can you receive disability insurance when you are 50?
Yes, you can receive disability insurance at age 50, but premiums may be higher compared to younger individuals.
What is considered Accidental Death in Disability Insurance?
Accidental death in disability insurance is death caused by an unexpected and unintentional event, like a car accident or a fall.
What are the cons of disability insurance?
Cons include high premiums, especially for high-risk individuals, limited coverage, and potentially strict underwriting processes.
What are the different types of disability insurance?
Short-term disability Insurance, Long-Term Disability Insurance, Group Disability Insurance, Own-Occupation Disability Insurance, Any-Occupation Disability Insurance, Partial or Residual Disability Insurance, and High-Limit Disability Insurance are available.
Does disability insurance premium increase with age?
Yes, disability insurance premiums typically increase with age due to the higher risk of disability as you get older.
Does disability insurance accumulate cash value?
No, disability insurance policies do not accumulate cash value.
Do you have to take a medical exam for disability insurance?
A medical exam is often required, especially for higher benefit amounts or if you have health issues.
Do they drug test for disability insurance?
Yes, drug tests may be part of the medical exam for disability insurance, particularly for high-benefit amounts.
What happens if you fail a drug test on disability insurance?
Failing a drug test can lead to denial of coverage or higher premiums due to increased risk assessment.
How much disability insurance do I need?
You generally need enough disability insurance to cover 60-70% of your current income.
What reasons do people get denied disability insurance?
Common reasons for denial include pre-existing health conditions, high-risk occupations, and failing medical or drug tests.
Is supplemental disability insurance worth it?
Yes, supplemental disability insurance can be worth it to cover gaps in employer-provided plans and ensure comprehensive coverage.
How long do long-term disability benefits last?
Long-term disability benefits typically last between 2 years and retirement age (65 or 67), depending on the policy. Some policies may offer lifetime benefits. The policy terms and the nature of the disability determine the duration.
Are disability insurance premiums tax-deductible?
No, personal disability insurance premiums are not tax-deductible. However, benefits received from these policies are typically tax-free. If your employer pays the premiums, then the benefits you receive may be taxable.
Can you buy long-term disability insurance on your own?
Yes, individuals can purchase long-term disability insurance directly from an insurer or through a broker.
What does disability insurance not cover?
It usually doesn’t cover pre-existing conditions, self-inflicted injuries, or disabilities caused by illegal activities.
What’s the difference between short-term and long-term disability insurance?
Short-term disability typically pays benefits for a few months up to a year, while long-term disability can pay until retirement age. Most people need long-term coverage since major illnesses or injuries can last years.
How much disability insurance coverage do I need?
Most policies replace 50%–70% of your income. The right amount depends on your monthly expenses and whether you have savings or other income sources.
Is employer-provided disability insurance enough?
Usually not. Employer coverage often pays only 40%–60% of income and may be taxable. Many workers supplement with an individual policy.
When is the best time to buy disability insurance?
When you’re young and healthy, premiums are lower, and you’re more likely to qualify for strong coverage before health issues appear.