

What an Emergency Fund Really Does
- Purpose: An emergency fund is your personal safety net. It covers unexpected costs like medical bills, car repairs, job loss, or home damage—without relying on debt or selling investments when the market is down.
- Goal: Maintain financial stability, reduce stress, and give yourself time to recover from financial shocks.
How Much You Should Save: Every Common Approach Explained
1. The Months-of-Expenses Method
- How it works: Save 3–12 months of essential expenses such as rent/mortgage, utilities, groceries, and insurance premiums.
- Why it works: It’s simple and directly tied to your actual cost of living.
- Pros: Easy to calculate. Adapts to lifestyle.
- Cons: Doesn’t factor in job stability or insurance protection.
- Who needs it: Ideal for most households—especially families with predictable incomes.
- Who doesn’t: Wealthy households with high liquidity or strong insurance coverage.
2. The Job-Loss Coverage Method
- How it works: Estimate how long it would take you to find a comparable job, then multiply that by your monthly expenses. Add health insurance premiums if you’d lose coverage when unemployed.
- Pros: Tailored to your job market risk.
- Cons: Can overestimate needs in stable industries.
- Who needs it: Self-employed workers, contract employees, or anyone in a cyclical industry like construction or tech.
3. The “Known Unknowns” Method
- How it works: Save specific amounts for predictable but irregular expenses—like your medical deductible, home maintenance, and auto repairs.
- Pros: Helps you prepare for real-world emergencies.
- Cons: May overfund if you double-count costs already insured.
- Who needs it: Homeowners, parents, and people with older vehicles.
- Who doesn’t: Renters or those with new cars under warranty.
4. The Tiered Bucket Method
How it works: Divide your fund into three buckets:
- Tier 1: $1,000–$3,000 in checking for immediate access.
- Tier 2: 1–3 months in a high-yield savings account.
- Tier 3: 3–9 months in a money market account, short-term CDs, or Treasury bills.
- Pros: Combines liquidity with better interest earnings.
- Cons: Requires managing multiple accounts.
- Who needs it: Everyone who wants quick access and growth potential.
- Who doesn’t: Minimal savers or those with simple financial lives.
5. The Income Percentage Method
- How it works: Set aside 10–20% of your income each year until you hit your goal.
- Pros: Works automatically through payroll deductions or transfers.
- Cons: Not as precise as the expense method.
- Who needs it: New savers who need structure.
- Who doesn’t: People with irregular income who need a more flexible approach.
6. Retiree Cash Buffer
- How it works: Retirees should keep 6–12 months of withdrawals in cash so they don’t have to sell investments when markets drop.
- Pros: Reduces sequence-of-returns risk.
- Cons: Cash earns less than invested assets.
- Who needs it: Retirees who rely on investment income.
- Who doesn’t: Pensioners or those with annuity income that covers all expenses.
Where to Keep Your Emergency Fund
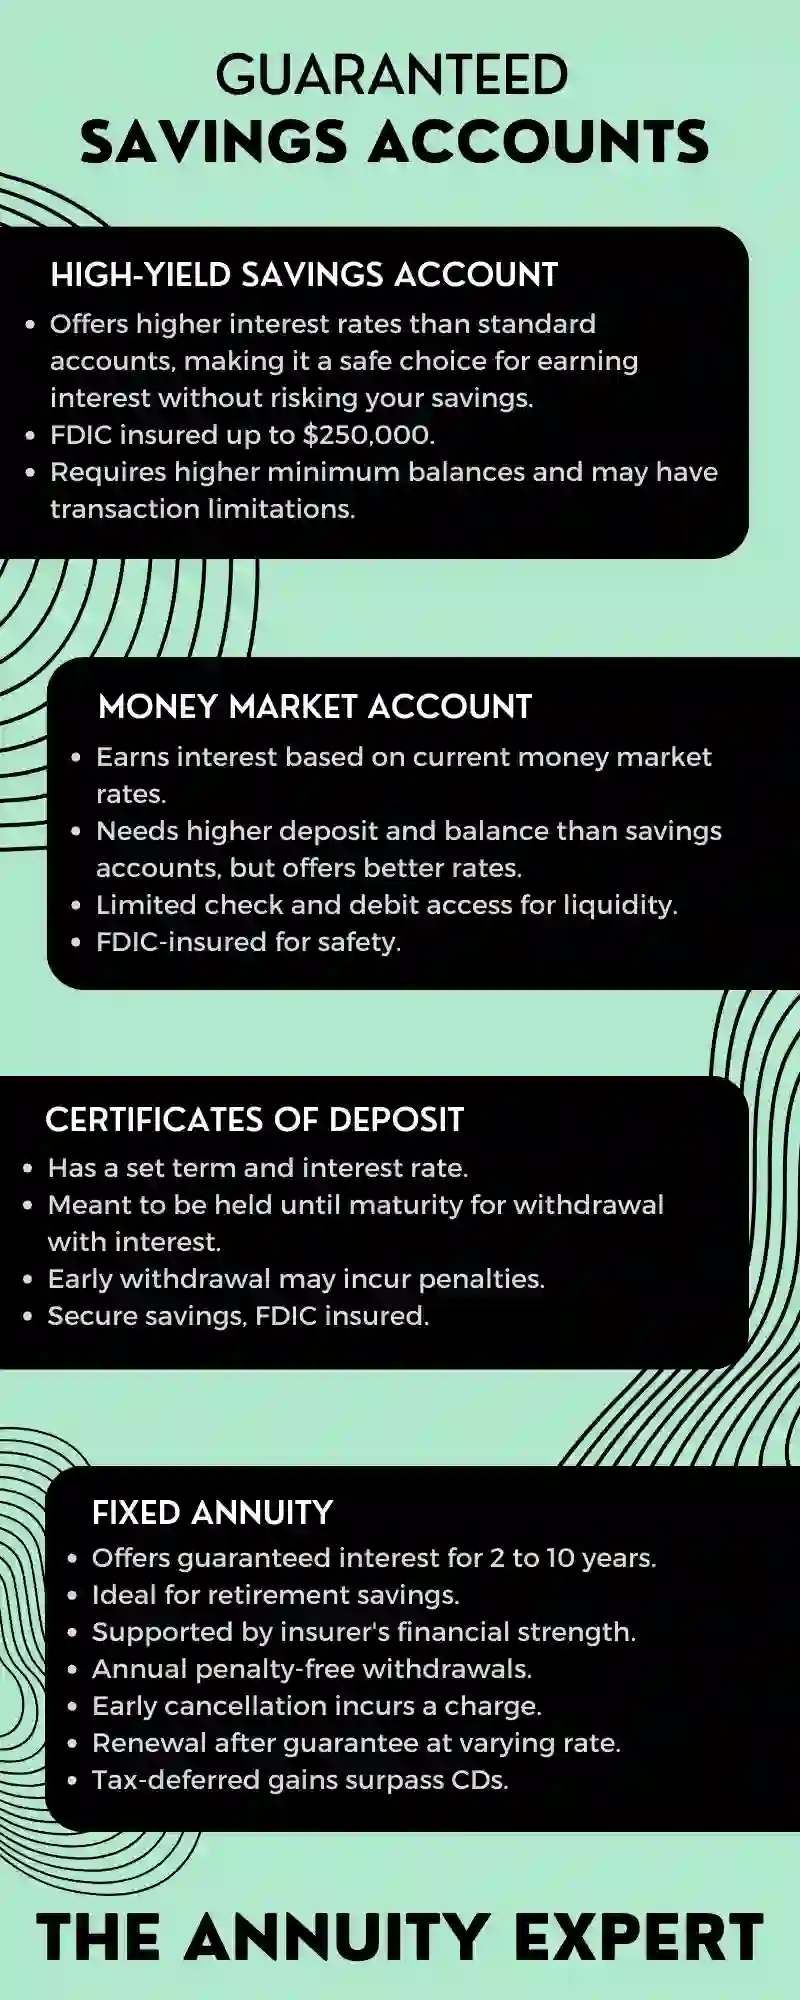
- Checking Accounts: Perfect for instant access but earn almost no interest.
- High-Yield Savings Accounts: FDIC/NCUA-insured and ideal for Tier 2 funds.
- Money Market Accounts: Higher yields, but limited monthly withdrawals.
- Short-Term CDs: Better rates with early-withdrawal penalties for discipline.
- Treasury Bills: Safe, state tax-free, and ideal for advanced savers.
- I Bonds: Good for long-term inflation protection, but locked for 12 months.
Who Needs a Bigger Fund
- Single-income households: One job loss stops all income.
- Self-employed or commission earners: Income varies widely.
- Families with kids: More frequent unexpected expenses.
- Homeowners: Large repair and maintenance costs.
- People with high medical deductibles: Out-of-pocket risks are higher.
Who Can Get By With Less
- Dual earners with stable jobs: Income security from two sources.
- People with strong insurance coverage: Health, disability, and life insurance lower your personal risk.
- Retirees with guaranteed income: Pension or annuity income reduces the need for a big fund.
If You’re Starting Late or Behind
- Cut recurring costs: Reevaluate insurance, subscriptions, and utilities.
- Boost income: Take side gigs or use bonuses to build the fund faster.
- Buy protection: Disability and term life coverage prevent catastrophic losses.
- Automate saving: Even $50 per week builds over time.
Insurance That Reduces Your Emergency Fund Requirement
Your cash reserve covers immediate bills and a policy’s waiting period. For a longer illness or injury that stops you from working, compare disability insurance for an extended loss of earnings, including benefit limits and how disability is defined. It does not cover ordinary unemployment or replace your emergency fund.
- Health Insurance: Covers major medical bills and prevents draining cash reserves.
- Disability Insurance: Replaces lost income due to injury or illness.
- Term Life Insurance: Protects dependents from losing financial stability if you die.
- Homeowners and Renters Insurance: Prevents massive losses from disasters or theft.
- Auto Insurance: Covers repair costs and liabilities.
- Umbrella Insurance: Protects savings against lawsuits.
- Accident or Critical Illness Insurance: Provides lump-sum payouts for major events.
- Why it matters: The more risks you transfer to insurance, the less emergency cash you need to keep on hand.
- Tip: Have your insurance agent review your coverage annually or contact The Annuity Expert for help comparing rates and filling coverage gaps.
When to Add Annuities to the Mix
Once you’ve built your emergency fund, you can shift excess savings into fixed annuities (MYGAs) or fixed indexed annuities (FIAs) for long-term security and higher growth potential.
- Why: Annuities can provide guaranteed income for life, reducing your future need to maintain a large cash cushion.
- Funding options: 401(k), IRA, Roth IRA, non-qualified funds, 1035 exchanges, and rollovers from retirement plans.
- Caution: Never use annuities for emergency funds—they have surrender periods and penalties.
Contact The Annuity Expert for Free Help
Why contact us: The Annuity Expert is an independent annuity and insurance agency. We compare quotes from dozens of companies to help you find the right coverage and rate.
What we do:
- Identify ways to reduce the amount of emergency cash you need by optimizing insurance coverage.
- Compare fixed annuities and insurance plans for long-term financial security.
- Next step: Contact The Annuity Expert for free quotes to build your emergency fund plan and find affordable coverage that protects your savings.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
Is $20,000 enough for an emergency fund?
A savings account with $20,000 is a good starting point for creating a substantial emergency fund. This will help you financially should an unexpected situation arise. However, if you face an extreme situation, $20,000 may only cover limited expenses.
Is a 12-month emergency fund too much?
It ultimately depends on individual circumstances, but typically enough money saved to cover 3 to 6 months of living expenses, including critical expenses like housing and food is sufficient.
Is a 6-month emergency fund too much?
Financial experts recommend having enough money saved to cover 3 to 6 months of living expenses, including critical expenses like housing and food.
How much money should I have saved by 30?
According to financial advice, you should aim to save an amount equal to your yearly salary by age 30. For example, if you make $55,000 annually, your savings at 30 should be $55,000.
How much should a 20-year-old have in an emergency fund?
There isn’t a specific amount that a person in their twenties should aim for in their emergency fund. However, financial experts advise saving enough to cover three to six months’ necessary expenses.
How much should I keep in my emergency fund?
Most households need 3–6 months of essential expenses. Increase it if your income is unstable or if you’re self-employed.
Do retirees still need an emergency fund?
Yes. Retirees should hold 6–12 months of living expenses in cash or short-term accounts to avoid selling investments at a loss.
How often should I review my emergency fund?
Once a year or after major life changes like marriage, a new home, or a job change.