

Timing Is Everything, Especially When Switching to a Better Contract With Bonuses and Lifetime Income Riders
Scenario
You’re thinking about replacing your annuity but aren’t sure if it’s worth the trouble—or if you’ll lose money doing it. The truth is, replacement can be smart when done strategically. Even if you’re facing surrender charges or loss of benefits, you can recover much of the cost with Bonus Annuities and enhanced income features.
Here are the three most common times when replacing an annuity makes sense—and how to minimize regret.
When to Replace a Bad Annuity
1. Replace During the Free-Look Period
Key Stat: Most states offer a 10–30 day free-look window.
If you just bought an annuity and have doubts, now’s the time to act. The free-look period lets you cancel and start over without penalty. This is the cleanest time to switch, mainly if you’ve found a better rate or features elsewhere.
✔ Full premium refund
✔ No surrender charges
✘ Must act fast
✘ Still requires new paperwork and approval
Who Needs It: Anyone with buyer’s remorse or who found a better offer quickly.
Who Doesn’t: Owners outside the free-look period.
Helpful Add-on: Look for a bonus annuity with a Guaranteed Lifetime Withdrawal Benefit (GLWB) for higher future income.
2. Replace with a 1035 Exchange to a Bonus Annuity
Key Stat: Over $1.5 trillion in annuities qualify for tax-free 1035 exchanges.
If your current annuity has high fees, poor growth, or lacks modern benefits, consider a 1035 exchange. This lets you transfer your annuity’s value into a new one without paying taxes. Choosing a bonus annuity—which adds an upfront percentage (often 6%–10%)—can help offset any surrender charges or lost growth from the old contract.
✔ Tax-deferred exchange
✔ Get an upfront bonus to recover losses
✔ Better benefits, riders, or growth options
✘ New surrender period starts
✘ Must be the same annuitant and owner
Who Needs It: Owners with old, outdated, or underperforming contracts.
Who Doesn’t: Those who are almost done with their surrender schedule and planning to cash out soon.
Also Consider: Add a GLWB rider for 5%–8% guaranteed lifetime income—ideal for retirement income planning.
3. Replace After the Surrender Period Ends (and Get a Bonus)
Key Stat: Surrender periods typically last 7–10 years.
Once the surrender period ends, there’s no penalty for switching. This is the best time to upgrade your annuity strategy—especially if you can move into a bonus annuity or one with strong income guarantees. You’re free to move your funds wherever you’ll get better value.
✔ No surrender penalty
✔ Freedom to shop for the best annuity
✔ Opportunity to boost income or reduce fees
✘ Could lose legacy benefits from the old annuity
✘ Still requires research and the replacement process
Who Needs It: Retirees shifting from saving to spending or wanting better benefits.
Who Doesn’t: Those who still benefit from older riders or guaranteed rates.
Helpful Tip: Choose an annuity with a bonus and GLWB rider to lock in high payouts, especially if income is your priority.
Insurance That Helps With Replacements
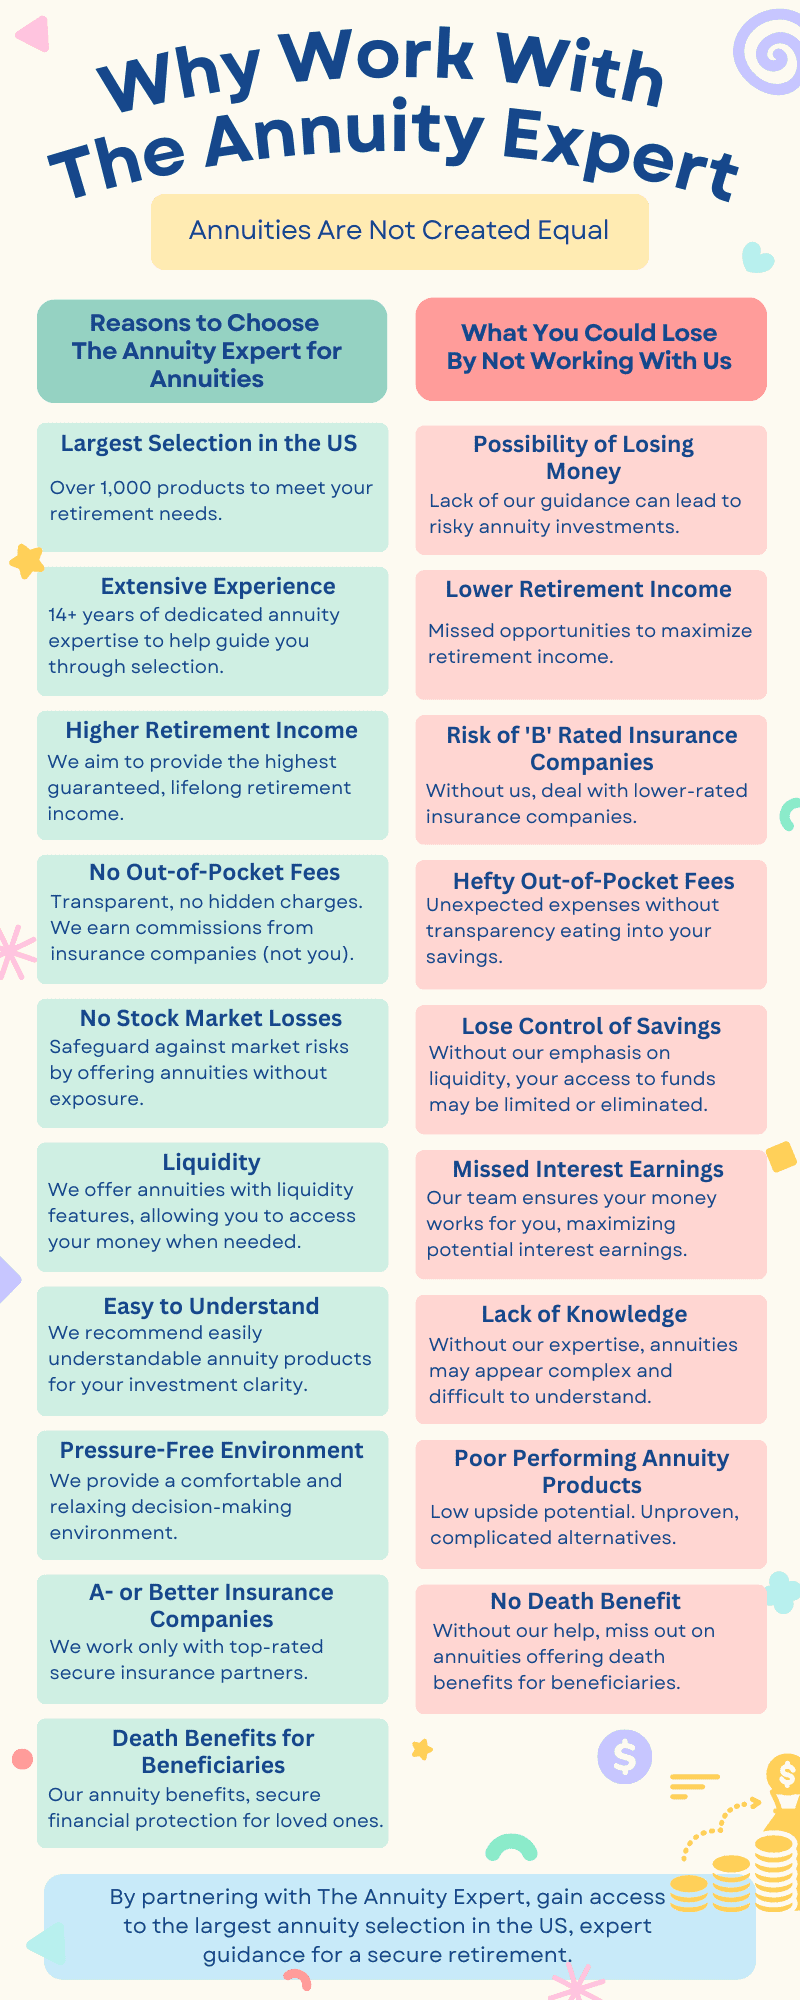
- Bonus Annuities: Help recoup surrender charges or lost growth by adding upfront value (typically 5%–10%).
- Fixed Index Annuities with GLWB: Provide lifetime income with protection from market loss.
- Deferred Income Annuities (DIAs): Great if you want income in 5–10 years and don’t need access to funds now.
- Long-Term Care Riders: Replace your old contract if it doesn’t cover future care costs.
Book A Call
Yes, you can replace an annuity—but timing is key. Use bonus annuities to recover surrender fees or lost growth, and upgrade to modern features like lifetime income riders and inflation protection. Don’t stay stuck in a contract that no longer serves your goals.
Contact The Annuity Expert for free quotes, personalized comparisons, and help choosing the right bonus annuity for your situation—no obligation, just thoughtful planning.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
How does a 1035 exchange work?
A 1035 exchange allows you to replace your annuity without immediate tax consequences by directly transferring funds to the new annuity.
What are surrender charges?
Surrender charges are fees you pay for withdrawing funds from an annuity before a specified period ends. These can significantly impact your decision to replace an annuity.
Can replacing an annuity save me money?
It depends. While you might find an annuity with lower fees or better terms, you must consider surrender charges and potential tax implications. Additionally, seek annuities with premium bonuses to help offset any losses.