

Why This Topic Matters
Life insurance is commonly believed to be tax-free, but the truth is more nuanced. While most death benefits are paid to beneficiaries tax-free, certain events—such as policy surrenders, unpaid loans, or owning the policy yourself—can trigger income, estate, or gift taxes. Without the right structure and planning, your beneficiaries could face an avoidable tax liability, and your legacy could be diminished.
This guide is written for first-time readers who may not be familiar with how life insurance interacts with the U.S. tax code. We’ll explain everything in plain language, using real-world examples and actionable strategies.
When Life Insurance is Generally Not Taxable
Most people purchase life insurance for its primary benefit: to provide a tax-free death benefit to loved ones. In many common situations, life insurance avoids taxation completely.
Income Tax-Free Scenarios
- Death Benefits: If you name individual beneficiaries (like a spouse or child), they receive the full death benefit without owing any federal income tax.
- Why This Is Unique: Unlike IRAs or 401(k)s, life insurance benefits are not considered taxable income.
- Policy Loans: Whole life and universal life policies build cash value over time. You can borrow from this amount tax-free, as long as the policy doesn’t lapse.
- Why This Is Unique: Loans do not count as income. You’re essentially borrowing your own money.
- Accelerated Death Benefits: If the insured becomes terminally or chronically ill, many policies allow early access to the death benefit. These payouts are tax-free under IRS rules.
- Dividends from Whole Life Policies: These are usually considered a return of premiums and are tax-free up to the total premiums paid.
Estate Tax-Free Scenarios
- Ownership Outside Estate: If the policy is owned by an irrevocable life insurance trust (ILIT) or another person, the death benefit is not included in the insured’s taxable estate.
- Policy Held for Over Three Years: If the policy ownership was transferred to someone else more than three years before the insured’s death, it avoids estate taxes.
Gift Tax-Free Scenarios
- Beneficiary Payments: Beneficiaries receiving the death benefit do not incur gift tax.
- Premium Payments Below Gift Tax Exclusion: Paying premiums for someone else’s policy does not trigger gift tax if the amount is within the annual exclusion limit.
Other Tax-Free Situations
- Policy Exchanges: Under Section 1035, exchanging one life insurance policy for another (or for an annuity) is tax-free.
- Withdrawals up to Cost Basis: Partial withdrawals are tax-free up to the amount of premiums paid into the policy.
- Group Life Insurance: Employer-provided group life insurance coverage up to $50,000 is tax-free to employees.
- Charitable Donations: Death benefits left to a charity are not taxable.
Situations Where Life Insurance Can Be Taxable
Life insurance proceeds are typically tax-free to beneficiaries, but there are scenarios when taxes may apply. Here are the key cases:
Income Tax
- Gain on Policy Surrender: If you surrender a policy for cash value, any amount exceeding the total premiums paid is taxable as income.
- Real Example: You paid $40,000 in premiums and received $60,000 when surrendering. The $20,000 is taxed.
- Policy Loans Not Repaid: Unpaid loans become taxable if the policy lapses or is surrendered, with gains above premiums taxed as income.
- Modified Endowment Contracts (MECs): If a permanent life policy becomes a MEC, non-annuity distributions (including loans) are treated as coming from taxable gain first and then from basis. Only the portion allocable to gain is included in income. The taxable portion may also face a 10% additional tax before age 59½ unless an exception applies.
- Interest on Delayed Death Benefits: Interest paid on death benefits held by the insurer is taxable.
Estate Tax
- Ownership in Estate: If the policyholder owns the policy at death, the death benefit is included in the taxable estate.
- Transfer of Ownership: If the insured dies within three years of transferring ownership, the benefit is included in their estate.
Gift Tax
- Premium Payments on Another’s Policy: Paying premiums for a policy owned by someone else can be considered a taxable gift if it exceeds annual gift tax exclusions.
Corporate-Owned Life Insurance (COLI)
- Non-Qualified Beneficiary: Benefits may be taxable if proper notice and consent requirements aren’t met.
- Split-Dollar Life Insurance: Taxation depends on the agreement, including the employee’s taxable benefit.
Group Life Insurance
- Coverage Over $50,000: The cost of employer-provided coverage exceeding $50,000 is taxable as imputed income to the employee.
Foreign Ownership
- U.S. Expatriates: Life insurance owned abroad may have tax implications under U.S. tax laws.
Strategies to Minimize Tax Implications
- Irrevocable Life Insurance Trust (ILIT): Establishing an ILIT can effectively remove the life insurance proceeds from your taxable estate, potentially saving significant estate taxes.
- Structuring Ownership: Ensuring that the intended beneficiary owns the policy or trust rather than the insured can help avoid estate tax issues.
- Avoid MEC Classification: Work with an advisor to make sure your premium payments follow IRS guidelines to avoid losing tax-free access to cash value.
- Regular Reviews: Periodically review your life insurance policy in light of changing tax laws. Adjusting ownership or beneficiaries as needed can help you stay compliant and minimize taxes.
- Use a 1035 Exchange to Improve Tax Efficiency: You can replace an underperforming or unwanted policy with a better one, without paying taxes on the gains.
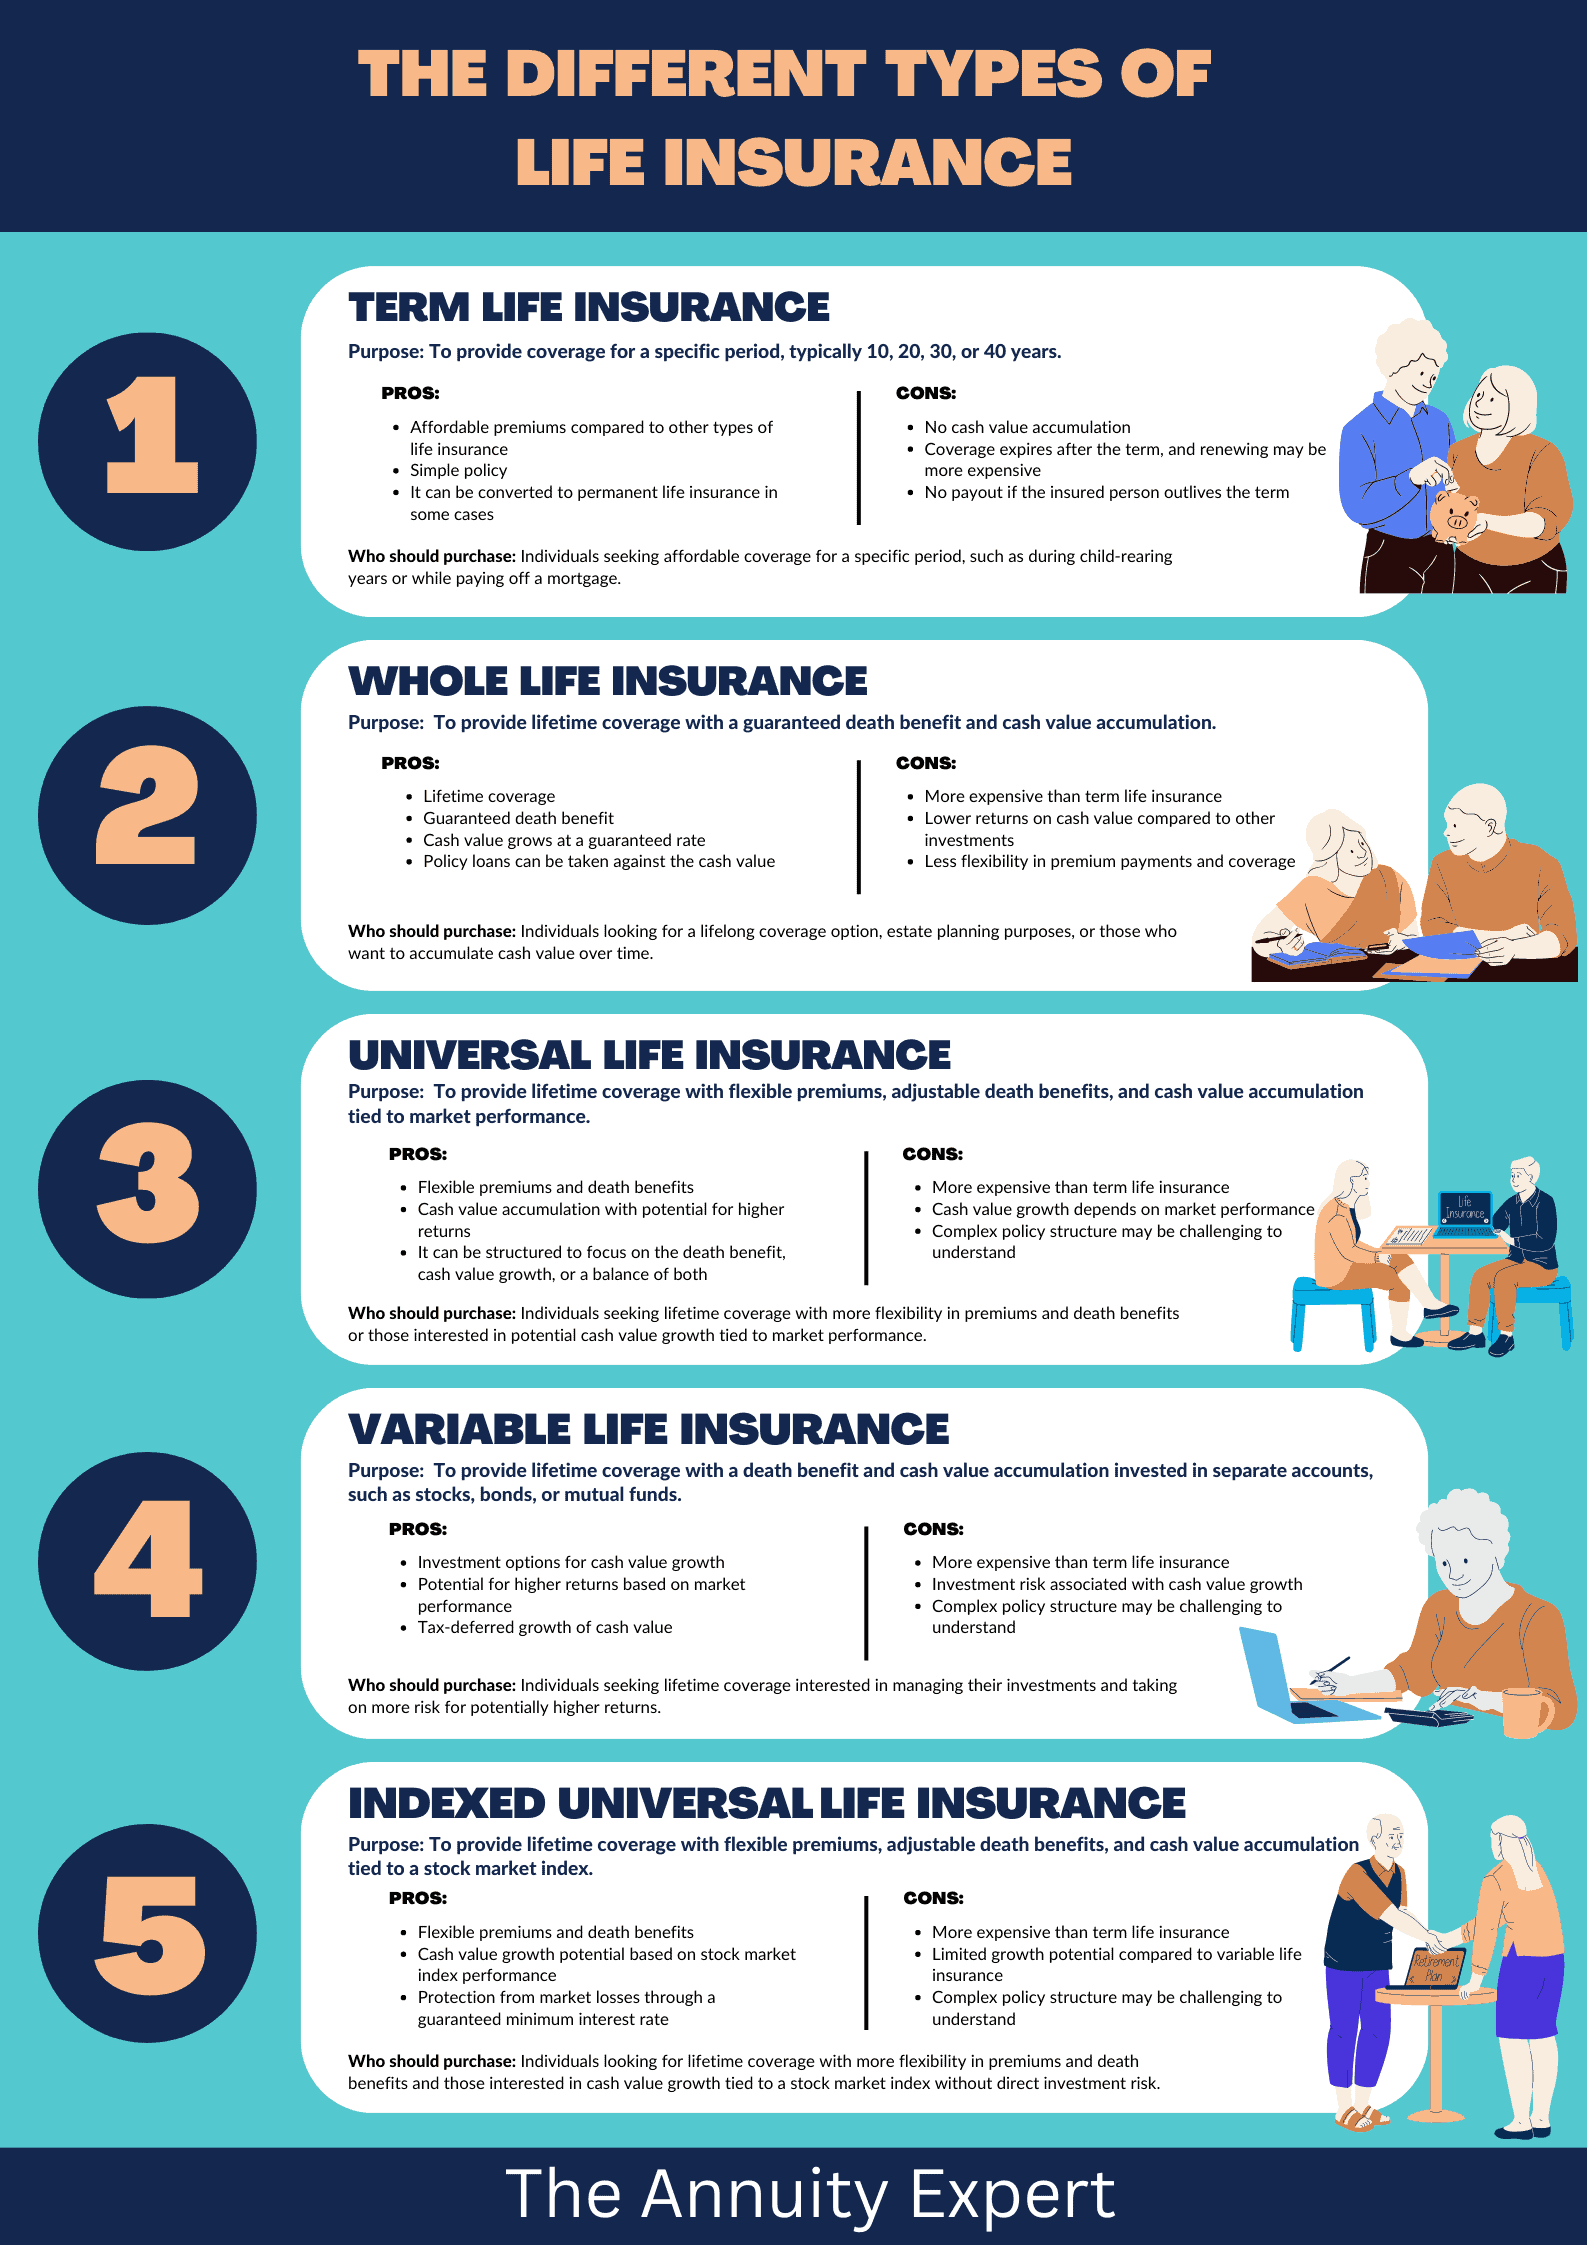
Insurance Products That Can Help
Fixed Indexed Annuities (FIAs)
Use a 1035 exchange to roll life insurance cash value into an FIA, which earns interest based on a market index or fixed rate, and can be structured to provide guaranteed income for life.
Long-Term Care Life Insurance
Permanent life insurance with long-term care riders allows early access to death benefits for qualifying care expenses, tax-free.
Survivorship Life Insurance
Ideal for estate planning, these policies pay only after both spouses pass and are often used to cover estate taxes or leave a legacy.

Who Should Pay Attention
- High-net-worth families (estate planning needs)
- Retirees accessing cash value
- Business owners with key person or COLI plans
- Parents funding life insurance for children
- Anyone gifting policies or premium payments
What Happens If You Don’t Plan Correctly
- Your beneficiaries may owe unexpected taxes
- You could forfeit years of tax deferral on gains
- The estate tax could consume 40% or more of your death benefit
- Your policy may become a MEC without warning
Get Help Now
Book A Free Consultation
Speak with a licensed expert. We’ll review your policy and provide personalized advice—free of charge.
Have a Question?
Submit your inquiry below. We’ll respond with helpful advice.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
Are life insurance payouts taxed?
Generally, when you get life insurance money because someone has died, the government doesn’t tax the money. But if you earn interest from the life insurance company, that is taxed, and you should report it as income.
Do you pay taxes on life insurance?
No, life insurance payouts are not subject to income tax. This means beneficiaries will receive 100% of the life insurance death benefit amount.
Can the IRS take money from life insurance?
No, the IRS cannot take money from life insurance. Life insurance proceeds are typically exempt from taxation.
Is life insurance over $50,000 taxable?
No, life insurance policies exceeding $50,000 are not taxable. In addition, life insurance proceeds are typically exempt from taxation.
Can creditors go after life insurance?
No, creditors cannot go after life insurance. Life insurance proceeds are typically exempt from taxation.
Does a life insurance payout affect Social Security benefits?
No, a life insurance payout does not affect Social Security benefits.
How much money can you inherit without having to pay taxes on it?
No limit exists on how much money you can inherit from life insurance without paying taxes. Inherited money is typically not subject to taxation.
Are life insurance premiums tax-deductible?
Generally, life insurance premiums are not tax-deductible. This applies to personal life insurance policies where the insured pays the premiums. The IRS considers these premiums a personal expense, similar to groceries or clothing, which are not eligible for tax deductions.
Are life insurance cash value withdrawals or loans taxable?
Yes, if you withdraw more than the premiums you paid, the excess is taxable as ordinary income. Loans are tax-free as long as the policy stays in force, but if it lapses or is surrendered, outstanding loans may become taxable.
Are life insurance dividends taxable?
Not if treated as a return of premium. For example, dividends applied to reduce premiums aren’t taxed.