

Compare Globe Life Insurance With Other Companies
Scenario: You’re looking for affordable life insurance with no medical exam. You’ve seen Globe Life’s aggressive advertising—$1 coverage to start, simple applications, and guaranteed approval offers. But is it too good to be true? Before you buy, here’s what every American should understand about Globe Life and Accident Insurance Company—its credibility, what it does well, where it falls short, and what alternatives offer more value.
You can also use our calculator to compare Globe’s life insurance rates with life insurance quotes from other insurance companies.
1. They Are Legitimate With Strong Financial Ratings
Key Fact: Founded in 1951, Globe Life holds an “A” (Excellent) rating from A.M. Best and is backed by Globe Life Inc., a publicly traded company (NYSE: GL).
✔ Pros:
- ✔ In business for over 70 years
- ✔ Strong financial strength ratings (A from A.M. Best, AA- from S&P)
- ✔ Policies available in most states
- ✔ No medical exam for most policies
✘ Cons:
- ✘ No permanent life insurance with strong cash value growth
- ✘ Limited riders and customization options
- ✘ Frequently targets low-income households with simplified, high-cost coverage
Who Needs It and Why:
Someone who has serious health issues and cannot qualify elsewhere may find Globe Life’s no-medical exam policies convenient.
Who Doesn’t:
Anyone in relatively good health who can qualify for lower rates and better value elsewhere should avoid Globe Life. You’ll pay less for more coverage through a fully underwritten term or permanent policy.
2. Their Policies Often Appear Cheaper Than They Are
Key Fact: Globe advertises policies starting at $1, but the full premium kicks in after the first month and increases every five years.
✔ Pros:
- ✔ Simple sign-up process
- ✔ Immediate coverage for small amounts
✘ Cons:
- ✘ Premiums increase every five years
- ✘ Policies may lapse if you can’t afford the rising cost
- ✘ High premiums for the amount of coverage over time
Who Needs It and Why:
People needing short-term, low-coverage life insurance quickly.
Who Doesn’t:
Anyone looking for long-term affordability and predictability. A 20- or 30-year term policy from another insurer is usually much cheaper in the long run.
Helpful Add-on:
A term life policy with a conversion option or a permanent policy like whole life or guaranteed universal life provides predictable costs for life.
3. Globe Life Faces Serious Allegations of Misconduct
Key Fact: In 2024, short sellers accused Globe Life of fraudulent practices, including writing fake policies and abusive sales tactics. The company is under investigation.
✔ Pros:
- ✔ Globe Life has denied the allegations and continues to operate
✘ Cons:
- ✘ Subject of federal investigation
- ✘ Allegations include fake policyholders and forged documents
- ✘ Serious trust and credibility concerns surfaced
Who Needs It and Why:
If you’re already insured with Globe Life and healthy, you may consider keeping the policy temporarily while researching other options.
Who Doesn’t:
If you’re considering a new policy, these allegations are reason enough to look at other companies first.
Helpful Add-on:
Use an independent life insurance broker to compare quotes on your behalf from top-rated companies, free of charge and obligation.
4. High Complaint Ratio From Policyholders
Key Fact: The National Association of Insurance Commissioners reports that Globe Life’s complaint ratio is higher than the industry average.
✔ Pros:
- ✔ Globe Life holds an A+ rating from the Better Business Bureau
✘ Cons:
- ✘ Numerous customer complaints about billing, policy cancellations, and difficulty contacting support
- ✘ Customer service may not be responsive or helpful
Who Needs It and Why:
If you value a quick and easy sign-up more than long-term service quality.
Who Doesn’t:
If you expect strong customer support, transparency, and claims handling, choose another provider.

5. Limited Policy Options and Features
Key Fact: Most of Globe Life’s policies are simplified issue and graded benefit plans with lower face values and fewer customization features.
✔ Pros:
- ✔ Quick issue for basic coverage
- ✔ No medical exams needed
✘ Cons:
- ✘ No comprehensive permanent life insurance with cash value
- ✘ No advanced riders like long-term care or disability waivers
- ✘ Limited face amounts, often capped at $100,000 or less
Who Needs It and Why:
Someone who only needs a burial or final expense plan and cannot qualify elsewhere.
Who Doesn’t:
People who want a policy that builds cash value or offers living benefits like long-term care.
Also Consider:
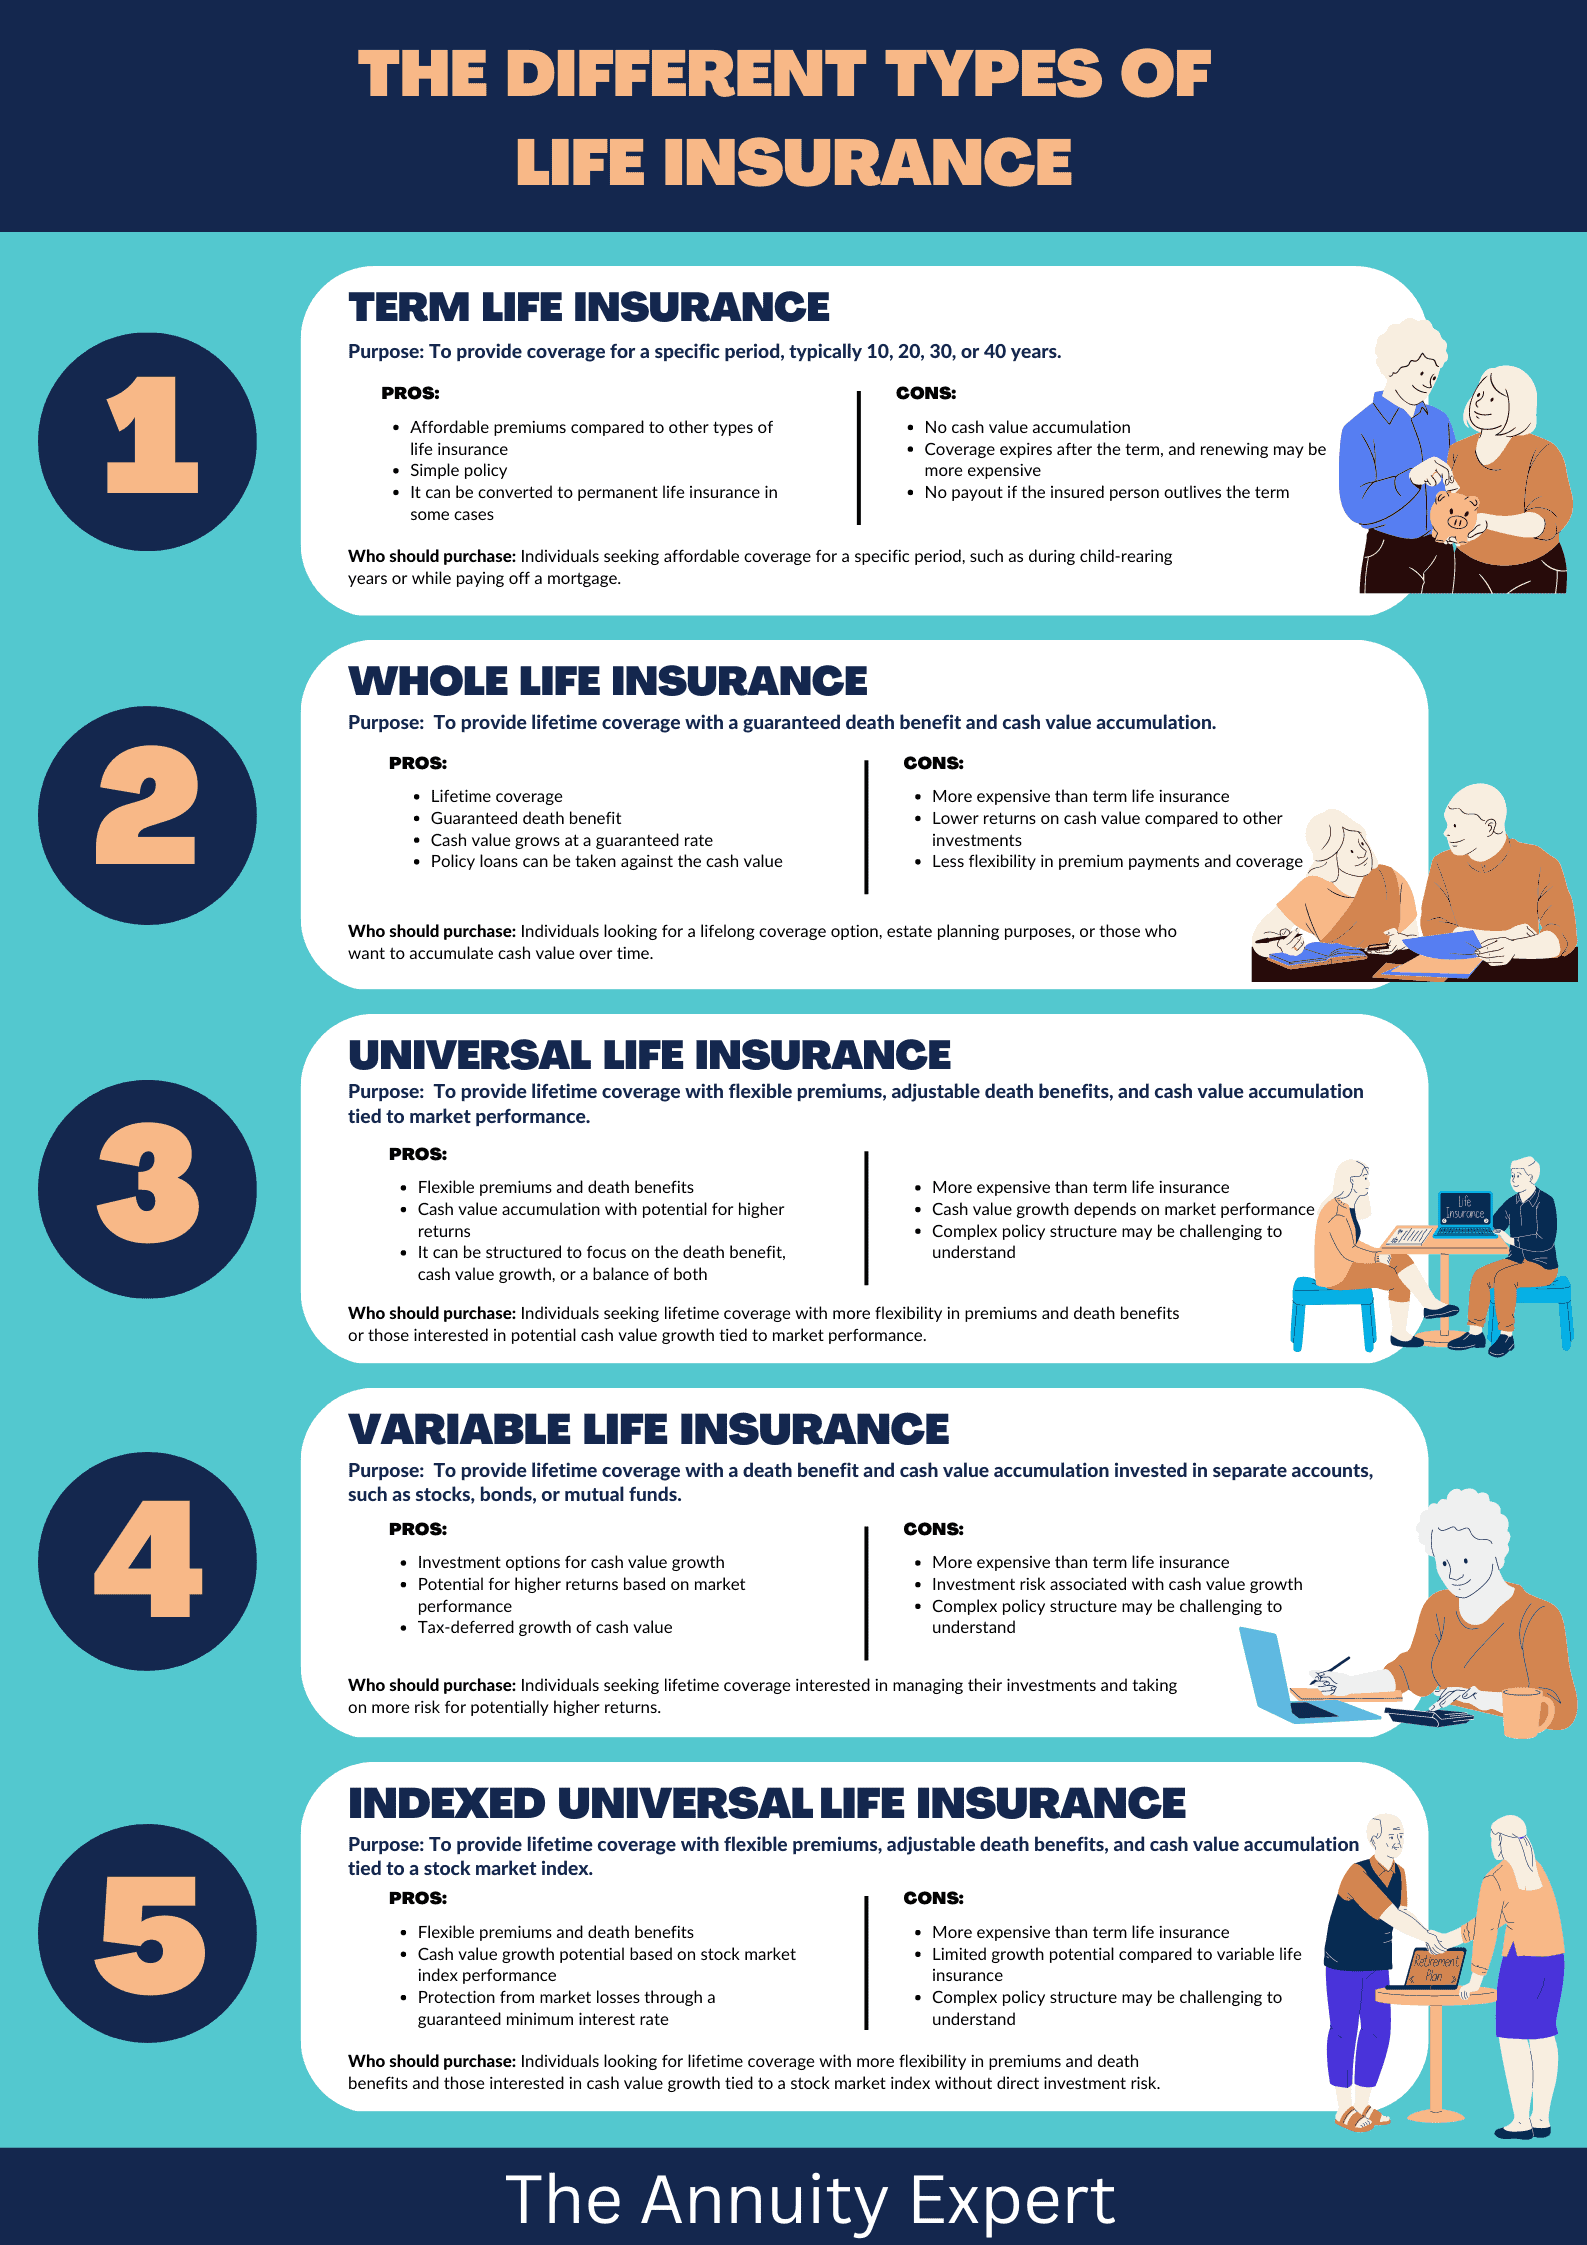
For those wanting permanent protection, a Whole Life Insurance or Indexed Universal Life (IUL) policy from a top-rated company offers better lifetime value and benefits.
6. Doesn’t Offer Long-Term Price Lock
Key Fact: Globe Life’s term life premiums increase every five years—meaning your costs rise as you age, which can make coverage unaffordable.
✔ Pros:
- ✔ No surprise if you’re aware of the structure
- ✔ Flexible if you only need short-term coverage
✘ Cons:
- ✘ Premiums rise substantially with age
- ✘ No level-term or permanent price guarantee
Who Needs It and Why:
Someone who expects to cancel the policy within five years.
Who Doesn’t:
If you want fixed costs, a traditional Level Term Life Insurance or Guaranteed Universal Life policy is a better long-term solution.
7. There Are Better Alternatives With More Benefits
Key Fact: Many companies offer term and permanent life insurance with stronger benefits, better pricing, and higher coverage amounts.
✔ Pros:
- ✔ Globe Life makes insurance accessible to almost anyone
✘ Cons:
- ✘ Not the best value
- ✘ Lack of living benefits, low customization, and poor pricing over time
Who Needs It and Why:
Someone who has no other coverage options and understands the limitations.
Who Doesn’t:
Anyone who qualifies for medically underwritten life insurance should work with a broker to compare more competitive options.
Speak To A Broker First—Not A Call Center Rep
Before signing up with Globe Life, compare policies from 25+ top-rated insurers. The Annuity Expert is an independent broker—our agents offer personalized comparisons and quotes at no cost to you. We’ll help you find better value and stronger coverage tailored to your needs.
👉 Contact The Annuity Expert today for free quotes and side-by-side comparisons.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Related Reviews
- Colonial Penn Life Insurance
- Allstate Life Insurance
- American Family Life Insurance
- Erie Life Insurance
- Farmers Life Insurance
- Geico Life Insurance
- AAA Life Insurance
- Prudential Life Insurance
- State Farm Life Insurance
- Progressive Life Insurance
- USAA Life Insurance
- Gerber Life Insurance
- Ethos Life Insurance
- Protective Life Insurance
- American General Life Insurance
- Banner Life Insurance
- Transamerica Life Insurance