

Compare Term Life Insurance Quotes and Rates to Find the Best Coverage for Your Budget
Who we are: The Annuity Expert is an independent term life insurance agency. We compare policies from top-rated insurers nationwide to help you buy the right term life insurance at the lowest cost. Our goal is to make sure you get affordable coverage that fits your family’s needs—without overpaying or missing important features.
Helpful Tip: This page focuses on standard level term lengths and rates for all ages. If you are specifically looking for a pricing breakdown tailored to mature applicants, see our guide to life insurance quotes over 50.
What Is Term Life Insurance And How Does It Work?
Term life insurance is a type of life insurance policy that provides coverage for a specific period, or “term.” Term life insurance provides coverage for a specified period, typically ranging from 10 to 40 years. If the policyholder dies during the term, their beneficiaries receive a death benefit. If the term expires while the insured is still alive, coverage will end unless it is renewed or converted to a permanent policy. It’s straightforward, without the bells and whistles of other insurance types.
Why it’s unique: Term life is the most affordable way to protect your income, mortgage, and family’s future for a specific period of time.
If you’re over 50 and still working, start with our life insurance for over 50 page to compare term policies built for your age budget and how long you need coverage.
Expert Insight: Level term is essentially a commodity, meaning the policy works exactly the same way regardless of who you buy it from. Your main goal is simply finding the cheapest rate among the best life insurance companies.
Who Needs Term Life Insurance?
- Families: To replace income and ensure dependents are financially secure. Term life insurance helps protect your family’s financial future by providing funds to cover everyday expenses and replace lost income.
- Young professionals: To lock in lower premiums while young and healthy.
- Homeowners: To cover mortgage payments if a primary earner passes away.
- Business owners: To protect partners and secure business continuity.
- Parents: To fund children’s education if something happens.
Term life insurance can provide financial security for those who depend on your income.
Who Doesn’t Need It?
- Retirees with savings: If you have enough assets to cover end-of-life expenses.
- High-net-worth individuals: If estate planning is the goal, permanent life insurance may be a better option.
- People needing lifelong coverage: Whole or universal life insurance may be more suitable.
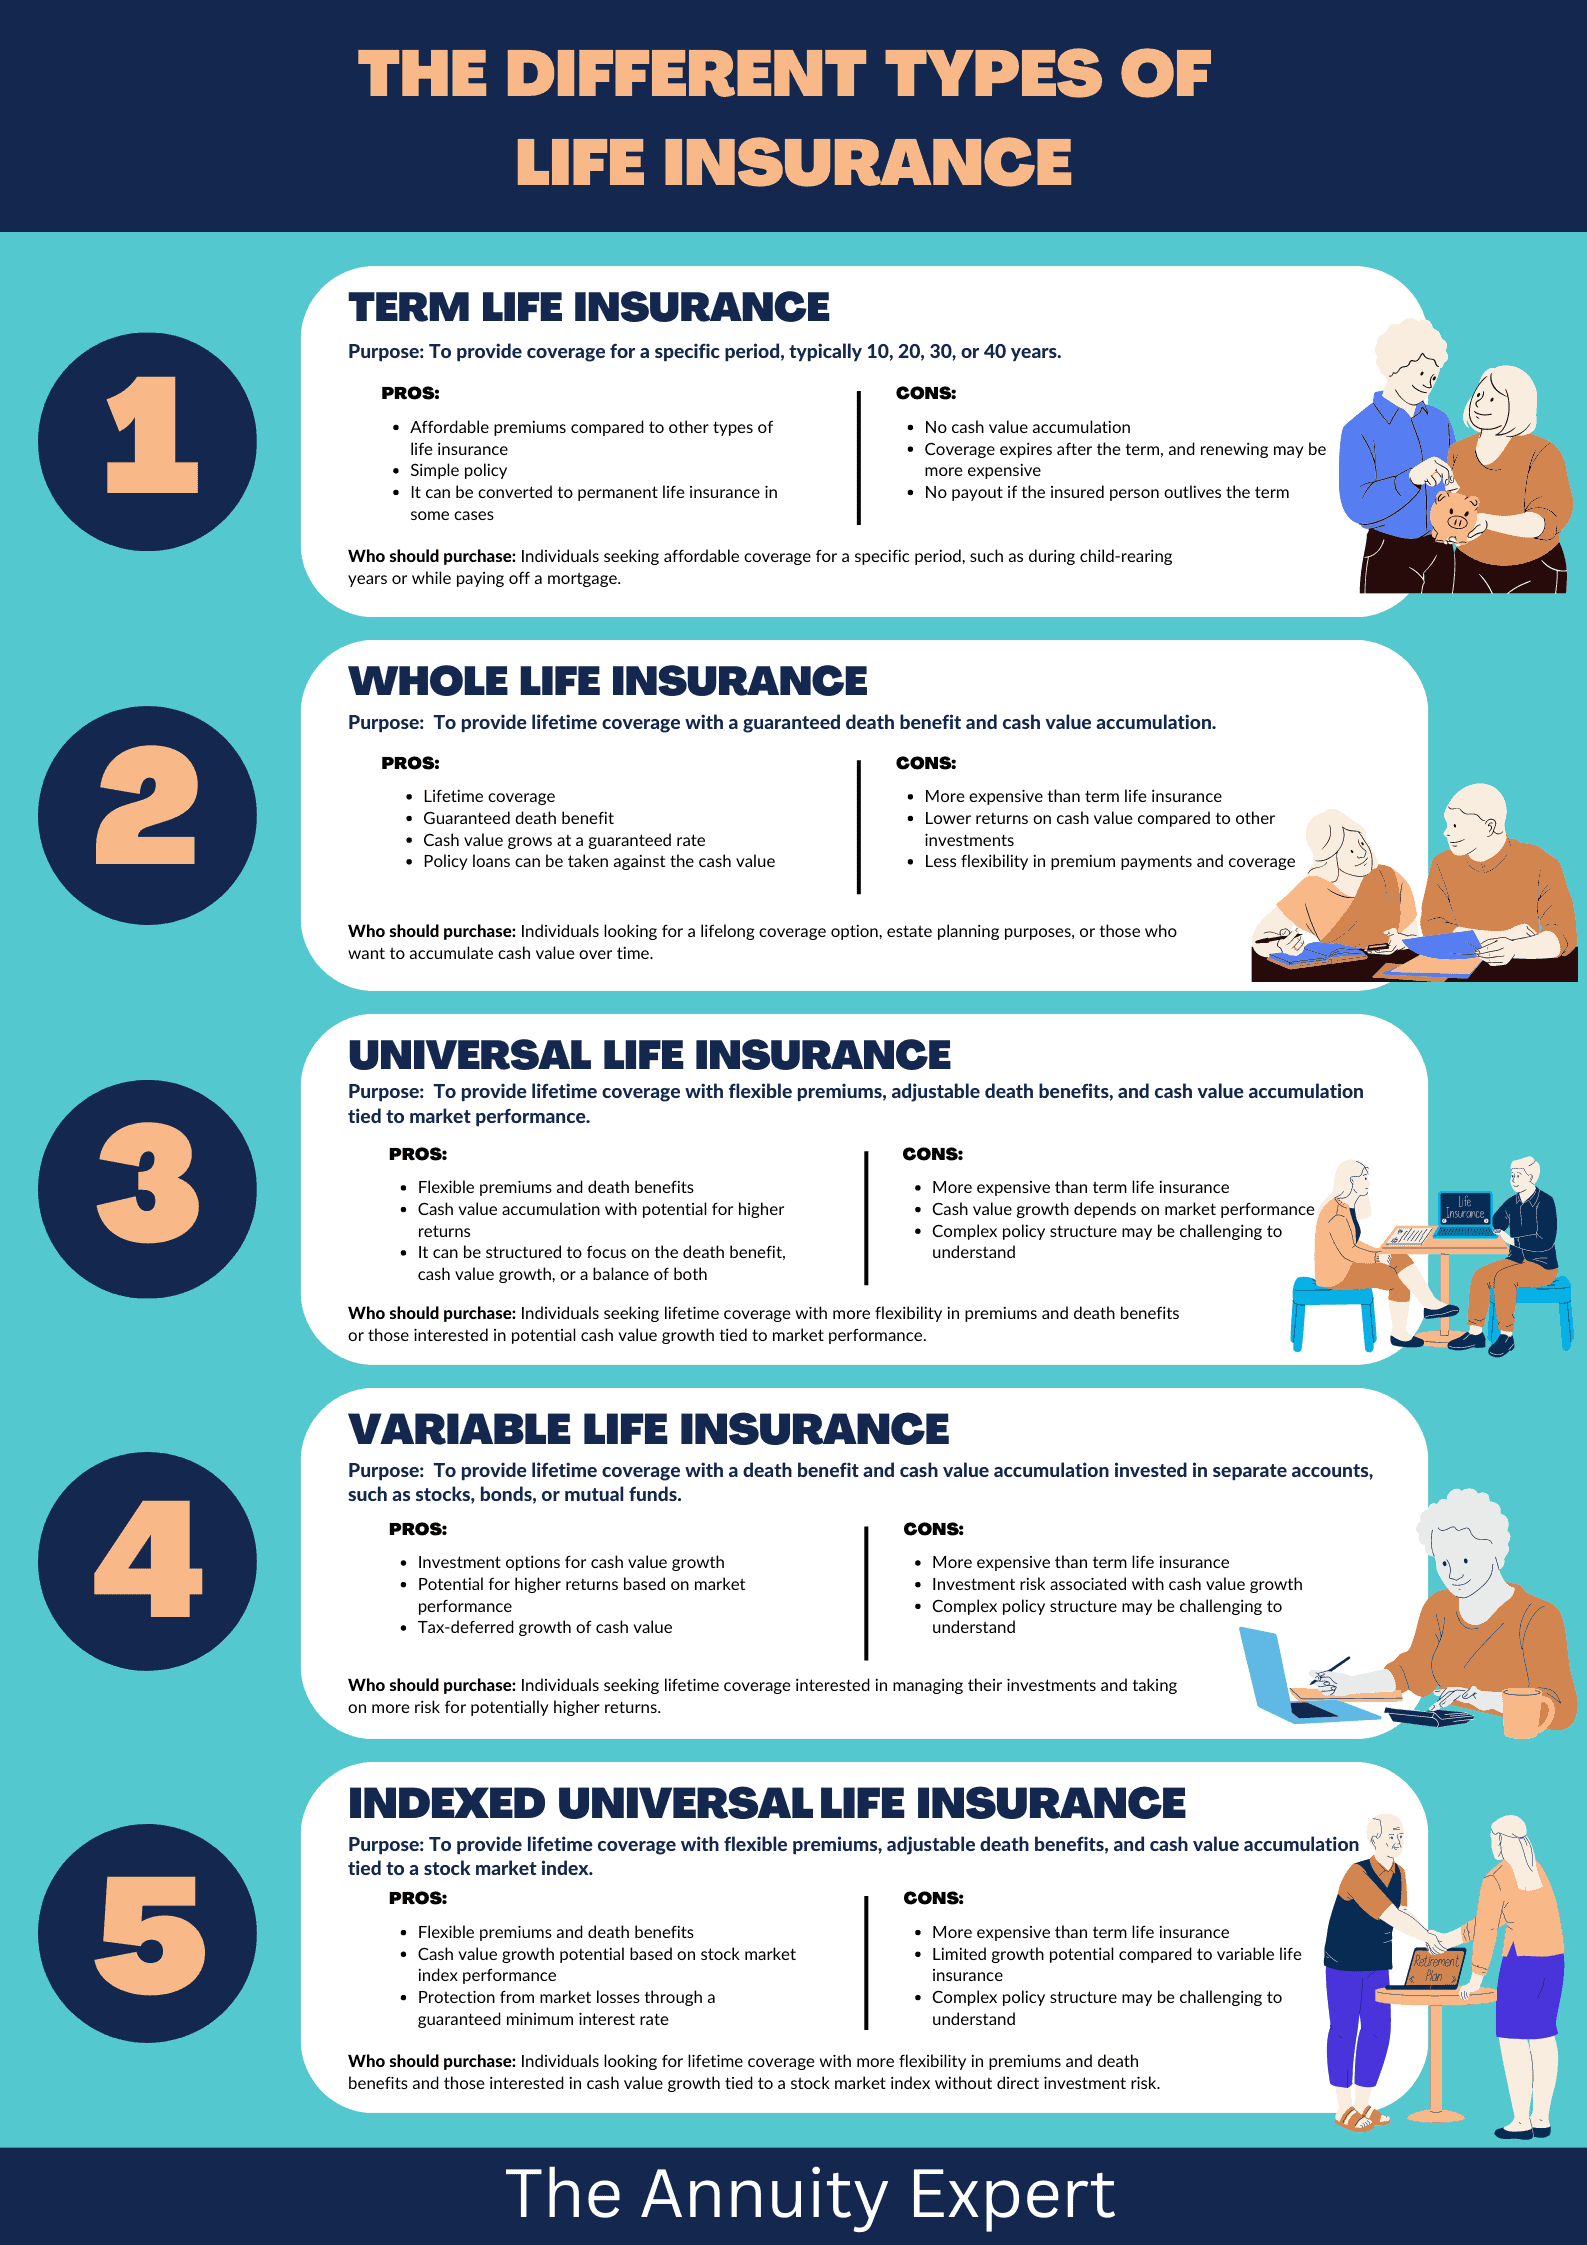
Types of Term Life Insurance We Sell
1. Level Term Life Insurance
- Coverage lasts for a fixed period with fixed premiums.
- Common terms: 1, 5, 10, 15, 20, 25, 30, and 40 years.
- Best for: Individuals seeking stable and predictable payments.
Use our term life insurance calculator to help decide which policy to choose.
2. Decreasing Term Life Insurance
- Death benefits decrease over time, while premiums remain constant.
- Typically used to cover loans or mortgages.
- Best suited for: Homeowners or individuals with large debts that are decreasing over time.
3. Renewable & Convertible Term Life Insurance
- Renewable: Includes options like annual renewable term, where coverage is renewed each year, often resulting in paying higher premiums as you age. Some policies allow renewal or conversion only up to a specified age. A diagnosis of terminal illness may affect your ability to renew or convert your policy.
- Convertible: Can be converted into a whole or universal life without new underwriting.
- Best for: Those who may need permanent coverage later.
4. Return of Premium Term Life Insurance
- If you outlive the policy, premiums are refunded.
- More expensive than standard term insurance.
- Best for: Those who want a safety net if they outlive their policy.
Helpful Tip: Contact The Annuity Expert to get a term life insurance quote to compare policy prices and find the most suitable option for you.
Choosing the Right Term Length
10-Year Term Life Insurance
- Lowest cost option for short-term needs.
- Best for: Covering temporary financial obligations, such as a small business loan.
15-Year Term Life Insurance
- Moderate duration with level premiums.
- Best for: Parents with teenagers who need coverage until college is completed.
20-Year Term Life Insurance
- Provides long-term financial security.
- Best for: Homeowners with a 20-year mortgage or young families.
25-Year Term Life Insurance
- Long enough for most major life goals.
- Best for: Covering long-term debt, income replacement, or children’s college.
30-Year Term Life Insurance
- One of the longest standard options.
- Best for: Individuals seeking lifelong coverage at an affordable cost.
40-Year Term Life Insurance
- The longest term available.
- Best for: People who want near-permanent coverage at term rates.
Tip: If unsure, choose a longer term. Buying new coverage later is often more expensive, especially if your health changes.
Ready to compare actual rates for your age and health? Connect with a term life insurance broker to scan 50+ top-rated carriers for the best price today.”
How Much Term Life Insurance Do You Need?
- Multiply your annual income by 10-15 times.
- Add outstanding debts (mortgage, loans, credit cards).
- Factor in future expenses (college tuition, retirement savings).
- Subtract existing savings and life insurance policies.
Ensure your policy’s death benefit is sufficient to cover your family’s expenses, debts, and future needs, thereby providing them with financial security.
Expert Tip: Determining the right coverage amount involves more than just a 10x income rule of thumb. To get a precise estimate based on your specific debts and family goals, use our term life insurance calculator before selecting your final policy amount.
Pros And Cons Of Term Life Insurance
- Pros:
- Affordability: Lower initial costs compared to whole life insurance.
- Simplicity: Straightforward policies without complex investment components.
- Flexibility: Various term lengths to match your specific needs.
- Cons:
- No Cash Value: Unlike whole-life policies, term insurance does not accumulate cash value or build cash value over time.
- Temporary Coverage: Only provides protection for the chosen term length, after which you may need to renew at higher rates.
What Affects Your Premium?
Premiums depend on:
- Age: The younger you are, the cheaper your premium.
- Health: Good health = lower rates. Medical conditions raise premiums.
- Gender: Women usually pay less because of longer life expectancy.
- Tobacco use: Smokers pay 2–3× more than non-smokers. (We have a way around this.)
- Policy details: Higher coverage amounts and longer terms cost more.
- Lifestyle: Engaging in high-risk jobs or hobbies (such as flying planes, scuba diving, or racing) can increase costs.
Sample Monthly Premiums for a $500,000 Policy
| Age | 10-Year Term | 20-Year Term | 30-Year Term |
|---|---|---|---|
| 30 | $13-$20 | $18-$30 | $30-$45 |
| 40 | $20-$30 | $30-$45 | $50-$75 |
| 50 | $45-$65 | $75-$110 | $130-$180 |
How to Get the Best Term Life Insurance Rates
- Compare Quotes: Obtain multiple quotes from top insurance providers. Use an independent broker (like The Annuity Expert!) to compare rates and find the best life insurance company for your needs.
- Buy Young: The younger you are, the lower the rate.
- Stay Healthy: Non-smokers and those with good health pay less.
- Choose the Right Term: Avoid overpaying for unnecessary years of coverage.
- Consider No-Exam Policies: Some life insurance companies offer term life without a medical exam, including guaranteed approval policies that require only a few health questions and no medical exam.
Expert Advice: Finding the lowest premium requires an independent market scan of over 50 carriers. To see which companies are currently offering the most competitive level rates for your health class, you can buy term life insurance directly through our brokers today.
Top Companies For Term Life Insurance
- Banner Life: Known for competitive rates and excellent customer service.
- Pacific Life: Offers a variety of term lengths and robust policy options.
- Corebridge: Provides flexible term policies with customizable features.
Important Note: While level term is the most affordable and straightforward option for temporary needs, it does not build cash value or last your entire life. If you need coverage for estate planning or lifelong protection, compare this product against the other types of life insurance to find the best fit for your long-term goals.
Term Life vs. Whole Life Insurance
| Feature | Term Life Insurance | Whole Life Insurance |
|---|---|---|
| Coverage Length | Fixed term (10-40 years) | Lifetime |
| Premiums | Lower | Higher |
| Cash Value | None | Yes |
| Best for | Income replacement, debt coverage | Estate planning, lifelong needs |
A life policy can be either term or permanent. Permanent life policies include whole life and variable life insurance, with variable life insurance offering investment features and flexibility in premiums and death benefits.
Expert Recommendation: While level term is the most affordable choice for most families, it’s important to understand the alternative. We recommend you read our full breakdown of whole life vs. term life insurance to see if you actually need the permanent guarantees and cash value growth of a whole life policy.

How to Apply for Term Life Insurance
- Get a Quote: Compare rates from different providers.
- Choose Your Coverage: Pick the right term length and amount.
- Complete an Application: Provide health and lifestyle information.
- Medical Exam (if required): The insurer may request a physical examination.
- Approval & Policy Issue: If approved, pay the premium and activate coverage.
Group term life insurance may also be available through employers as an alternative to individual policies.
Underwriting Options
- Fully underwritten: Includes a medical exam and labs; usually the lowest rates.
- Accelerated/no-exam: Quick approval for healthy applicants; slightly higher rates.
- Simplified issue: No exam, just health questions; higher cost, lower coverage limits.
Riders That Enhance Coverage
- Accelerated Death Benefit: Access a payout early due to terminal/critical illness.
- Waiver of premium: Keeps the policy active in the event of disability.
- Child rider: Covers children; converts later as they get older.
- Accidental death benefit: Extra payout for accidental death.
Common Mistakes to Avoid
- Buying too short a term to save money up front
- Missing conversion deadlines
- Relying only on employer life insurance (not portable)
- Skipping comparison shopping across insurers
Ready to Compare Term Life Insurance Quotes?
Work with an independent agency that represents you, not just one insurer. We’ll compare quotes, explain the fine print, and help you buy the right coverage at the best rate. Contact The Annuity Expert for free quotes to buy coverage.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
What happens when your term insurance expires?
In most cases, when your term life insurance policy expires, you essentially become uninsured. If something were to happen to you after the policy term, your beneficiaries would not receive any death benefit. The coverage ends, and you’re no longer paying premiums.
Do you get money back after it has expired?
Standard-term life insurance policies do not offer a return of premiums at the end of the term. So, if you outlive your term life insurance policy, you generally do not get any money back unless you have a return of premium (ROP) term life insurance policy.
What happens if I live longer than my term life insurance?
If you live longer than your term life insurance, the policy will expire, and you will not receive a death benefit. Instead, the policyholder must purchase a new policy or opt for a different form of coverage.
Does term life insurance have cash value?
No, term life insurance policies do not have cash value. The premiums paid towards a term life insurance policy are solely used to provide death benefit coverage. Once the policy term ends, the coverage ends, and there is no cash value component. Term life insurance is designed to provide affordable life insurance coverage for a specific period, and the premiums are significantly lower than those of permanent life insurance policies.
What happens at the end of term life insurance?
When your term life insurance policy ends, you have a few different options. You can renew your policy, convert your policy, or let your policy lapse.
What is level premium term life insurance?
Level premium term life insurance is a type of life insurance policy where the premium payments remain consistent throughout the term. This allows policyholders to budget for their insurance premiums more quickly, as there won’t be any unexpected increases in their payment amounts. As the name suggests, it covers a specified term, such as 10, 20, or 30 years.
Which component increases in the increasing term insurance?
The death benefit is the main component of an increasing term life insurance policy. As you age, the death benefit will increase, providing your loved ones with more financial protection in the event of your passing.
How much does life insurance cost for a 50-year-old male?
For a healthy 50-year-old man wanting a $500,000 policy, the average monthly premium for a 20-year term policy is $79.
How much does life insurance cost for a 50-year-old female?
For a healthy 50-year-old woman wanting a $500,000 policy, the average monthly premium for a 20-year term policy is $63.
How do I sell my term life insurance?
To sell your term life insurance policy, you can consider a life settlement or viatical settlement company. These companies purchase life insurance policies from policyholders for a lump sum. Research reputable companies, gather your policy documents, and compare offers. Remember that selling your policy may have tax implications and affect your beneficiaries.
Can you borrow against term life insurance?
No, you cannot borrow against term life insurance. Term policies do not accumulate cash value, which is necessary for taking out a loan.
Can a 60-year-old get term life insurance?
Yes, a 60-year-old can get term life insurance. Many insurers offer policies to older applicants, though premiums will be higher compared to those of younger individuals.
When does term life insurance end?
Term life insurance ends when the specified term (e.g., 10, 20, or 30 years) expires. At that point, coverage ceases unless renewed or converted to a permanent policy.
Does term life insurance have a waiting period?
Typically, term life insurance does not have a waiting period. Coverage usually begins immediately after policy approval and the first premium payment.
How much term life insurance do I need?
The amount of term life insurance you need depends on factors like your income, debts, future expenses, and financial goals. A common rule is to get coverage equal to 10-12 times your annual income.
Do term life insurance premiums increase each year?
Term life insurance premiums are usually fixed for the duration of the term. However, with yearly renewable term policies, premiums increase annually.
Why is term life insurance the best option for a young adult?
Term life insurance is the best option for a young adult because it offers affordable premiums, straightforward coverage, and financial protection during the years when they might have significant debts or dependents.
Who offers the best-priced term life insurance?
Banner Life is often recognized for offering competitively priced term life insurance, providing affordable rates and comprehensive coverage options.
Why is life insurance so cheap?
Life insurance, especially term life, is cheaper because it offers coverage for a limited period without accumulating cash value. Premiums are based on the low risk of the insured passing away during the term, making it an affordable option.
When should I stop buying term life insurance?
You should consider stopping term life insurance when your financial obligations decrease, such as when your mortgage is paid off, your children are financially independent, or you have sufficient savings and investments for your dependents.
Can you extend term life insurance?
Yes, you can extend term life insurance by renewing it at the end of the term or converting it to a permanent policy, though premiums may increase.
Why doesn’t everyone buy term life insurance on healthy parents in their 50s as a “windfall” strategy?
The main reason is that life insurance is priced to match life expectancy, so insurers rarely underprice the risk enough to make it a “sure bet.” A healthy person in their early 50s statistically has a good chance of living into their 80s, meaning the odds of the policy paying out during a 30+ year term are lower than many think. If they outlive the term, you lose every premium dollar with no return.
Also, you generally can’t take out a policy on someone unless you can prove an insurable interest (financial dependence or liability), and many insurers won’t approve a large policy solely for inheritance purposes. Underwriting may also raise rates if your parent develops health issues during the application process.
If your goal is inheritance planning, other strategies—like permanent life insurance designed to last for life, or investing premiums into a growth portfolio—might offer more predictable outcomes. Permanent coverage guarantees a payout but costs far more than term.
How long should a 29-year-old choose for a term life insurance policy, and how much coverage should they get?
Since you’re 29, planning to buy a home, and getting engaged, you’ll want coverage that protects your future spouse and any potential dependents until major financial obligations are gone. Most people in your position choose a 20–30 year term—long enough to cover a mortgage payoff window and high-earning years. Coverage amounts are typically 10–15× your annual income, which would put you around $700k–$1M. If you plan to have kids or take on a large mortgage, err on the higher side. Locking in a longer term now ensures lower premiums for the entire period, even if your health changes later.
Should I port my old employer’s life insurance or buy a new term policy?
At 44, porting your employer’s policy means you’ll keep the $256K coverage but pay $1,700 annually with rates increasing every year, making it less cost-effective long-term. A new 20-year term policy for $1M at a fixed $2,100 yearly premium locks in much more coverage at a predictable cost. Even with a higher BMI now, securing coverage avoids the risk of being denied later if your health changes. If you lose weight and improve your health within the next couple of years, you can reapply for a new policy at lower rates and either replace or supplement the current one. Some life insurance companies even offer a “rate review” after two years, allowing them to reevaluate your improved health and potentially make your premiums substantially cheaper without requiring a brand-new application. This strategy balances immediate protection with the flexibility to reduce costs later.
What is the best term life insurance?
The best policy offers the right coverage amount and term length at the lowest premium from a financially strong insurer. The Annuity Expert can compare multiple carriers to find your best option.
Where to buy term life insurance?
An independent insurance agency, such as The Annuity Expert, can shop multiple insurers for you to find the best rates and coverage.
How can I buy term life insurance online?
You can compare quotes, apply online, and complete any required health screenings. The Annuity Expert offers online applications with live agent support.
Should I get term or whole life insurance?
Term is better for temporary needs; whole life is for permanent coverage. The Annuity Expert can help determine which fits your situation.
How much is a 20-year term life insurance policy?
Rates depend on your profile and coverage. The Annuity Expert can provide tailored quotes.
Can I get term life insurance with no medical exam?
Yes, some insurers offer no-exam options. The Annuity Expert can find these for you.
Can I have multiple term life insurance policies?
Yes, you can own more than one policy if you meet insurer guidelines.
Is term life insurance taxable?
Death benefits are usually tax-free to beneficiaries.
Can I get term life insurance if I have health issues?
Yes, but options and prices will depend on your medical history. The Annuity Expert can find insurers that work with higher-risk applicants.
Can I increase my term life insurance coverage later?
Some policies allow you to apply for more coverage, but it may require new underwriting.
Can I decrease my term life insurance coverage?
Yes, many insurers allow you to lower coverage to reduce premiums.
Does smoking affect term life insurance rates?
Yes, smokers pay significantly higher premiums than non-smokers.
Can I name more than one beneficiary on a term life policy?
Yes, you can name multiple beneficiaries and assign percentages of the benefit.
Can I change my term life insurance beneficiary?
Yes, you can change beneficiaries at any time by submitting a form to your insurer.
What happens if I stop paying my term life insurance premiums?
The policy will lapse, and your coverage will end.
Can I pay term life insurance premiums annually instead of monthly?
Yes, and paying annually can sometimes lower the overall cost.
Where can I find an online term life insurance quote quickly?
Use our life insurance quoter or contact our agents.
What does a 10-year term policy mean?
Level premiums and coverage for 10 years; the death benefit pays if death occurs during that period, then coverage ends or must be renewed.