

Compare Universal Life Insurance Quotes and Rates to Find the Best Coverage for Your Budget
When shopping for permanent coverage, comparing universal life insurance quotes is the single best way to secure lifelong protection that adapts to your financial future. Before you buy, it is essential to look at how your age, health class, and desired death benefit will impact your premium costs and policy value over time. On this page, you can analyze different styles of adjustable coverage or compare universal policies side-by-side with whole life and term life to choose the absolute best policy for your family’s needs.
What Is Universal Life Insurance?
Universal life insurance (UL) is a flexible type of permanent life insurance that offers both a death benefit and a cash value component. It allows policyholders to adjust their premiums and death benefits over time, making it a popular choice for those who want control over their policy.
How Universal Life Insurance Works
Universal life insurance consists of two main components:
- Death Benefit – The payout your beneficiaries receive upon your passing.
- Cash Value – A savings component that accumulates interest and can be accessed through loans or withdrawals.
Unlike whole life insurance, UL allows policyholders to increase or decrease their premiums, provided there’s enough cash value to cover the policy costs.
Pros and Cons of Universal Life Insurance
Pros
- Flexibility – Adjust premiums and death benefits as your financial situation changes.
- Cash Value Growth – Accumulates tax-deferred cash value that can be borrowed or withdrawn.
- Potential for Higher Returns – Indexed and variable UL policies offer market-linked growth potential.
- Permanent Coverage – Can last a lifetime if properly funded.
Cons
- Complexity – Requires active management of premiums and cash value.
- Policy Costs – Fees and insurance costs can increase, reducing cash value.
- Market Risk – Indexed and variable UL policies may have fluctuating cash values.
- Lapse Risk – If not properly funded, the policy may lapse, leaving you without coverage.
Types of Universal Life Insurance We Sell
Universal life insurance comes in several forms, each catering to different needs and preferences:
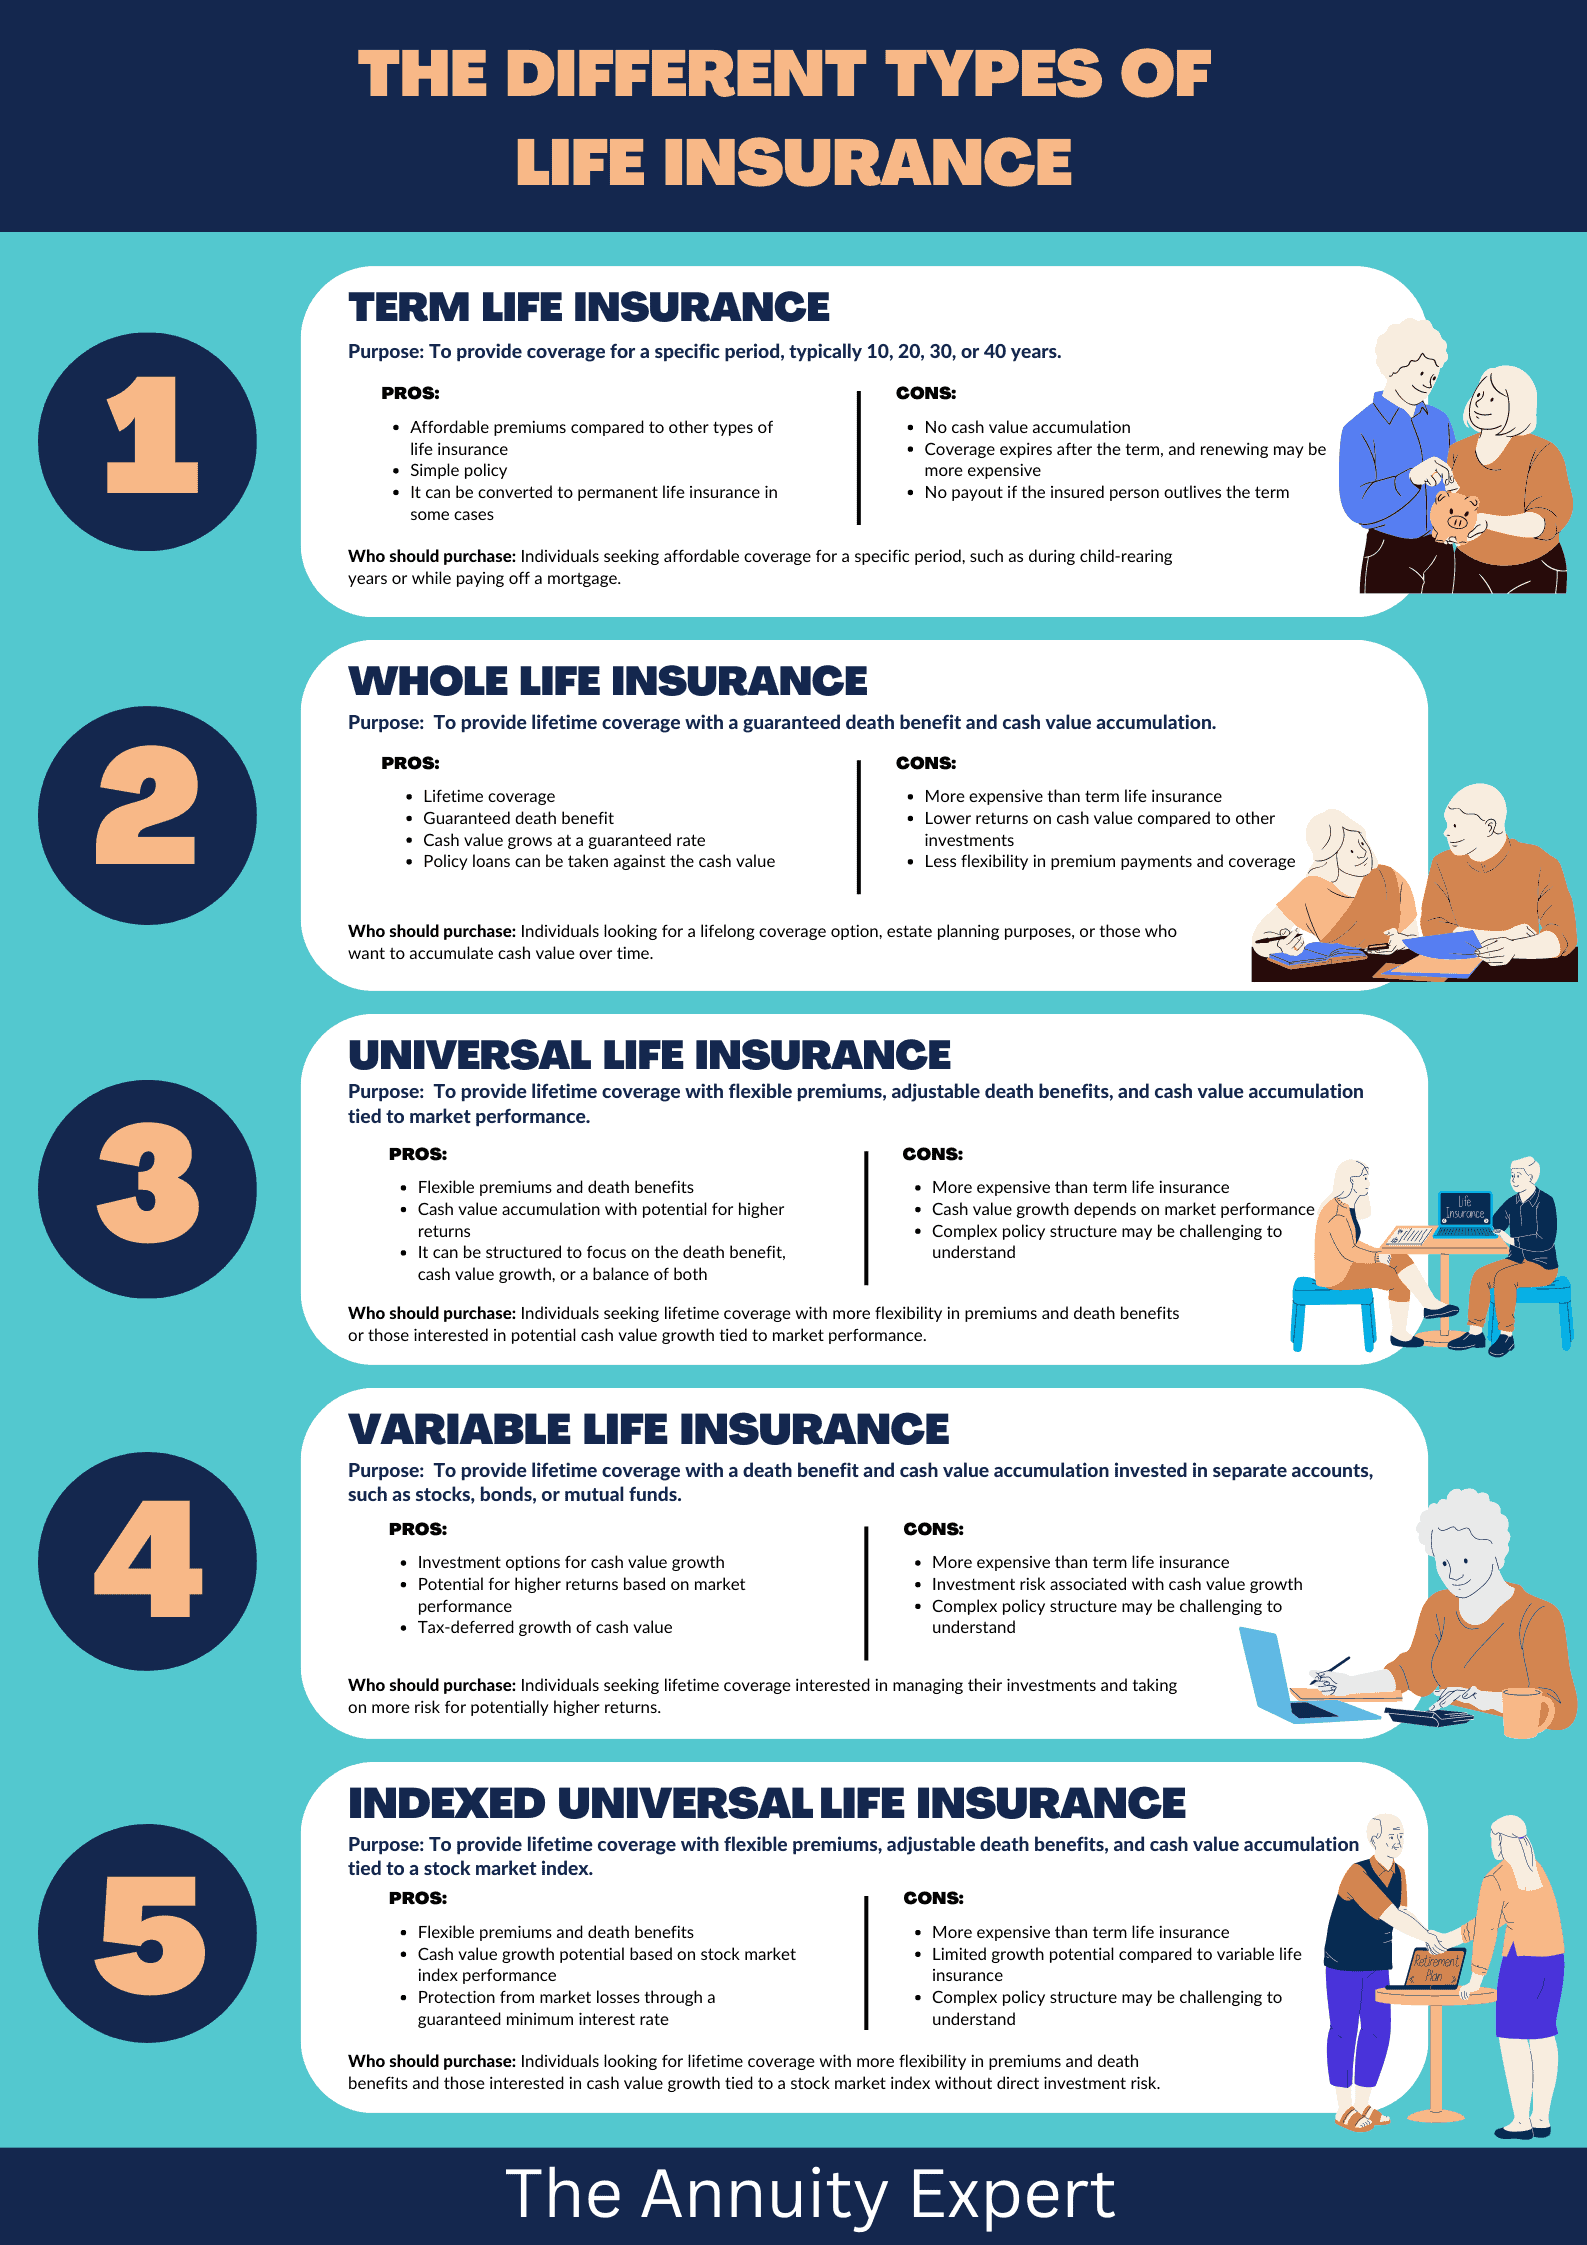
- Guaranteed Universal Life Insurance: This type focuses on providing lifelong coverage with a lower emphasis on cash value growth. It is ideal for those primarily concerned with ensuring a death benefit for their beneficiaries.
- Indexed Universal Life Insurance: The cash value in this policy is tied to market indices, such as the S&P 500, which offers the potential for higher returns compared to traditional interest-based growth. This option suits those looking for a balance between growth potential and security.
- Variable Universal Life Insurance: Offering various investment options within the policy, this type allows you to choose how your cash value is invested. While it offers higher growth potential, it also comes with increased risk, making it suitable for those with a higher risk tolerance.
Universal Life Insurance vs. Whole Life Insurance
| Feature | Universal Life | Whole Life |
|---|---|---|
| Premiums | Flexible | Fixed |
| Cash Value Growth | Varies (fixed, indexed, or variable) | Guaranteed |
| Market Exposure | Possible (IUL & VUL) | None |
| Death Benefit | Adjustable | Fixed |
| Complexity | Higher | Lower |
How We Can Help
At The Annuity Expert, we understand that choosing the right life insurance policy can be overwhelming. With 18 years of experience as an insurance agency, annuity broker, and retirement planner, we are committed to helping you find the best solution for your needs at the lowest cost. Whether you’re considering universal life insurance for its flexibility or exploring alternative options, we provide expert guidance to ensure you make an informed decision.
Who Benefits from a Universal Life (UL) Policy?
A UL policy is ideal for individuals who:
✔️ Want the flexibility to adjust premiums and death benefits over time.
✔️ Seek long-term financial protection with potential for cash value growth.
✔️ Are comfortable with managing policy details to ensure proper funding.
✔️ Need a tax-advantaged way to transfer wealth or supplement retirement income.
It can be a powerful tool, but you must be aware of how universal life illustrations can fail policyholders if real-world interest rates fall below the projected assumptions.
Who Might Be Better Off with Another Option? (And What to Consider Instead)
A UL policy may not be the best fit for those who:
❌ Prefer fixed, predictable premiums and guaranteed cash value growth.
Solution: Whole life insurance offers fixed premiums and guaranteed cash value accumulation, making it a great option for those who want stability and long-term financial security.
❌ Want a simpler, low-maintenance insurance solution.
Solution: Term life insurance is a straightforward, affordable option that provides coverage for a set period without the complexities of managing cash value.
❌ Are looking for the most affordable coverage.
Solution: Term life insurance is generally cheaper than UL, making it ideal for families or individuals who need high coverage at a low cost.
❌ Do not want to monitor their policy’s cash value or risk policy lapse due to underfunding.
Solution: Guaranteed Universal Life (GUL) insurance provides permanent coverage with little to no cash value, offering lower premiums and no risk of lapsing as long as payments are made.
Why Work with The Annuity Expert?
Personalized Recommendations – We analyze your financial goals to match you with the right coverage.
Lowest Cost Options – As an independent broker, we compare policies from multiple providers to find the most affordable rates.
Expert Retirement Planning – If you’re considering cash value life insurance for retirement, we help you optimize its benefits.
Estate Planning Support – If you need a tax-efficient way to pass on wealth, we can guide you through trust strategies.
Find the Best Policy for You
Universal life insurance can be a powerful tool—but only if it fits your needs. Book a free consultation to compare options with a universal life insurance broker and make sure you get the right coverage at the best price. Book a free consultation today and explore your options with confidence!

Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
Who offers the best universal life insurance?
John Hancock, Nationwide, and Prudential offer the best UL insurance because of their higher maximum coverage levels, low premiums, and A+ (Superior) rating from A.M. Best.
Is universal life insurance a sound investment strategy?
Universal life insurance can be a good investment strategy for individuals looking to grow their cash value over time and access those funds when needed.
Which riders will pay a death benefit?
Riders that will pay a death benefit include the accelerated death benefit rider, the child rider, and the spousal rider. These riders are designed to provide financial protection for the policyholder’s beneficiaries in the event of the policyholder’s death.
Can a universal life insurance policy be sold?
Yes, a universal policy can be sold. The policies are typically sold through financial advisors or life insurance agents.
Can a universal life policy be paid up?
Yes, a UL policy can be paid up. This means that the policyholder can make one final lump sum payment to cover their ongoing premiums fully and ensure that the policy remains in force for its full term.
What happens if I miss a payment?
If you miss a payment on your policy, there may be several consequences, depending on your policy’s specific terms and conditions. For example, some policies may allow you to make a one-time “grace period” payment to reinstate your coverage after missing a payment. However, this will typically come with additional costs or fees.
Is universal life insurance cheaper than whole life?
There is no one-size-fits-all answer to this question, as the cost of life insurance depends on many factors, including the death benefit amount, the policy term, and the age and health of the insured individual. However, universal life insurance tends to be more flexible and less expensive than whole life insurance.
What happens to the cash value in a universal life policy at death?
The cash value and the investment gains stay with the insurance company, and the beneficiaries inherit the death benefit tax-free.
What happens when a universal life policy matures?
When a policy matures, the policyholder will typically have the option to continue their coverage or cancel it. However, if the policy continues, the premiums will generally increase yearly as the insured individual ages.
Can you cash out a universal life insurance policy?
It is possible to cash out a universal life insurance policy, but this will typically come with several fees and surrender charges.