

Our Allianz 222 Plus Annuity Review
Short Answer: We would not use the Allianz 222 Plus for future lifetime income. The lifetime income is performance-based, you generally have to wait until year 11 to use the Protected Income Value for lifetime withdrawals, and the amount of income you eventually receive depends heavily on what happens with the contract’s interest crediting over the first 10 years.
Where the Allianz 222 Plus gets more interesting is estate planning. We think there are a few niche situations where the enhanced death benefit can make sense, particularly for someone who is uninsurable, someone who wants to leave qualified retirement assets to beneficiaries, or a high-net-worth retiree taking RMDs they do not need.
Allianz 222 Plus Overview
The Allianz 222 Plus is a fixed indexed annuity issued by Allianz Life Insurance Company of North America. It combines principal protection, indexed interest potential, a Protected Income Value, future lifetime withdrawals, and an enhanced death benefit.
- Product Type: Fixed Indexed Annuity
- Insurance Company: Allianz Life Insurance Company of North America
- Surrender Period: 10 Years
- Premium Structure: Additional premium can generally be added during the first 18 months
- Free Withdrawals: Up to 10% of paid premium annually under the contract provisions
- Protected Income Value: Used for lifetime income and an enhanced death benefit
- Income Waiting Period: At least 10 contract years before PIV lifetime withdrawals
- Income Rider Fee: No separate fee for the PIV or Income Multiplier Benefit riders
For more information about the carrier itself, see our Allianz annuity review.
Our Professional Opinion
Our opinion on the Allianz 222 Plus is that you should not, under any circumstances, use this annuity when your primary goal is predictable lifetime income in the future.
The biggest problem is simple. You generally cannot begin using the Protected Income Value for lifetime withdrawals until after 10 contract years. In practical terms, you are waiting until year 11 to start the income. During those first 10 years, the amount of future income you are building depends heavily on the performance of the Allianz 222 Plus.
The Protected Income Value grows when the contract earns interest, and Allianz applies an additional interest bonus to that value. If the contract does not earn much interest, your future income value does not grow the way you hoped it would.
That is where we have a major problem with this product. Allianz controls renewal cap rates, participation rates, spreads, and other crediting terms within the guarantees of the contract. In our experience, Allianz has frequently reduced renewal rates on in-force contracts. That means you are allowing future decisions by the insurance company to influence how much retirement income you may ultimately receive.
Allianz also heavily favors complex proprietary and engineered indexes. We would rather work with straightforward, traditional indexes when possible. A complicated index with an impressive backtest does not guarantee that the annuity will actually produce strong interest credits after you purchase it.
The big picture is that you are taking control out of your future lifetime income planning. You can receive an illustration showing attractive future income, but the actual outcome years later can be substantially lower if interest credits disappoint.
We have reviewed too many situations where owners expected substantially better results from this type of design and instead experienced very low credited returns. When the income value depends on performance, low returns can dramatically reduce the lifetime income you thought you were building.
And do not let the fact that the income rider has no separate fee convince you that it is automatically a better deal. In our opinion, the no-fee feature is actually a con when it comes at the expense of contractually guaranteed income growth.
We would rather pay a reasonable rider fee and know exactly how the income benefit is contractually guaranteed to grow than save the fee and gamble on what the retirement income might look like 10 years from now.
Where we do like the Allianz 222 Plus is for three very specific estate-planning scenarios. Its enhanced death benefit can make it useful for someone who cannot qualify for traditional life insurance, someone who wants to leave qualified retirement money to beneficiaries, or a high-net-worth retiree who is taking RMDs they do not need.
What We Like
- Enhanced Death Benefit: This is the primary reason we would consider the Allianz 222 Plus.
- Protected Income Value Bonus: The current product provides a substantial bonus to the PIV, which can increase the value used for the enhanced death benefit.
- Interest Bonus: Interest credited to the contract receives an additional enhancement when applied to the PIV.
- Life Insurance Alternative: It can be useful for someone who is medically uninsurable and wants to leave additional money to beneficiaries.
- Qualified Account Legacy Planning: It can be useful when the primary objective is leaving retirement assets to beneficiaries.
- RMD Planning: Applicable required minimum distributions can generally be taken penalty-free under the contract provisions.
- Strong Insurance Company: Allianz easily clears our A- or better financial-strength preference.
- 10% Free Withdrawal Feature: Provides annual access to a portion of the contract during the surrender period.
- Principal Protection: Direct market declines do not reduce the contract because the annuity is not directly invested in the indexes.
What We Don’t Like
- Performance-Based Lifetime Income: This is the biggest reason we would not use the Allianz 222 Plus for retirement income planning.
- Income Does Not Begin Until After 10 Contract Years: You are effectively waiting until year 11 to use the PIV for lifetime withdrawals.
- No Contractually Guaranteed Income Roll-Up: Future PIV growth depends on credited interest rather than a guaranteed annual growth formula.
- Renewal Rate Risk: Cap rates, participation rates, spreads, and other crediting terms can change subject to contractual guarantees.
- Complex Engineered Indexes: We prefer straightforward traditional index strategies instead of depending heavily on proprietary indexes and backtested performance.
- No-Fee Rider Can Be Misleading: We do not consider a free income rider a benefit if it provides less certainty about future income.
- PIV Is Not Cash: The bonus and enhanced PIV cannot simply be withdrawn as a lump sum.
- Enhanced Death Benefit Requires Payments Over Time: Beneficiaries generally must receive the PIV death benefit over at least five years rather than as an immediate lump sum.
- Long Surrender Period: You are committing to a 10-year surrender schedule.
- Withdrawals Reduce the PIV: RMDs and other withdrawals reduce the Protected Income Value proportionally.
Where We Actually Like the Allianz 222 Plus
A Life Insurance Alternative for Someone Who Is Uninsurable
This is one of the better uses for the Allianz 222 Plus.
If you have a serious medical condition or illness that prevents you from qualifying for traditional life insurance, this annuity can provide another way to leave additional money to your beneficiaries without traditional medical underwriting.
The current version provides a substantial bonus to the Protected Income Value when the contract is issued. At the time of this review, that bonus is 45%.
For example, a $200,000 premium with a 45% PIV bonus would create an initial Protected Income Value of $290,000 before future interest bonuses are applied.
That does not mean you suddenly have $290,000 of cash. The bonus is applied to the PIV, not the accumulation value.
The PIV can ultimately be used as an enhanced death benefit. Beneficiaries can generally elect the enhanced PIV death benefit through payments over a period of at least five years, subject to the contract provisions.
For someone who cannot qualify for life insurance and has money available to reposition, this can be a good estate-planning strategy.
Leaving Qualified Retirement Accounts to Beneficiaries
The second situation we like is someone whose main goal is leaving qualified retirement money to children or other beneficiaries.
This could include money coming from a traditional IRA, 401(k), 403(b), or another qualified retirement account.
Instead of simply leaving the retirement account as-is, eligible assets can be transferred into the Allianz 222 Plus, where the PIV receives the premium bonus and can potentially receive additional interest bonuses over time.
The goal is not to eliminate income taxes for the beneficiaries. Pretax retirement money generally remains taxable when inherited and distributed. The objective is to potentially create a larger gross inheritance that can help offset some of that tax burden.
If your primary objective is transferring wealth rather than maximizing retirement income for yourself, this is one of the situations where the Allianz 222 Plus becomes more interesting.
High-Net-Worth Retirees Taking RMDs They Don’t Need
The third scenario is a high-net-worth retiree who has to take required minimum distributions but does not actually need the money for living expenses.
The Allianz 222 Plus allows applicable RMDs from a qualified contract to qualify as penalty-free withdrawals. However, the accumulation value is reduced by the amount distributed, and the PIV is reduced proportionally.
That means you should not assume the full enhanced death benefit will remain untouched. The strategy needs to be illustrated using your actual age, premium, anticipated RMDs, and beneficiary goals.
But for a retiree whose priority is transferring wealth rather than spending down retirement assets, this can still be worth evaluating.
If you are taking RMDs you do not need, there are other things you can do with those after-tax dollars. You could use them to buy additional life insurance, purchase long-term care insurance, or consider a hybrid life and long-term care policy.
Our preference is to protect you while you are alive and protect your beneficiaries when you die. There is no reason to focus only on leaving an inheritance while ignoring the possibility that a long-term care event could consume a substantial portion of your estate.
How the Protected Income Value Works
The Allianz 222 Plus has two separate values that buyers need to understand: the accumulation value and the Protected Income Value.
The accumulation value is essentially the actual contract value. It consists of premium plus credited interest, minus withdrawals and applicable adjustments or charges.
The Protected Income Value is different. It is used to calculate lifetime income withdrawals and the enhanced death benefit. It receives the premium bonus and an additional enhancement on interest credited to the contract.
This distinction is critical because the PIV is not money you can simply surrender and take with you.
If you fully surrender the contract, the cash surrender value does not include the PIV premium bonus, interest bonus, or interest earned on those bonuses.
How the Lifetime Income Works
The Allianz 222 Plus provides lifetime withdrawals from the PIV, but you must generally hold the contract for at least 10 contract years and meet the applicable age requirements before those withdrawals can begin.
The starting annual withdrawal amount is calculated as a percentage of the PIV based on your age when income begins.
Once lifetime withdrawals begin, the payment can increase after years in which the contract earns interest.
That increasing-income potential sounds good, but it is exactly why we do not want to use the Allianz 222 Plus as the foundation of a future retirement income plan. Your starting PIV and future increases depend on performance instead of a contractually guaranteed annual income roll-up.
Compare Allianz 222 Plus Income Payouts
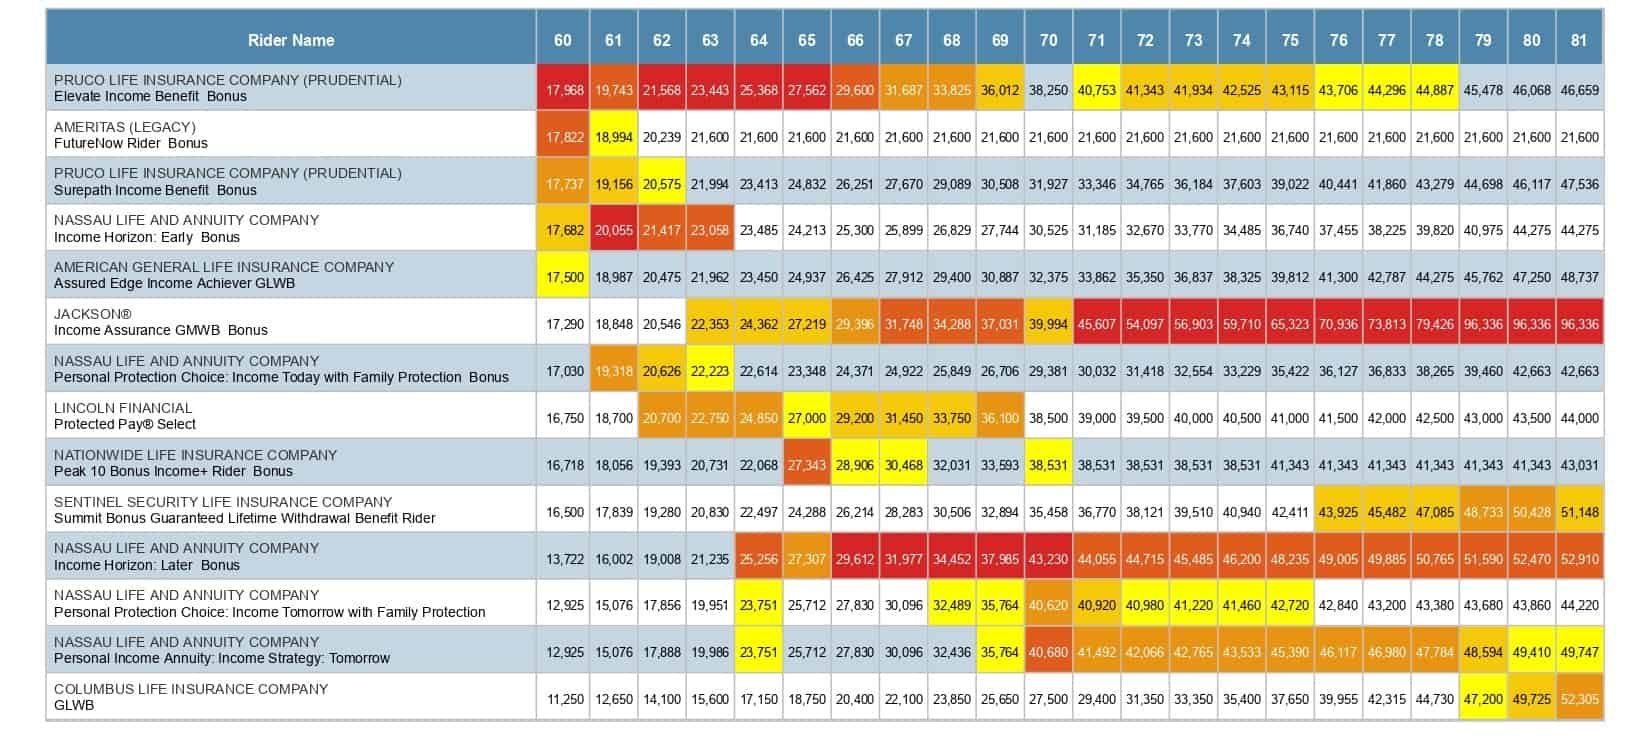
If your primary objective is lifetime income, we would compare the Allianz 222 Plus against annuities that provide contractually guaranteed income growth.
The best guaranteed income product depends on your age, state, premium amount, whether the income covers one or two lives, and exactly when you want the income to begin.
Contact us, and we will create a custom annuity income heat map based on your age, state, premium amount, and when you want income to start. That lets us compare actual guaranteed income available from A- or better-rated insurance companies instead of relying on hypothetical index performance.
The Allianz Income Multiplier Benefit
The Allianz 222 Plus includes the Allianz Income Multiplier Benefit, which can increase the annual maximum lifetime withdrawal when certain health-related requirements are met.
The benefit can generally provide up to twice the annual maximum when qualifying confinement or activities-of-daily-living requirements are satisfied.
However, the benefit terminates when the applicable rider terminates, the accumulation value reaches zero, or the insured fully recovers under the applicable provisions.
This is not a replacement for dedicated long-term care coverage. It is an annuity rider with specific contractual qualification requirements.
Liquidity Features
- Annual Free Withdrawals: Up to 10% of paid premium can generally be withdrawn annually under the contract provisions.
- Required Minimum Distributions: Applicable RMDs from qualified contracts can qualify as penalty-free withdrawals.
- Health-Related Access: Certain contract benefits may provide additional access under qualifying health circumstances.
- No Return of Premium: There is no contractual return-of-premium feature that automatically gives you your original premium back if you leave early.
Surrender Charges and Market Value Adjustment
The Allianz 222 Plus is a long-term contract with a 10-year surrender period.
Withdrawals exceeding the contract’s penalty-free amount can be subject to surrender charges and a Market Value Adjustment.
If there is a reasonable chance you will need substantial access to this money during the next several years, the Allianz 222 Plus may be the wrong product regardless of the bonus.
A Better Alternative to the Allianz 222 Plus
If you are considering the Allianz 222 Plus primarily because of its enhanced death benefit or legacy-planning features, we would compare it directly with the Athene Agility 10.
In our opinion, the Athene Agility 10 is the superior product for these particular enhanced-death-benefit strategies.
Both products use enhanced benefit values that are different from the actual cash account value, but their bonuses, interest-crediting mechanics, withdrawal rules, and beneficiary payout structures differ.
We would compare both contracts using the same premium, age, anticipated withdrawals, RMD assumptions, and beneficiary goals before choosing either one.
If your goal is future lifetime income, we would use a completely different type of annuity. We prefer a fixed indexed annuity with a contractually guaranteed income roll-up so you know how the income benefit grows regardless of what the index strategies actually earn.
Who Should Consider the Allianz 222 Plus?
- Someone Who Is Medically Uninsurable: You want an enhanced death benefit but cannot qualify for traditional life insurance.
- Someone Leaving Qualified Retirement Assets: Your main objective is increasing the potential inheritance left to beneficiaries.
- A High-Net-Worth Retiree Taking RMDs They Don’t Need: You want to satisfy required withdrawals while maintaining an enhanced death benefit.
- Someone Comfortable With a 10-Year Commitment: You do not expect to need substantial access to the account during the surrender period.
Who Should Probably Buy Something Else?
If your primary goal is predictable future lifetime income, we would buy something else. We want contractually guaranteed income growth, not a retirement plan that depends on future index credits and renewal rates.
If your primary goal is accumulation, we would also compare accumulation-focused FIAs instead. The Allianz 222 Plus is built around its PIV and benefit structure rather than being our favorite pure accumulation product.
If you simply want a guaranteed interest rate and do not need indexed growth or an enhanced PIV, compare current fixed annuity rates instead.
What We Recommend
If your goal is predictable lifetime income 10 or more years from now, we would skip the Allianz 222 Plus.
There are better annuities that provide contractually guaranteed income growth without forcing you to depend on future index performance and renewal rates.
If your objective is estate planning, the conversation changes. The Allianz 222 Plus can be useful as a life insurance alternative for someone who is uninsurable, as a strategy for leaving qualified retirement assets to beneficiaries, or as a specialized tool for high-net-worth retirees taking RMDs they do not need.
Even in those situations, we would compare the Allianz 222 Plus against Athene Agility 10 before making a decision.
The mistake is buying this annuity because the bonus looks impressive or because the income rider has no fee. Buy an annuity because it does the specific job you need it to do better than the available alternatives.

Compare the Allianz 222 Plus Before You Buy
We can compare the Allianz 222 Plus against annuities offering contractually guaranteed lifetime income, enhanced death benefits, accumulation features, and other estate-planning strategies.
Contact The Annuity Expert for free quotes and a no-obligation side-by-side comparison before deciding which product makes the most sense for your situation.
If you already own an Allianz 222 and want to know whether it still fits your retirement plan, request a free annuity second opinion.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Related Reviews
- Pacific Life Pacific Income Provider
- Fidelity and Guaranty Safe Income Advantage Annuity
- Integrity Life Income Source Annuity
- Symetra Freedom Income Annuity
- Lincoln Financial Insured Income Annuity
- Allianz Benefit Control Annuity
- Nationwide Income Promise Select Annuity
- EquiTrust Market Power Bonus Index Annuity
- Oceanview Fixed Indexed Annuity
- Allianz Core Income 7 Annuity