

Our Professional Opinion on the NexAnnuity NexHaven MYGA
We do not recommend the NexHaven MYGA. The contract is issued by The Ohio State Life Insurance Company, which is currently rated B+ by AM Best. That is below our normal A- minimum and below the limited B++ level we may occasionally consider for a short-term MYGA with a substantially higher rate.
NexHaven offers 3-, 5-, 7-, and 10-year guarantee periods. Even the 3-year version does not overcome the company-rating issue for us. If we are using a fixed annuity for the safe portion of a retirement plan, there is no reason to step down to B+ when A- or better-rated MYGAs are widely available.
The product also requires optional riders to provide features many competing MYGAs include automatically. Without the death-benefit rider, the beneficiary amount can be based on cash surrender value rather than the full account value. Normal percentage-based liquidity also requires the free-withdrawal rider.
The Market Value Adjustment can affect withdrawals, surrender values, and potentially the death benefit when the applicable rider is not selected. The contract also has a relatively high minimum premium and automatically renews into another guarantee period if the owner does not act at maturity.
We do like the daily compounding, broad term selection, nursing-home waiver, and ability to customize the contract with optional features. Those positives do not outweigh the weaker insurer rating and the need to add riders for basic liquidity and death-benefit protection.
Bottom line: NexHaven is not a product we would use for new retirement money. We would choose an A- or better-rated MYGA with comparable or better rates and stronger built-in contract provisions.
Compare NexHaven with the current fixed annuity rates from A- or better-rated insurers before purchasing.
What We Like
- 3-, 5-, 7-, and 10-Year Terms: The product offers a broad range of guarantee periods.
- Daily Compounding: Interest is credited daily and compounded at the end of each policy year.
- Optional Liquidity Rider: Buyers can add percentage-based free withdrawals when access is important.
- Optional Full Account-Value Death Benefit: The death-benefit rider can waive normal withdrawal charges and MVA at death.
- Nursing-Home Waiver: Qualifying confinement can provide additional access after the first contract year.
What We Don’t Like
- B+ AM Best Rating: Ohio State Life falls below our minimum and below the limited B++ exception we may consider.
- High Minimum Premium: The contract requires a substantially larger deposit than many competing MYGAs.
- Base Death Benefit Can Be Cash Surrender Value: The full account-value death benefit requires the applicable rider.
- Normal Liquidity Requires a Rider: Percentage-based penalty-free withdrawals are not automatically included in the base design.
- Market Value Adjustment: The MVA can affect withdrawals, surrender value, and certain death-benefit calculations.
- Automatic Renewal: The contract can restart another guarantee period and surrender schedule if the owner does nothing at maturity.
Nex MYGA Overview
Product Details
The Nex Multi-Year Guaranteed Annuity (MYGA) offered by The Ohio State Life Insurance Company is a fixed annuity product designed to provide retirees with a stable and guaranteed income stream. This product comes with multiple guarantee periods, including 3-, 5-, 7-, and 10-year options. It aims to grow retirement income while offering principal protection and tax-deferred growth.
Features
- Income & Growth: The Nex MYGA offers higher interest rates compared to typical financial products. Its tax-deferred growth allows for faster compounding, making it a beneficial option for growing retirement savings.
- Access & Liquidity: The product offers flexible withdrawal terms and optional riders, providing access to funds under specific conditions.
- Principal Protection: Guarantees the protection of both the principal and the interest earned.
- Succession Planning: Facilitates asset transfer to beneficiaries, potentially avoiding probate.
- Interest Rate Guarantees: Ensures a guaranteed interest rate over the selected guarantee period.
- Annuitization Options: Provides various payout options, including lifetime, fixed period, and joint life income.
- Withdrawal Charge Schedule: Charges vary depending on the selected guarantee period, with detailed percentages outlined for each contract year.
Product Type
- Annuity Type: Fixed Multi-Year Guaranteed Annuity (MYGA)
- Issuer: The Ohio State Life Insurance Company (a NexAnnuity affiliate)
- Primary Use: Safe accumulation, CD replacement, IRA rollover
- Income Option: Annuitization only (no GLWB available)
Retirement Accounts Accepted
- Non-Qualified
- IRA
- 401(K)
- IRA Rollover
- Inherited IRA
- TSP
Pros and Cons
| Pros | Cons |
|---|---|
| Rate guaranteed for 3–10 years | No GLWB income rider available |
| Optional death benefit pays full value with no penalties | MVA applies if you withdraw early without a rider |
| Nursing home waiver improves access during crisis | Auto-renewals reset surrender charge period |
| Strong liquidity options if riders are selected | Limited flexibility once term ends unless proactive |
| Tax-deferred growth | IRS 10% penalty if withdrawn before 59½ (qualified funds) |

What Happens After The Term Ends?
When the term expires, you have 30 days to:
- Withdraw the full account value without fees.
- Transfer the balance via a 1035 exchange.
- Annuitize the balance using one of several payout options.
- Do nothing, in which case the annuity automatically renews into the same term with a new rate and a fresh surrender charge period.
Important: If you don’t take action during this window, you lose flexibility and may be locked into a less favorable interest rate. Renewal terms may come with lower rates and new surrender charges, so reviewing your options with a broker before maturity is essential.
Why Comparing Annuity Products Matters
Even among MYGAs, differences in rate, renewal practices, waivers, and post-term flexibility can dramatically impact performance and accessibility. Comparing the Nex MYGA with other products helps you:
- Find the highest guaranteed rate
- Access income riders when needed
- Avoid annuities that auto-renew without client notice
- Secure the right balance between liquidity and accumulation
Let a broker help you compare apples to apples across A-rated carriers so you can make the most cost-effective and performance-driven decision.
Who Should Consider The Nex MYGA?
Best for:
- Savers who want guaranteed fixed growth
- IRA owners needing tax-deferred accumulation
- Individuals replacing CDs or maturing bond ladders
- People who don’t need income during the term
- Clients looking to pass money efficiently to beneficiaries
Not ideal for:
- Anyone who may forget to act during the renewal window
- Retirees seeking lifetime income (no GLWB available)
- Investors who want growth linked to inflation or markets
- People needing more than 10% liquidity or frequent access
Final Verdict
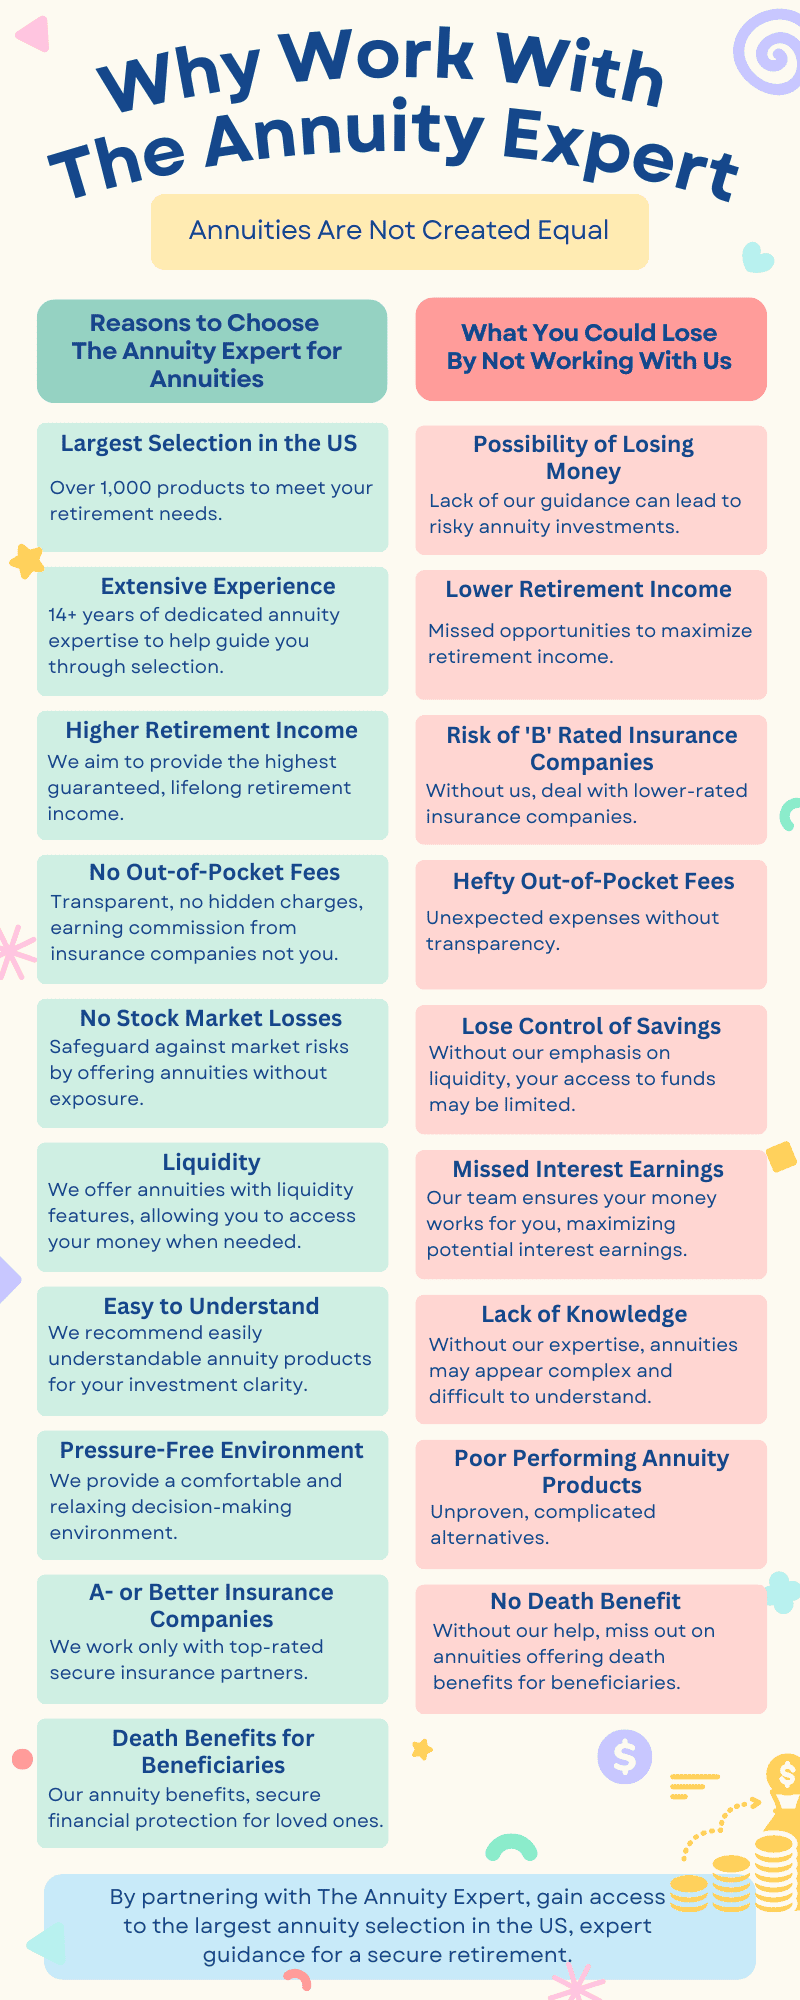
We recommend skipping NexHaven and using an A- or better-rated MYGA with stronger built-in liquidity and death-benefit provisions. Contact The Annuity Expert for free quotes and a no-obligation comparison of current fixed annuities.
Talk to The Annuity Expert Before You Buy
Get a custom quote and see how the Nex MYGA compares to other leading options. Whether you’re looking for the best rates, better liquidity, or guaranteed income, we’ll guide you to the product that fits your goals. Contact us now for a free annuity consultation.
Free Personalized Annuity Help
Get help or a quote from a licensed financial professional. This service is free of charge.
Related Reviews
- Athene Agility Annuity
- TIAA
- Is The FERS Annuity a Good Idea
- American Equity Annuity Reviews
- Are Fidelity Annuities Any Good?
- Is the Allianz 222® Annuity Any Good?
- Transamerica Annuity Review
- Is The Accumulation Protector PlusSM Annuity Any Good?
- Is SILAC Multi-Year Guaranteed Annuity (MYGA) Any Good?
- Is Allianz Core Income 7® Annuity with Core Income Benefit Rider Any Good?
- Is Thrivent Multi-Year Guarantee Annuity (MYGA) Any Good?
- Is NAC VersaChoice 10 Fixed Index Annuity Any Good?
- Is The Select™ Fixed Annuity From Northwestern Mutual Any Good?
- Are North American Life Insurance And Midland National Reliable Annuity Companies?
- Are State Farm Annuities Any Good?
- Is The American Equity Immediate Annuity Any Good?
- Is Athene Ascent Pro 10 Any Good?
- Are New York Life Annuities Any Good?
- Is The IncomeShield 10 Fixed Index Annuity Any Good?
- Is The Americo Elite 5 Index Annuity Any Good?