

Utilizing Annuities for Conservative Growth and Principal Protection
When protecting your hard-earned retirement nest egg, avoiding market volatility is paramount. Deploying annuities for conservative growth can protect your principal from stock market downturns while still providing an opportunity to earn interest. Two contract designs are commonly used for this purpose: Multi-Year Guaranteed Annuities (MYGAs) and Fixed Index Annuities (FIAs). These annuities are designed for investors who want principal protection and tax-deferred growth without directly exposing their retirement savings to stock market losses.
Multi-Year Guaranteed Annuities (MYGAs)
How it works: A MYGA operates similarly to a bank CD but offers tax-deferred growth. The insurance company guarantees a fixed interest rate for a set number of years, and that rate does not change during the guarantee period.
What makes it conservative: The interest rate is locked in, and the principal is protected from stock market losses.
- Pros:
- Guaranteed interest rate for the entire guarantee term
- Principal protection
- Predictable growth
- Tax-deferred accumulation
- May offer higher rates than bank CDs
- Cons:
- No additional upside from stock market index growth
- Surrender charges apply during the surrender period
- The interest rate is fixed, so you cannot benefit from a higher rate during the guarantee period if market interest rates rise later
Who needs it: Conservative investors seeking predictable returns and stability without stock market volatility.
Who does not need it: Investors looking for aggressive growth, unlimited upside potential, or full liquidity.
Fixed Index Annuities (FIAs)
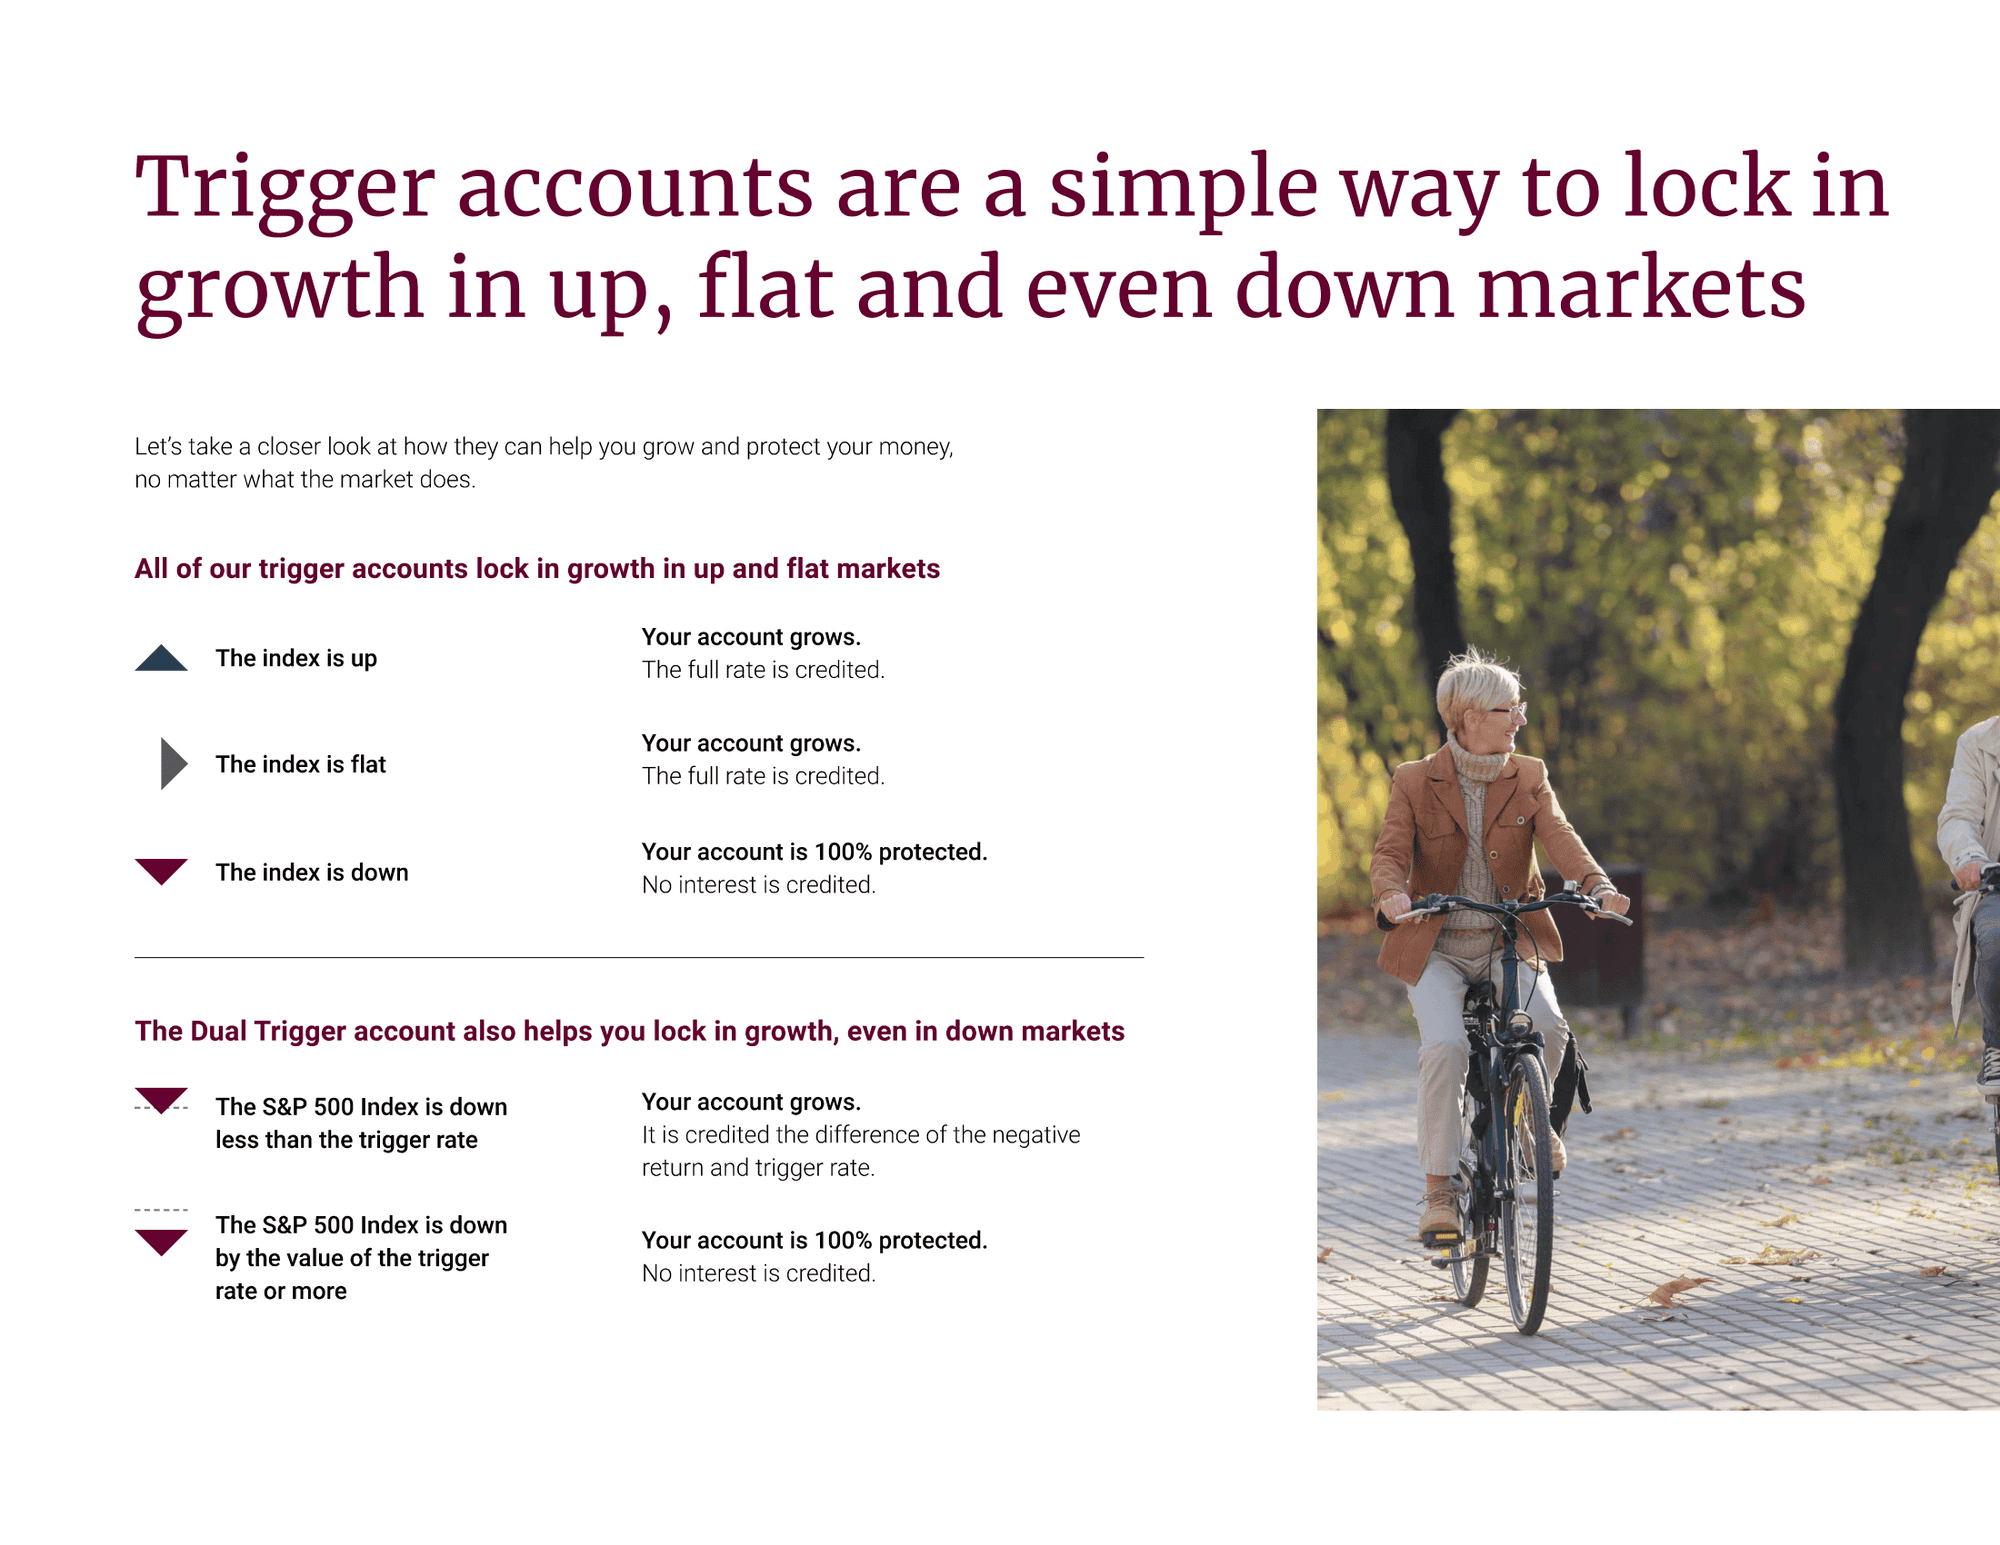
How it works: A fixed index annuity credits interest based in part on the performance of a market index, such as the S&P 500, without investing your money directly in the stock market. If the index declines, the contract does not lose value solely because of that market decline.
What makes it conservative: You can pursue market-linked interest while protecting your principal from stock market losses. The tradeoff is that the insurance company limits the amount of index growth you can receive through caps, participation rates, spreads, or other crediting rules.
- Pros:
- Principal protection from stock market losses
- Upside potential linked to market indexes
- Tax-deferred growth
- Some contracts offer optional lifetime income riders
- Multiple crediting strategies may be available
- Cons:
- Returns are limited by caps, participation rates, spreads, or other crediting rules
- More complex than a MYGA
- Many products allow the insurance company to change crediting rates each year
- Surrender charges apply during the surrender period
Who needs it: Investors seeking more growth potential than a fixed-rate annuity while still protecting their principal from stock market losses.
Who does not need it: Investors seeking unlimited stock market upside, direct ownership of stocks, or complete liquidity.
Fixed Index Annuities We Like
For conservative accumulation, we generally prefer fixed index annuities that use straightforward crediting strategies, provide access to well-known indexes such as the S&P 500, and give the insurance company less ability to reduce your upside potential after the contract is issued. A high initial cap is useful, but a competitive cap that is contractually locked can be more valuable than a higher rate that can be reduced after the first year.
Sagicor Sage Accumulator Fixed Index Annuity
The Sagicor Sage Accumulator is one of our preferred fixed index annuities for conservative accumulation because it combines principal protection with a competitive cap on the true S&P 500. Sagicor is an A-rated insurance company, and the Sage Accumulator is available in 5-, 7-, and 10-year options.
The biggest advantage is the 10% S&P 500 annual point-to-point cap. On the 5-year and 7-year products, the 10% cap is locked in for the entire term of the contract. Sagicor cannot reduce that cap from year to year during those terms.
This matters because many fixed index annuities give the insurance company the right to change caps and participation rates annually. An annuity may start with an attractive rate, but that does not necessarily tell you what the rate will be several years later. The Sage Accumulator provides more certainty because the 5- and 7-year S&P 500 caps are established upfront for the full contract term.
The 10-year version also starts with a 10% S&P 500 cap, but the initial cap is locked for the first five years rather than all ten years. A new guaranteed cap is then established for years six through ten.
- Pros:
- 10% annual point-to-point cap on the true S&P 500
- 5-year cap locked for the entire 5-year contract term
- 7-year cap locked for the entire 7-year contract term
- 10-year product locks the initial cap for the first five years
- Principal protection from stock market losses
- Simple annual point-to-point S&P 500 strategy rather than requiring an engineered index to pursue competitive upside
- Cons:
- The 10-year product does not lock the initial 10% cap for the full ten years
- A locked cap also means the cap will not increase during the lock period if market conditions later support higher caps
- Surrender charges apply during the surrender period
Who needs it: Conservative investors who want principal protection and meaningful S&P 500 growth potential but do not want to worry about the insurance company reducing their cap every year. The 5- and 7-year versions are particularly useful for investors who value knowing their S&P 500 cap upfront for the entire contract term.
Who does not need it: Investors who want unlimited stock market upside, complete liquidity, or who prefer to accept annually changing caps and participation rates in exchange for other product features.
Oceanview CapLock Fixed Index Annuity
The Oceanview CapLock stands out for investors who want multiple traditional index choices with locked crediting terms. The product offers strategies tied to familiar indexes such as the S&P 500, Nasdaq-100, and Russell 2000.
Where Oceanview differs from the Sagicor Sage Accumulator is index selection. Sagicor’s primary attraction is its locked 10% S&P 500 cap, while Oceanview gives investors access to several traditional indexes while still using its CapLock structure. Its caps and crediting rates are locked for the applicable contract term rather than resetting annually.
This can be valuable for conservative investors who want more index diversification without relying entirely on engineered or newly created indexes whose historical results may depend heavily on backtesting.
- Pros:
- Traditional index choices including the S&P 500, Nasdaq-100, and Russell 2000
- Caps and applicable crediting rates locked for the contract term
- Principal protection from stock market losses
- More traditional index variety than products focused primarily on the S&P 500
- Cons:
- Locked caps mean you cannot receive a higher cap during the lock period if rates improve later
- Surrender charges apply during the surrender period
Who needs it: Conservative investors who value stable crediting terms but also want access to several well-known market indexes rather than relying on a single index strategy.
Who does not need it: Investors who want unlimited upside, complete liquidity, or who specifically want only an S&P 500 strategy.

Lincoln Financial OptiBlend Fixed Index Annuity
The Lincoln OptiBlend is another option for investors who prefer a straightforward S&P 500-focused fixed index annuity. Its RateLock structure can provide more stability in crediting terms compared with products that reset rates annually.
Lincoln can make sense for investors who want a recognizable insurance company and a relatively simple indexed strategy but should still compare the available cap, contract term, deposit requirements, and RateLock provisions against products such as Sagicor and Oceanview.
- Pros:
- Simple structure focused on the S&P 500
- RateLock design can reduce annual changes to crediting terms
- Principal protection with market-linked growth potential
- Cons:
- Less traditional index variety than Oceanview
- Current cap rates and available bands should be compared with competing locked-cap products before purchasing
- Subject to surrender charges during the surrender period
Who needs it: Investors who prefer a relatively simple S&P 500-focused fixed index annuity and want more stability in the crediting structure than a typical annually resetting FIA.
Who does not need it: Investors whose main priority is obtaining the highest available locked S&P 500 cap or having several traditional index choices.
Accounts Suitable for Funding These Annuities
- Traditional IRA
- Roth IRA
- 401(k) rollovers
- 403(b) rollovers
- 457 plan rollovers
- Non-qualified brokerage or savings money
Using tax-deferred accounts such as IRAs can preserve the tax-deferred status of retirement savings while adding the contractual guarantees of an annuity. An annuity inside an IRA does not provide additional tax deferral beyond what the IRA already provides, so the reason for using one should generally be its guarantees, principal protection, income features, or crediting strategy.
Income Options
Both MYGAs and fixed index annuities can provide guaranteed lifetime income, but the way that income is created can differ significantly.
All annuities can offer lifetime income through annuitization, which is generally irreversible once elected. Many fixed index annuities also offer guaranteed lifetime withdrawal benefit riders (GLWBs) for lifetime income while allowing the contract owner to maintain more control over the remaining account value.
If your primary goal is accumulation rather than retirement income, do not automatically choose an annuity simply because it offers an income rider. Annuities tend to work best when the product is selected around the specific job you need it to perform.
Additional Insurance for Conservative Investors
- Long-term care insurance: Helps protect retirement assets from potentially significant long-term care expenses.
- Life insurance: Can provide a separate death benefit and help transfer money to beneficiaries.
- Disability insurance: Helps protect earned income during working years if an illness or injury prevents you from working.
Bottom Line
MYGAs: Best suited for conservative investors who want a known interest rate and predictable growth for a specific period.
Fixed Index Annuities: Better suited for conservative investors who want principal protection but are willing to accept less predictable returns in exchange for greater market-linked growth potential.
For investors comparing fixed index annuities for accumulation, pay close attention to more than the first-year rate. Look at whether the cap is guaranteed, how long it is guaranteed, which index is being used, whether the index has a meaningful live history, liquidity provisions, surrender charges, and what the insurance company is allowed to change after the contract is issued.
The Sagicor Sage Accumulator deserves consideration because its 5- and 7-year versions currently combine a 10% annual point-to-point cap on the true S&P 500 with a cap that is locked for the full contract term. Oceanview provides another strong locked-rate alternative for investors who want several traditional index choices, while Lincoln OptiBlend can appeal to investors who prefer a simpler S&P 500-focused RateLock structure.
Contact The Annuity Expert for free quotes and a side-by-side comparison of the best annuity options available for your goals. We can compare rates, cap guarantees, liquidity, surrender periods, insurance company ratings, and contract features so you can see which option fits your retirement plan. There is no obligation.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.