

Income Strategies, Risks, and Ways to Stretch Your Savings
Scenario:
Retiring with $500,000 saved is a milestone, but it doesn’t guarantee lifelong financial security. The real question is how to turn that lump sum into sustainable income. The answer depends on how you invest, whether you use insurance products like annuities, your Social Security benefits, and how much you plan to spend.
Stop the Drawdown Clock: Instead of worrying about how long your $500,000 will last, you can turn it into a guaranteed ‘personal pension’ that never runs out. Check out our dedicated guide to see exactly how much $500k annuity income you can generate per month.
How $500,000 Can Be Used in Retirement
Safe Withdrawal Rule (4% Rule)
$20,000/year for 30 years
Withdraw 4% of your portfolio annually to avoid running out of money. It’s based on historical market returns and inflation.
✔ Simple and widely known
✔ Can last ~30 years
✘ Doesn’t guarantee income
✘ Doesn’t protect against market crashes
Who Needs It: DIY retirees who want to manage their own investments
Who Doesn’t: Those afraid of outliving their money or managing portfolio risk
2. Relying on Investments Alone
- How it works: Keep the $500k in a mix of stocks, bonds, CDs, or REITs and live off dividends/interest.
- Pros: Liquidity, growth potential, estate value for heirs.
- Cons: Volatility, no guarantees, possible downturn losses.
- Who needs it: High-net-worth retirees with other assets.
- Who doesn’t: Retirees with no backup plan if markets crash.
3. Buying an Annuity
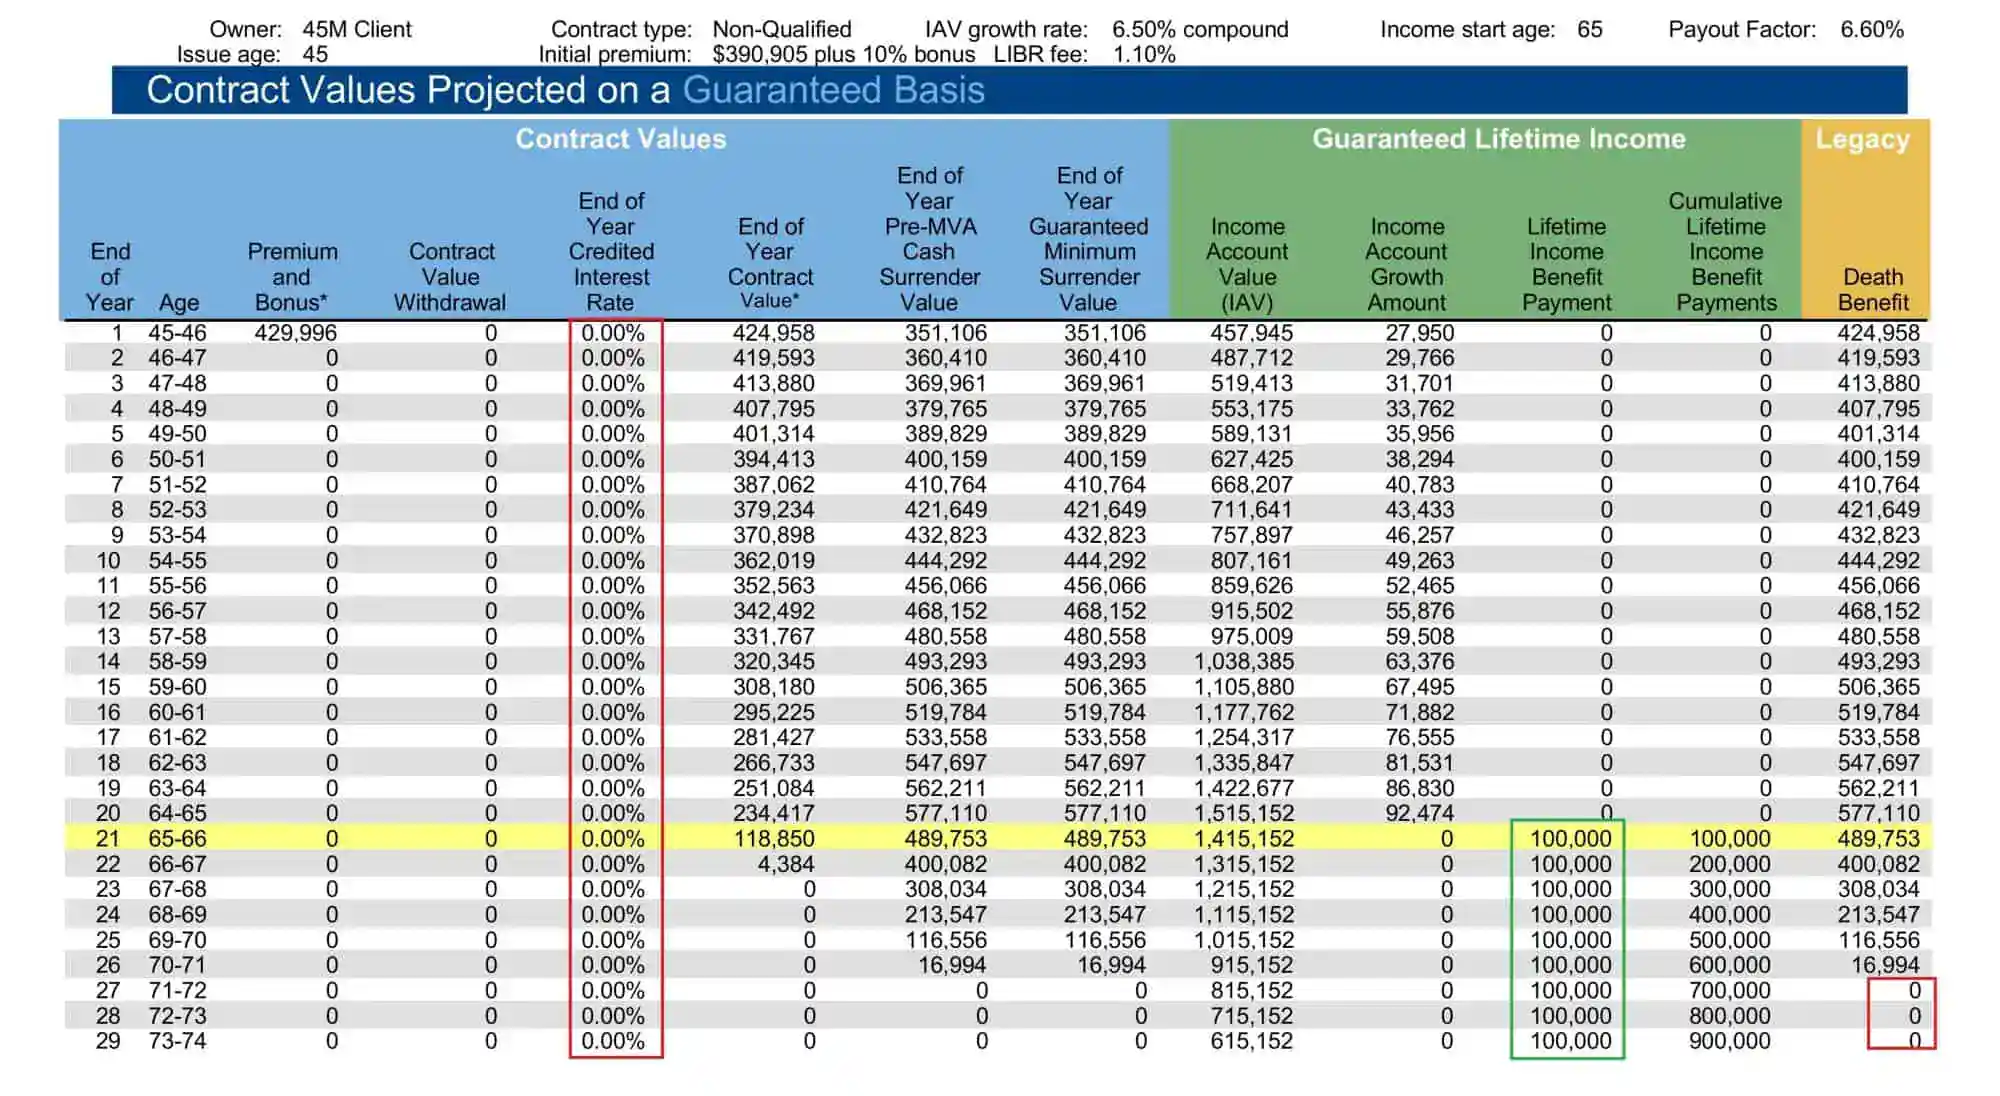
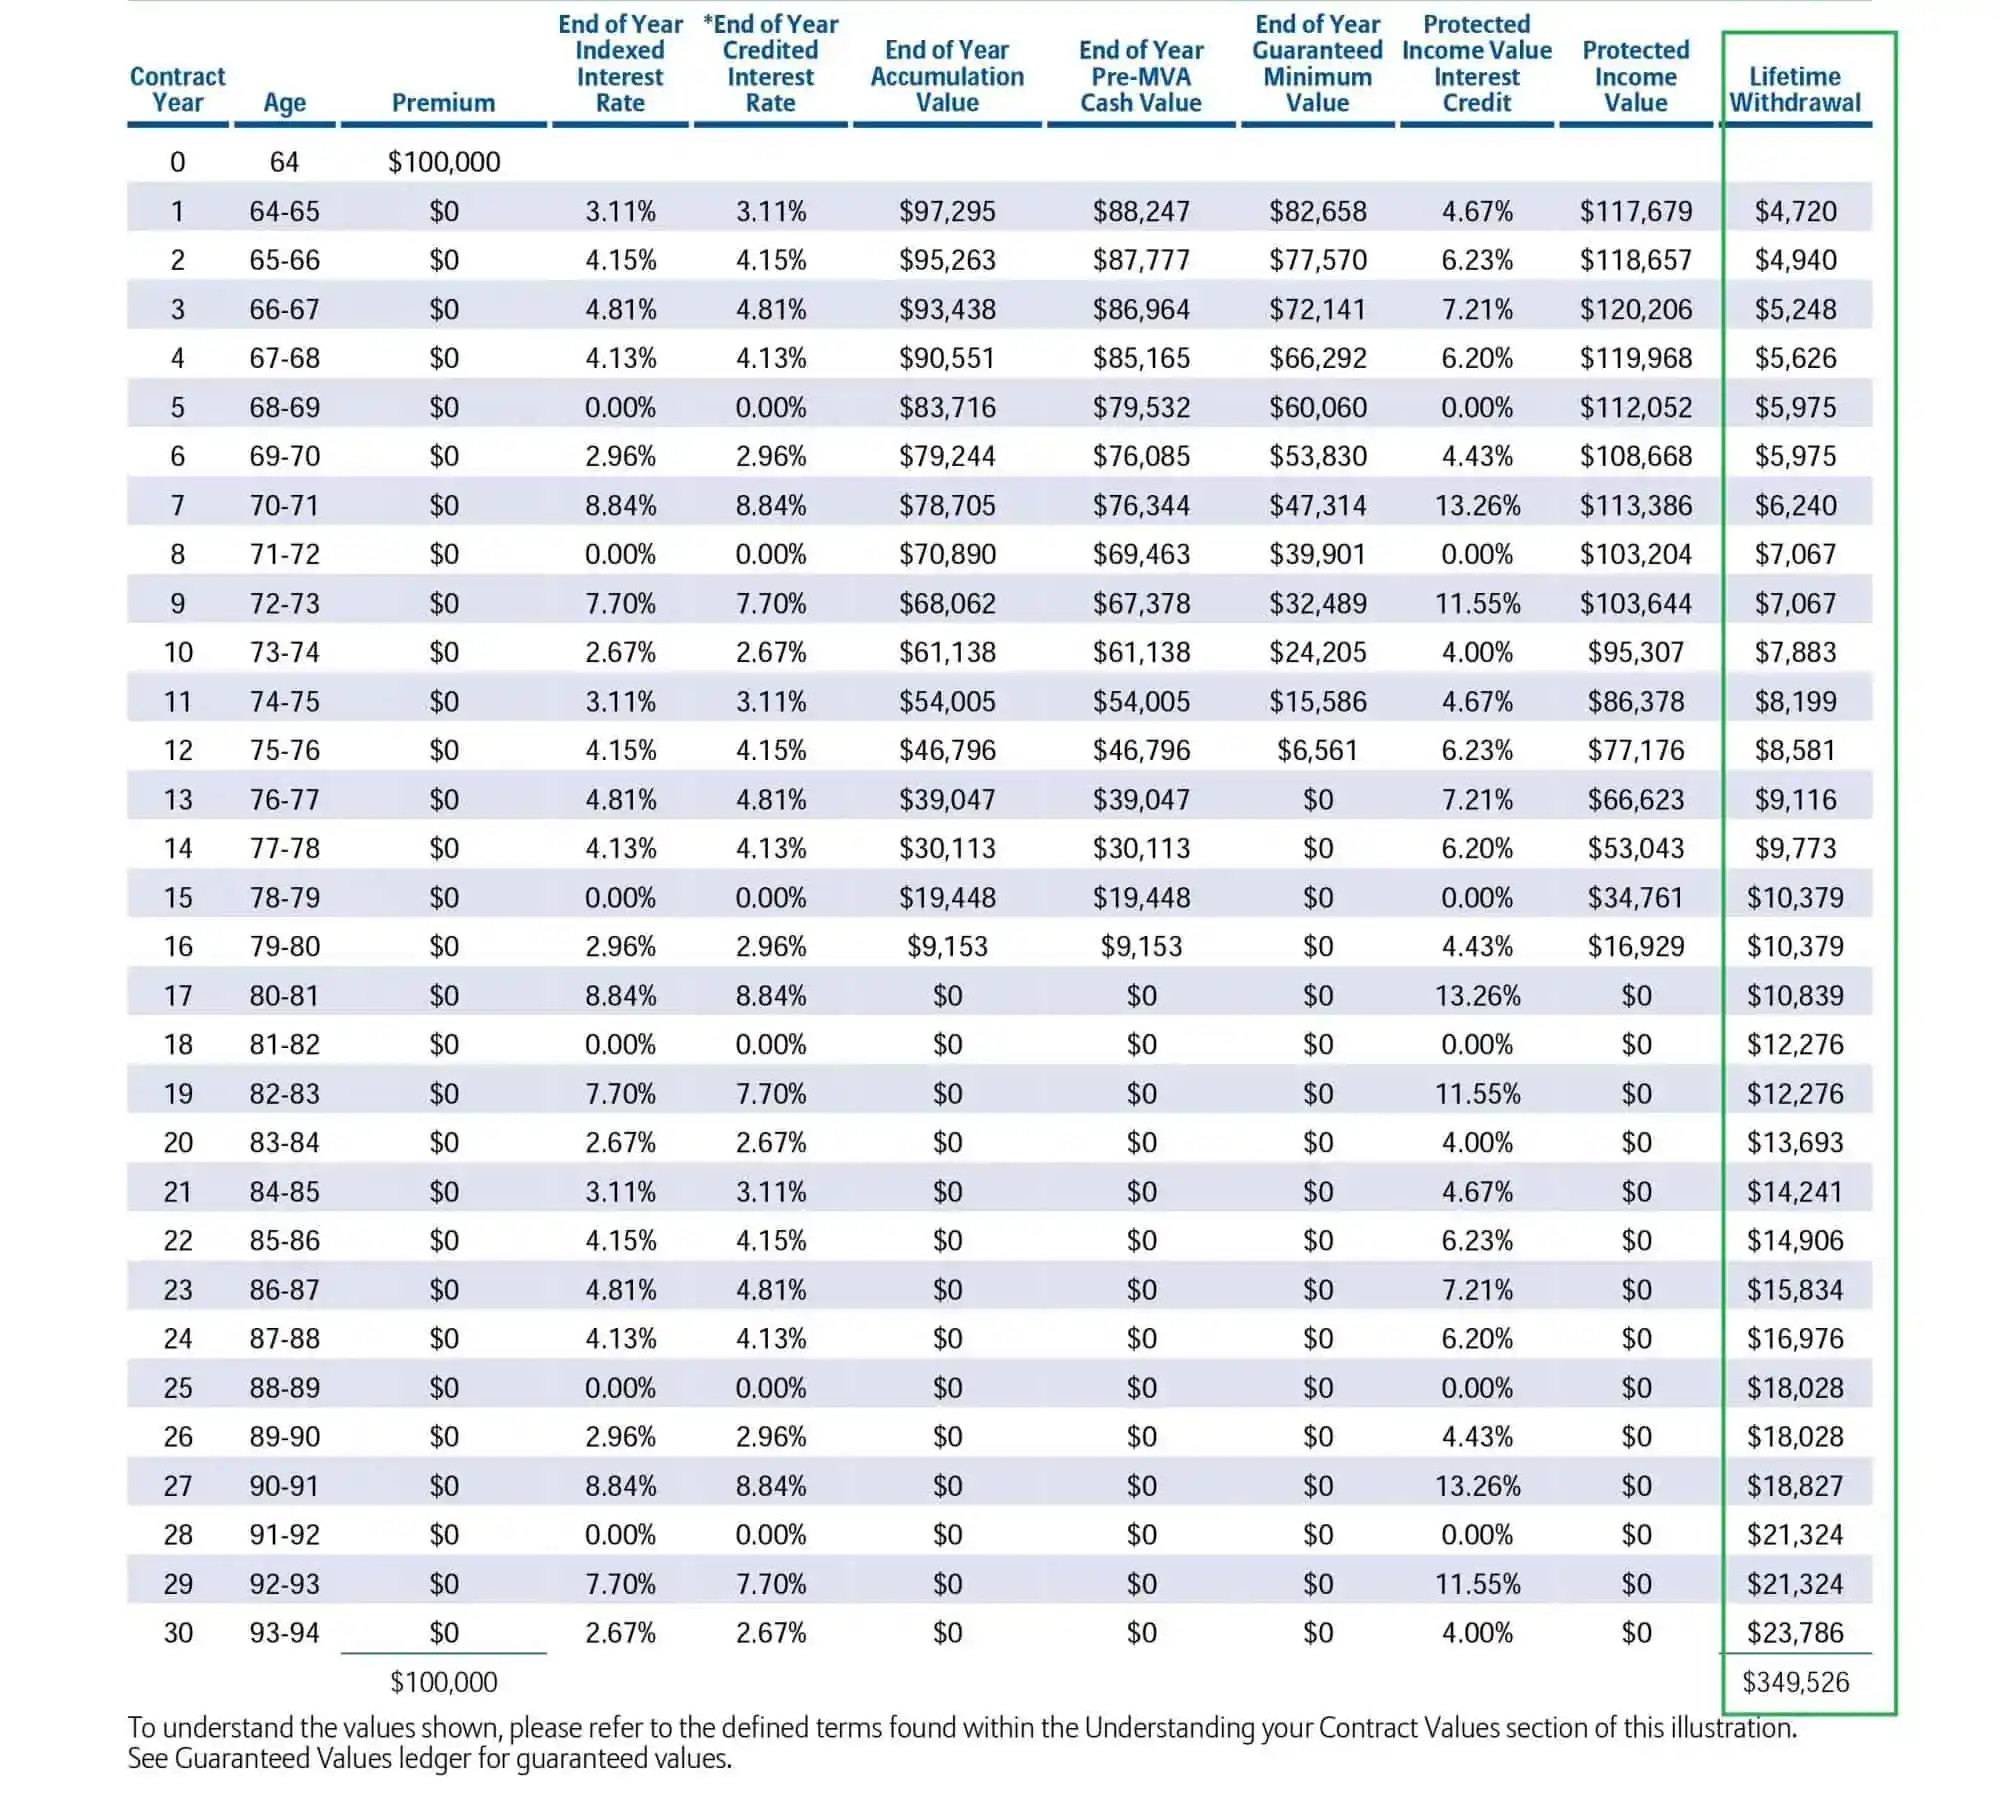
Use a fixed index annuity with a Guaranteed Lifetime Withdrawal Benefit (GLWB) to create income that never runs out, even if your account does. Income depends on age and deferral period.
GLWB Example:
- At age 62: about $35,800 annually
- At age 67: about $39,050 annually
- At age 70: about $41,450 annually
✔ High lifetime income—often more than 4% rule
✔ Keeps paying even if the balance hits $0
✔ Beneficiaries receive the remaining balance
✘ Contracts can be hard to understand
✘ May lock up funds with surrender charges early on
Who Needs It: Retirees who want a high, safe income and hate market risk
Who Doesn’t: Those who want full liquidity or prefer managing their own investments
Note: With a Guaranteed Lifetime Withdrawal Benefit (GLWB), you maintain control of your money, earn interest to grow your savings, and stay protected from stock market downturns. Plus, any unused balance will pass directly to your beneficiaries in a lump sum.

Blending Annuities With Social Security
| Age | GLWB Income | Est. Social Security | Total Income |
|---|---|---|---|
| 62 | $35,800 | $20,000 | $55,800 |
| 67 | $39,050 | $28,000 | $67,050 |
| 70 | $41,450 | $35,000 | $76,450 |
Estimates only: Actual Social Security depends on lifetime earnings and claiming strategy.
Key Trade-Offs: Annuities vs. Other Options
- Annuities vs. CDs: MYGAs (multi-year guaranteed annuities) often pay higher rates than CDs and add contractually guaranteed growth, but CDs are FDIC insured and more liquid.
- Annuities vs. Mutual Funds: Funds can outperform in bull markets but lack downside protection. Annuities cap some upside but protect principal and provide lifetime income.
- Annuities vs. DIY Withdrawals: DIY withdrawals provide flexibility but risk running out of money. Annuities remove longevity risk by paying for life.
Longevity Risk Example
If you withdraw $25,000 per year from a $500k portfolio and live to 85, your savings may run out depending on investment returns. With an annuity, income continues even if the account value goes to zero. This is the insurance protection only annuities provide.
Factors That Determine How Long $500,000 Will Last
- Retirement age: Retiring at 55 vs. 67 changes the time horizon dramatically.
- Spending habits: $40,000/year depletes funds twice as fast as $20,000/year.
- Healthcare costs: Medicare covers basics, but long-term care isn’t included. LTC insurance or hybrid annuities may be needed.
- Taxes: Withdrawals from traditional 401(k)/IRA accounts are taxed as ordinary income. Roth IRAs and Roth IRA annuities offer tax-free withdrawals.
- Inflation: Erodes purchasing power, making inflation-protected income (like some annuity riders) valuable.
The Impact of Inflation
One of the biggest risks in retirement is inflation slowly reducing your purchasing power. Even if your income looks strong today, 20–30 years later, it may not feel the same.
At age 67, combining a Guaranteed Lifetime Withdrawal Benefit (GLWB) annuity of about $39,050 annually with an estimated $28,000 Social Security benefit gives a total income of $67,050 per year. But the real question is—how much will that be worth after inflation?
| Years in Retirement | Age | Nominal Income (GLWB + SS) | Purchasing Power in Today’s Dollars* |
|---|---|---|---|
| Start (Year 0) | 67 | $67,050 | $67,050 |
| 5 years | 72 | $67,050 | ~$57,800 |
| 10 years | 77 | $67,050 | ~$49,800 |
| 18 years | 82 | $67,050 | ~$42,900 |
| 20 years | 87 | $67,050 | ~$37,000 |
| 25 years | 92 | $67,050 | ~$31,800 |
| 30 years | 97 | $67,050 | ~$27,200 |
*Adjusted for 3% annual inflation.
✅ Takeaway: Even though the nominal income stays level at $67,050, inflation steadily erodes its buying power. After 20 years, it feels more like $37,000, and after 30 years, it’s closer to $27,000.
👉 This is why many retirees either:
- Add an inflation rider on annuities,
- Pair fixed annuity income with growth assets, or
- Keep some money in equities to hedge rising costs.
Related Insurance To Consider
- Long-Term Care Insurance or LTC Annuities: Protects against the high cost of nursing homes or in-home care.
- Disability Insurance: For those retiring early or still working part-time.
- Life Insurance: Ensures loved ones aren’t burdened financially and can replace income lost through annuitization.
Conclusion
$500,000 can last anywhere from 10 years to a lifetime in retirement, depending on your income strategy. Using annuities with GLWBs or SPIAs creates a pension-like safety net, while investments add growth potential. Social Security provides additional stability. The key is not just how much you withdraw, but how you protect yourself against risk, inflation, and longevity.
Contact The Annuity Expert’s financial advisors and insurance agents for free quotes and comparisons to find the right mix of income and protection.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
Is $500,000 enough to retire comfortably?
Yes, if paired with Social Security and moderate spending. Alone, it may only cover basics unless structured with an annuity.
How much does a $500,000 annuity pay per month?
Around $2,900–$3,400 monthly, depending on your age, payout type, and the insurer. For a complete breakdown of exactly what to expect, read our master guide on $500,000 annuity income payouts.
How long will $500,000 last with the 4% rule?
About 25 years, assuming no major market downturns and inflation adjustments.
What happens after an annuity’s surrender period?
The account becomes liquid. You can withdraw without penalty, keep the annuity for income, or move it to a new product.