

What four hundred thousand dollars realistically pays in retirement—and why the number is never the same for everyone.
For many retirees, converting a lump sum into a predictable monthly check feels like creating a personal pension. The real question isn’t whether an annuity pays income—it’s how much income you can realistically expect and what trade-offs come with it.
The quick answer:
For most people between ages 65 and 70, a $400,000 annuity typically pays between $2,200 and $3,000 per month based on 2026 benchmarks, assuming a plain-vanilla lifetime income structure.
Why it varies:
$400,000 isn’t a salary—it’s capital. Insurers calculate payouts using your age, life expectancy, and how much risk and protection you want them to assume. Add survivor benefits, inflation protection, or refund features, and the starting check drops. Remove them, and income rises.
Managing a larger estate? See our guide on Jumbo Annuity Rates for $1M+ Portfolios
Annuity Income Heat Map
The income heat map below presents estimated lifetime income based on several ages and payout-start dates. Use our estimated annuity calculator to explore additional income scenarios. Fill out the contact form below to receive a custom income heat map based on your age, state, and income needs.

Payout Estimates by Age and Gender (2026 Benchmarks)
The age factor:
Older buyers receive higher monthly income because payments are expected to last fewer years, not because of better terms.
Sample estimates – Immediate Life-Only Annuity ($400,000 premium):
- Age 60: ~$2,160/month (Male) | ~$2,040/month (Female)
- Age 65: ~$2,400/month (Male) | ~$2,240/month (Female)
- Age 70: ~$2,720/month (Male) | ~$2,520/month (Female)
- Age 75: ~$3,120/month (Male) | ~$2,760/month (Female)
These assume immediate income, single life, no inflation adjustment, and no survivor or refund features. Change any variable, and the payment changes.
The numbers above are estimates. To see exactly what top-rated carriers will pay you based on your birthdate and state, run a custom $400k quote here
Level Income Payouts for a $400,000 Annuity
A level income payout provides the same monthly amount for life or a set period. Once income begins, it never increases.
Why people choose it:
- Highest starting income
- Ideal for covering fixed costs like housing, insurance, and utilities
The downside:
- Inflation steadily erodes purchasing power
- The payment doesn’t grow as expenses rise.
Illustrative examples for $400,000:
| Age at Purchase | Start Now | Start in 5 Years | Start in 10 Years | Start in 20 Years |
|---|---|---|---|---|
| 45 | ~$1,824 | ~$3,408 | ~$5,152 | ~$10,232 |
| 55 | ~$2,520 | ~$4,072 | ~$6,360 | ~$12,172 |
| 65 | ~$3,040 | ~$4,656 | ~$7,280 | ~$12,944 |
| 70 | ~$3,340 | ~$5,088 | ~$8,168 | ~$11,048 |
Deferring income can increase future payments, but requires other income sources during the waiting period.
$400,000 Annuity Increasing Income Payouts
An increasing income payout starts lower and grows over time based on a contractually defined adjustment.
Who this fits:
- Retirees with other income early on
- Those focused on maintaining purchasing power later in retirement.
Trade-off:
- Lower income upfront
- Higher income later
For $400,000, the starting income is typically 10–25% lower than a comparable level payout.
| Age at Purchase | Now | Start in 5 Years | Start in 10 Years | Start in 20 Years |
|---|---|---|---|---|
| 45 | $1,258.80 | $2,068.40 | $3,220.00 | $5,386.80 |
| 55 | $1,833.20 | $2,566.80 | $3,934.80 | $6,613.20 |
| 65 | $2,333.20 | $3,388.40 | $5,049.60 | $8,853.20 |
| 70 | $2,396.80 | $3,605.20 | $5,298.00 | $7,166.40 |
Joint Life Payouts for a $400,000 Annuity
A joint life payout continues income as long as either spouse is alive.
Why is the income lower?
The insurer expects to pay for a longer period.
Why couples choose it:
- Protects the surviving spouse
- Prevents income loss after the first death
This option prioritizes survivor protection, not income maximization.
| Age | Age 60 | Age 65 | Age 70 |
|---|---|---|---|
| Age 60(Spouse 2) | $2181.60 | $2181.60 | $2181.60 |
Advanced Payouts on a $400,000 Annuity
An advanced payout provides higher income early, followed by a permanent reduction later.
Why people use it:
- Bridging income gaps before Social Security or pensions
- Front-loading income during early retirement years
The trade-off:
Once reduced, the lower amount continues for life. This strategy only works when future income is reliable and planned.
| Ages | Years 1-10 | Years 11+ |
|---|---|---|
| Age 60 | $2,700 | $1,620 |
| Age 65 | $3,000 | $2,000 |
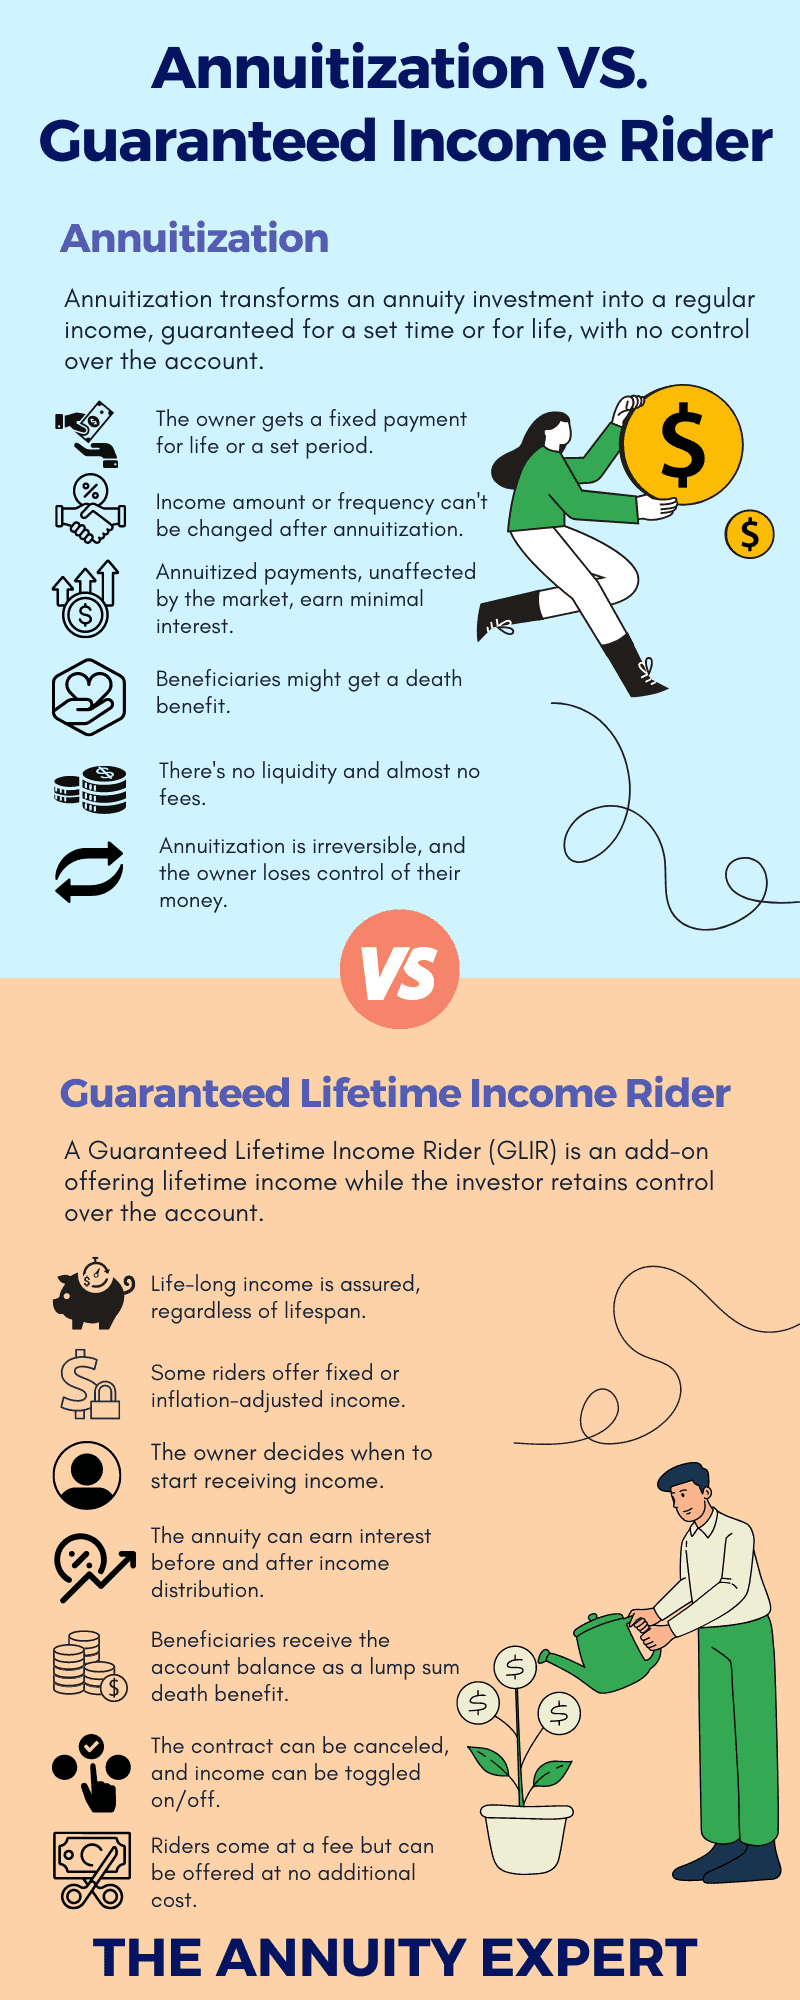
The “Old Way” vs. the “New Way” to Get Annuity Income
The Old Way: Annuitization (SPIA)
You give the insurance company your $400,000 and receive a lifetime paycheck.
What that really means:
- No access to the principal
- Limited or no inheritance
- Irreversible decision
If you die early, payments usually stop unless expensive add-ons were purchased.
The New Way: Income Riders (GLWBs)
A Guaranteed Lifetime Withdrawal Benefit (GLWB) provides lifetime income without giving up ownership of the money.
Key difference:
- You keep control of the $400,000.
- Income is contractually guaranteed for life.
- Any remaining account value is distributed to the beneficiaries.
- You get income and preserve flexibility and legacy.
Why This Matters
Income no longer requires surrendering the asset.
Modern annuities allow retirees to:
- Create a personal pension
- Maintain control and liquidity.
- Leave money to heirs.
Many retirees are never shown this option.
Key Factors Influencing a $400,000 Annuity Payout
- Interest rates:
Higher long-term yields allow insurers to support higher payouts. 2026 conditions remain stronger than the recent ultra-low-rate environment. - Immediate vs. deferred income:
Delaying income often raises monthly payments but delays certainty. - Inflation protection:
Cost-of-living adjustments reduce starting income, with benefits appearing later.
An annuity guarantees income forever. But if you keep your money in cash or bonds, you run the risk of depleting your account too early. See our analysis on How Long $400,000 Actually Lasts in Retirement without a guaranteed rider.
Tax Implications: What You Actually Keep
Qualified money (IRA or 401(k)):
- 100% of each payment is taxed as ordinary income
- Payments satisfy Required Minimum Distributions (RMDs)
Non-qualified money (cash or brokerage):
- Annuitization: Uses the Exclusion Ratio, splitting payments between taxable interest and non-taxable principal
- GLWBs: Taxed under LIFO, meaning gains are taxed first until exhausted
See What Your $400,000 Can Really Pay
A $400,000 annuity can generate meaningful lifetime income, but results vary based on structure. The difference between annuitization and modern income riders determines how much income you receive, how much flexibility you keep, and whether your family inherits anything.
Is a $400,000 nest egg enough to quit working today? It depends heavily on your Social Security claiming strategy. Read our specific guide: Can You Retire at 70 with $400,000?
At The Annuity Expert, we compare real contracts from multiple A-rated insurance companies and show income options side by side—no pressure, no obligation.
Contact The Annuity Expert for free quotes and see exactly how much lifetime income your $400,000 can generate—without giving up control or disinheriting your family.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.