

Is The Allianz Core Income 7 Fixed Index Annuity A Good Annuity?
Short Answer: The Allianz Core Income 7 is a middle-of-the-road lifetime income annuity in our opinion. Allianz is a fantastic insurance company, but we frequently see other A- or better-rated companies offering higher guaranteed lifetime income. If Core Income 7 happens to be competitive when you are ready to buy, it can work. If it pays less, there is no reason to accept a lower retirement income.
Allianz Core Income 7 Annuity Overview
The Allianz Core Income 7 with Core Income Benefit rider is a fixed indexed annuity designed primarily to provide guaranteed lifetime income while protecting principal from direct stock-market losses.
- Product Type: Fixed Indexed Annuity
- Primary Purpose: Guaranteed Lifetime Income
- Surrender Period: 7 Years
- Income Rider: Core Income Benefit rider
- Income Options: Level Income or Increasing Income
- Income Start: Lifetime withdrawals can begin at age 50 or older under the contract provisions
- Free Withdrawals: Up to 10% of paid premium annually after the first contract year and before lifetime withdrawals begin
- Additional Premium: Available during the first contract year or until lifetime income begins, whichever occurs first
- Market Value Adjustment: Yes
Allianz is an excellent annuity company. Allianz currently carries an A+ rating from AM Best, so our criticism of Core Income 7 is about the product’s competitiveness, not the financial strength of the insurance company.
Our Professional Opinion
Our professional opinion of the Allianz Core Income 7 is that the product is middle of the road at best for guaranteed lifetime income.
The biggest issue is the payout. In the comparisons we commonly run, Core Income 7 frequently does not produce as much guaranteed lifetime income as other annuity companies.
With a lifetime income annuity, this is not complicated. How much income are you actually going to receive?
If you put the same amount of money into another A- or better-rated insurance company and that company will pay you more every month for the rest of your life, choosing the lower-paying annuity means less spendable retirement income for you.
Allianz is a fantastic company. That does not automatically make every Allianz annuity a fantastic product. In our opinion, many Allianz products are simply middle of the road, and Core Income 7 frequently falls into that category.
The other issue is accumulation. We think the growth potential in Core Income 7 is not great. The product currently offers traditional S&P 500, Nasdaq-100, and Russell 2000 strategies, which we like seeing, but the caps on those strategies can be changed at future renewals subject to contractual minimums.
Allianz also offers engineered Bloomberg strategies where some of the larger participation rates may be found. A large participation rate on an engineered or excess-return index can look impressive, but you cannot compare that number directly with a cap or participation rate on the true S&P 500, Nasdaq-100, or Russell 2000.
Our concern is the same one we have with several Allianz products: Allianz retains substantial control over your future upside potential because caps, spreads, and participation rates can be changed at renewal.
If the primary purpose of the annuity is lifetime income, we can live with mediocre growth if the guaranteed income payout is excellent. But when the payout is also mediocre, there is not much reason for us to favor this contract over a stronger competitor.
That is why we would never purchase Core Income 7 without comparing it against the entire income annuity market first. If it is currently one of the highest-paying contracts for your age, state, premium, and income start date, then it is a viable option. If it is not, we would choose the annuity that pays more.
What We Like
- Strong Insurance Company: Allianz easily meets our A- or better financial-strength requirement.
- Guaranteed Lifetime Income: The Core Income Benefit can continue providing lifetime withdrawals even if the account value is eventually depleted under the rider provisions.
- 7-Year Surrender Period: The commitment is shorter than many 10-year income annuities.
- Guaranteed Withdrawal Percentage Increases: Beginning at the applicable age, the lifetime withdrawal percentage increases for each year income is deferred under the rider rules.
- Level Income: Provides predictable lifetime payments once income begins.
- Increasing Income: Offers the potential for future payment increases when positive interest is credited.
- Traditional Index Choices: The current product offers the S&P 500, Nasdaq-100, and Russell 2000.
- Principal Protection: Direct market losses do not reduce the annuity’s accumulation value.
- Index Lock: Certain allocations let you lock a positive index value during the crediting period.
- 10% Free Withdrawal Feature: Provides access to a portion of the contract before lifetime income begins.
- RMD Friendly: Applicable required minimum distributions from qualified contracts generally qualify as free withdrawals.
What We Don’t Like
- Income Is Often Not Competitive: We frequently see other A- or better-rated annuities producing higher guaranteed lifetime payouts.
- Growth Potential Is Mediocre: We do not consider Core Income 7 a strong accumulation annuity.
- Renewal Rate Risk: Caps, participation rates, spreads, and fixed rates can be changed after the applicable crediting period.
- Engineered Index Options: Some of the more aggressive-looking participation rates are tied to Bloomberg engineered or excess-return indexes rather than traditional benchmarks.
- Rider Fee: The Core Income Benefit has an annual charge that reduces the contract’s accumulation value.
- Increasing Income Starts Lower: You give up current income in exchange for the possibility of future increases.
- 2-Year Crediting Option: We generally prefer one-year crediting periods when competitive alternatives are available.
- Index Lock Is Not a Cap Lock: Locking an index value during a crediting period does not prevent Allianz from changing future renewal caps or participation rates.
How the Core Income Benefit Works
The Core Income Benefit is a guaranteed lifetime withdrawal benefit designed to produce income without requiring you to permanently annuitize the contract.
One of its main features is a guaranteed increase to the lifetime withdrawal percentage while you wait to begin income.
Beginning at age 45, the applicable withdrawal percentage increases each year until lifetime withdrawals begin. If joint lifetime income is selected, the younger spouse’s age is generally used for the rider calculations.
This part is contractual, which we like. You do not have to rely on index performance to determine whether the withdrawal percentage itself increases while you wait.
However, a larger withdrawal percentage does not automatically mean Core Income 7 produces the highest number of actual income dollars. That is why we compare the final guaranteed payment rather than focusing on the percentage by itself.
Level Income vs. Increasing Income
Core Income 7 gives you two primary ways to receive lifetime income.
Level Income
The Level Income option provides predictable income for life. Once established under the rider provisions, the payment is designed to remain level.
If your priority is maximizing dependable retirement income today, this is the option we would compare against level-income annuities from other carriers.
Increasing Income
The Increasing Income option starts with a lower payment but can increase when the annuity receives positive interest credits.
This sounds attractive, but remember that you are accepting less income upfront.
Increasing income is only better if you live long enough and the increases are large enough to make up for all of the income you gave up in the early years.
We would compare the cumulative break-even point against a competitive level-income annuity before choosing the increasing option.
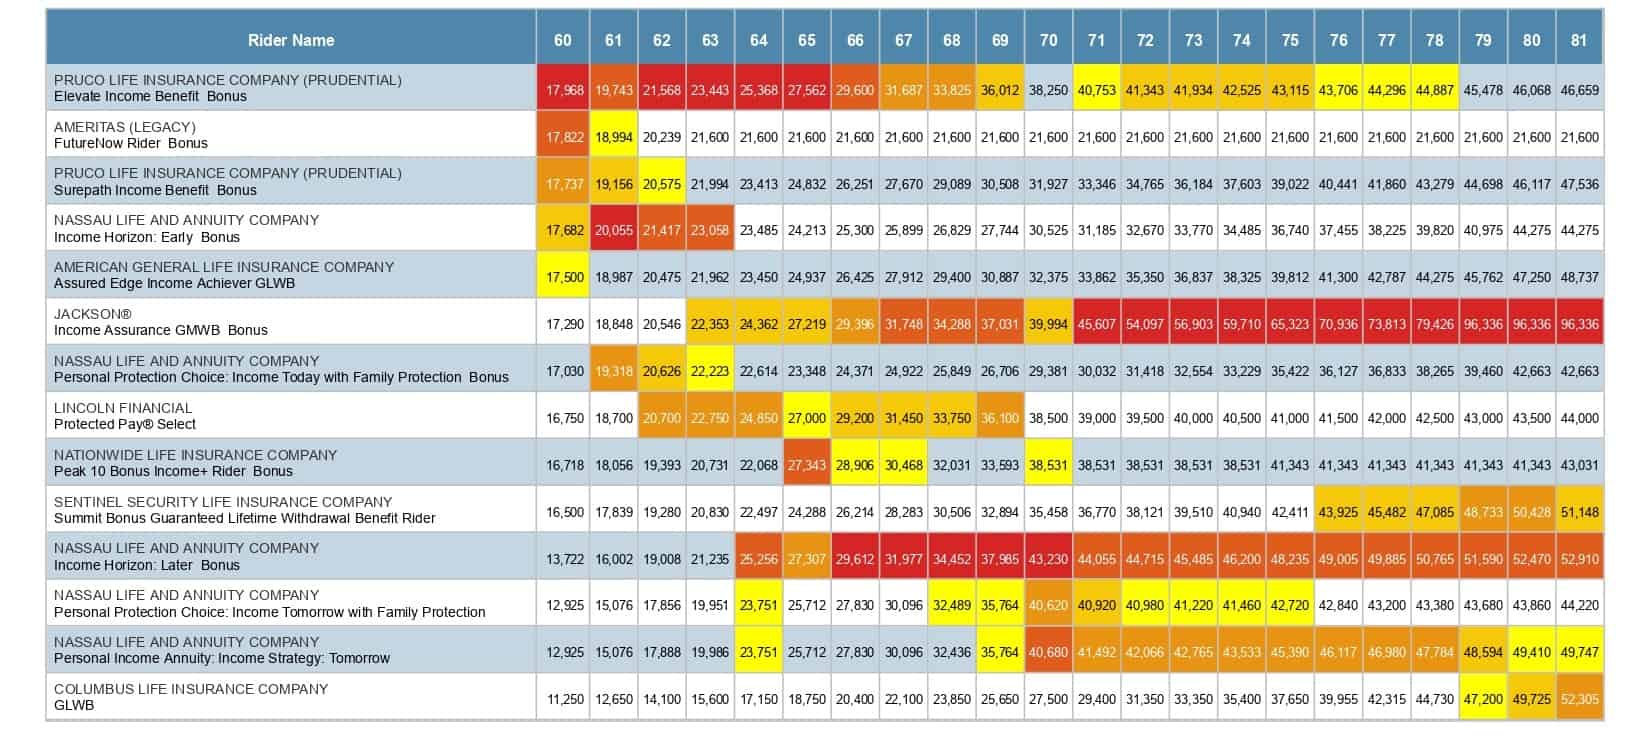
Compare Allianz Core Income 7 Income Payouts
Lifetime income is where this product either wins or loses.
The best income annuity changes as insurance companies adjust payout rates. The result also depends on your age, state, premium amount, whether income is for one or two lives, and when you want the payments to begin.
Contact us and we will create a custom annuity income heat map based on your age, state, premium amount, and desired income start date. We compare A- or better-rated insurance companies so you can see which contract actually provides the highest guaranteed lifetime income for your specific situation.
Growth Potential
We would not buy Core Income 7 primarily for growth.
The current product provides access to several traditional benchmark indexes, including the S&P 500, Nasdaq-100, and Russell 2000. It also offers Bloomberg engineered index strategies.
The traditional index choices are a positive. The problem is that their caps are subject to renewal, and the insurance company can raise or lower them after the applicable crediting period within the contract guarantees.
Similarly, participation rates and spreads on other allocations can change at renewal.
If safe accumulation is the primary goal, we prefer an accumulation-focused FIA with a competitive multi-year cap lock. Two of our favorite alternatives are the Oceanview CapLock and the Sagicor Sage Accumulator.
Traditional and Engineered Index Options
The current Core Income 7 offers both traditional and engineered index choices.
- S&P 500: Traditional large-cap U.S. benchmark.
- Nasdaq-100: Traditional benchmark with substantial exposure to large growth-oriented companies.
- Russell 2000: Traditional U.S. small-cap benchmark.
- Bloomberg US Dynamic Balance Index II: An engineered volatility-controlled benchmark.
- Bloomberg US Dynamic Balance II ER Index: An excess-return engineered index used with participation-rate strategies.
We prefer simple, transparent indexes when the economics are competitive. Do not assume a large participation rate on an engineered excess-return index automatically means more interest than a smaller cap on a traditional index.
Index Lock and Auto Lock
Core Income 7 offers Index Lock on certain participation-rate strategies.
Index Lock lets you lock a positive index value during the crediting period rather than waiting until the scheduled end of the period. Auto Lock can activate the feature automatically after a target is reached.
Do not confuse this with a rate lock. Index Lock locks the index value used in the current crediting calculation. It does not guarantee the same cap, spread, or participation rate for future renewal periods.
Liquidity and Surrender Charges
Core Income 7 has a 7-year surrender-charge period.
| Contract Year | Surrender Charge |
|---|---|
| 1 | 8.50% |
| 2 | 8.00% |
| 3 | 7.00% |
| 4 | 6.00% |
| 5 | 5.00% |
| 6 | 4.00% |
| 7 | 3.00% |
| 8+ | 0% |
After the first contract year and before lifetime income begins, the contract generally allows free withdrawals of up to 10% of paid premium annually.
Withdrawals above the free amount during the surrender period can be subject to a Market Value Adjustment in addition to the surrender charge.
Applicable required minimum distributions from qualified contracts generally qualify as free withdrawals.
Death Benefit
The Core Income 7 provides a standard annuity death benefit rather than an enhanced legacy feature.
The death benefit is generally based on the greatest applicable contract value under the contract provisions, including values such as the accumulation value, guaranteed minimum value, cumulative withdrawal amount, or applicable net-premium calculation.
If lifetime income is already being taken, beneficiaries generally receive the remaining applicable contract death benefit rather than a separate lifetime-income benefit base.

Who Should Consider Allianz Core Income 7?
- Someone Whose Current Payout Is Competitive: A market comparison shows Core Income 7 is producing one of the stronger guaranteed income amounts for your situation.
- Someone Who Values a 7-Year Surrender Period: You prefer a shorter commitment than many 10-year income annuities.
- Someone Who Wants Level Lifetime Income: You want a predictable payment that lasts for life.
- Someone Interested in Increasing Income: You understand the lower initial payment and are comfortable waiting for potential increases.
- Someone Who Values Allianz: You want guarantees backed by a financially strong, highly rated insurance company.
Who Should Probably Buy Something Else?
If another A- or better-rated insurer will pay you materially more guaranteed lifetime income, we would buy the higher-paying annuity.
If safe accumulation is your primary objective, we would choose an accumulation-focused FIA instead because the growth potential on Core Income 7 is not compelling enough for us.
If you dislike renewal-rate risk and want to know that your cap cannot be lowered every year, a cap-lock FIA may be a better accumulation solution.
What We Recommend
We consider Allianz Core Income 7 a middle-of-the-road income annuity.
Allianz is a fantastic insurance company. But with an income annuity, the company name does not pay your bills. The lifetime income payment does.
If Core Income 7 currently produces one of the highest guaranteed payouts available from an A- or better-rated insurance company, then it deserves consideration.
If it pays less, we would choose something else. There is no benefit to voluntarily locking yourself into a lower retirement income when another financially strong company will pay more.
And if accumulation is the goal, we would also look elsewhere. Core Income 7 is an income product first. Its growth potential is secondary and, in our opinion, mediocre compared with stronger accumulation-focused alternatives.
Compare Allianz Core Income 7 Before You Buy
We can compare Core Income 7 against other A- or better-rated income annuities using your actual age, state, premium amount, income start date, and single- or joint-life requirements.
Contact The Annuity Expert for a free custom income heat map and no-obligation quotes. We will show you which annuities currently provide the highest guaranteed income rather than assuming an Allianz product is automatically the best fit.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.