

Understanding Key Insurance Types
Having the right insurance isn’t just smart; it’s essential. In this guide, we’ll break down the 12 key types of insurance everyone should consider to protect their health, income, loved ones, and financial future. Whether you’re just starting or reevaluating your current coverage, this list will help you build a safety net that lasts.
Health Insurance
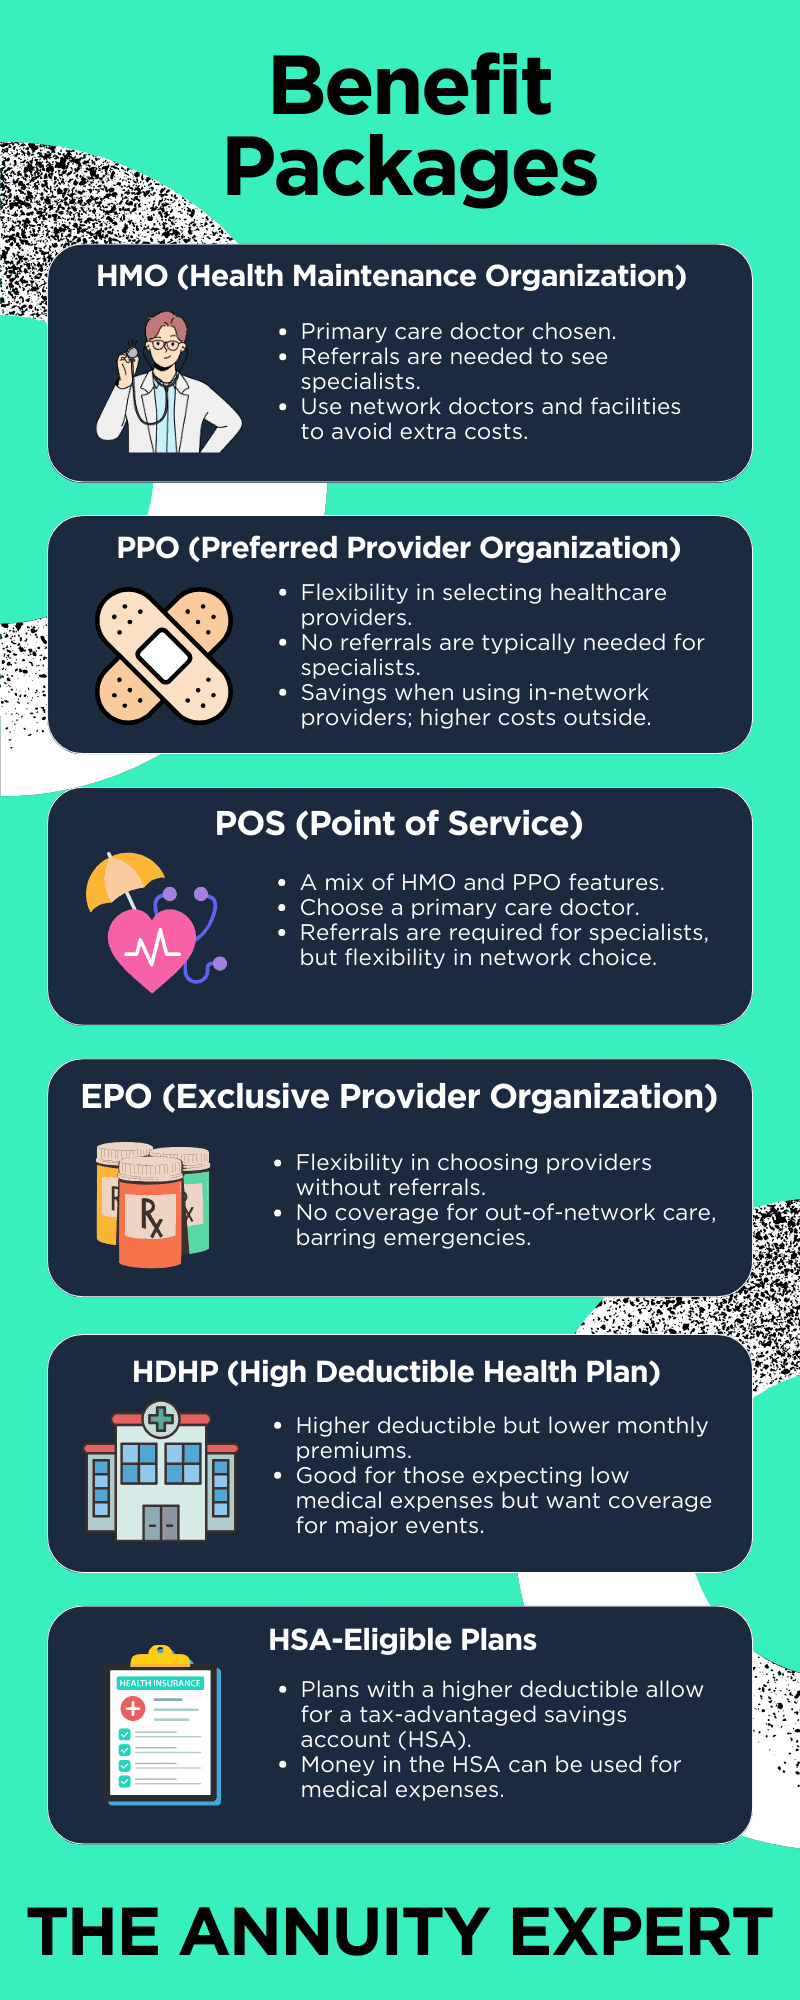
Health insurance is crucial for covering medical expenses, including doctor visits, hospital stays, and prescriptions. Without it, you risk facing significant out-of-pocket costs for medical care. Ensure you have a comprehensive plan that covers preventative care and emergencies.
- Why It’s Important: Covers medical expenses, including doctor visits, surgeries, and prescriptions.
- Pros: Reduces out-of-pocket healthcare costs, ensures access to medical care, and helps prevent medical bankruptcy.
- Cons: Can have high premiums and deductibles.
- Who Needs It: Everyone, especially those without employer-sponsored coverage.
Auto Insurance
Auto insurance protects you financially if you’re involved in a vehicle accident. It covers damages to your car, medical expenses for injuries, and liability for damage or injury you cause to others. Ensure your policy includes collision, comprehensive, and liability coverage.
- Why It’s Important: Covers liability, collision, and damages from accidents.
- Pros: Legally required in most states, protects against financial losses from accidents, repairs, and lawsuits.
- Cons: Premiums depend on driving history, location, and vehicle type.
- Who Needs It: All car owners and drivers.
Homeowners or Renters Insurance
Homeowners insurance protects your home and personal property against damage or theft. Renters’ insurance offers similar protection for those renting their homes. Both types of insurance can help you recover from loss due to fire, theft, or natural disasters.
- Why It’s Important: Protects your home and belongings from damage and theft.
- Pros: Covers property damage, liability, and loss due to disasters.
- Cons: Doesn’t always cover floods or earthquakes (requires separate policies).
- Who Needs It: Homeowners and tenants who want protection for their possessions.
Life Insurance
Life insurance provides financial security for your dependents in the event of your death. It can cover funeral costs and outstanding debts and provide income replacement for your family. Choose between term life insurance, which covers a specific period, and whole life insurance, which provides lifelong coverage.
- Why It’s Important: Provides financial support to your loved ones after your death.
- Pros: Pays for funeral expenses, replaces lost income, and secures your family’s financial future.
- Cons: Premiums increase with age and health conditions.
- Who Needs It: Anyone with dependents, including parents, spouses, and business owners.
Disability Insurance
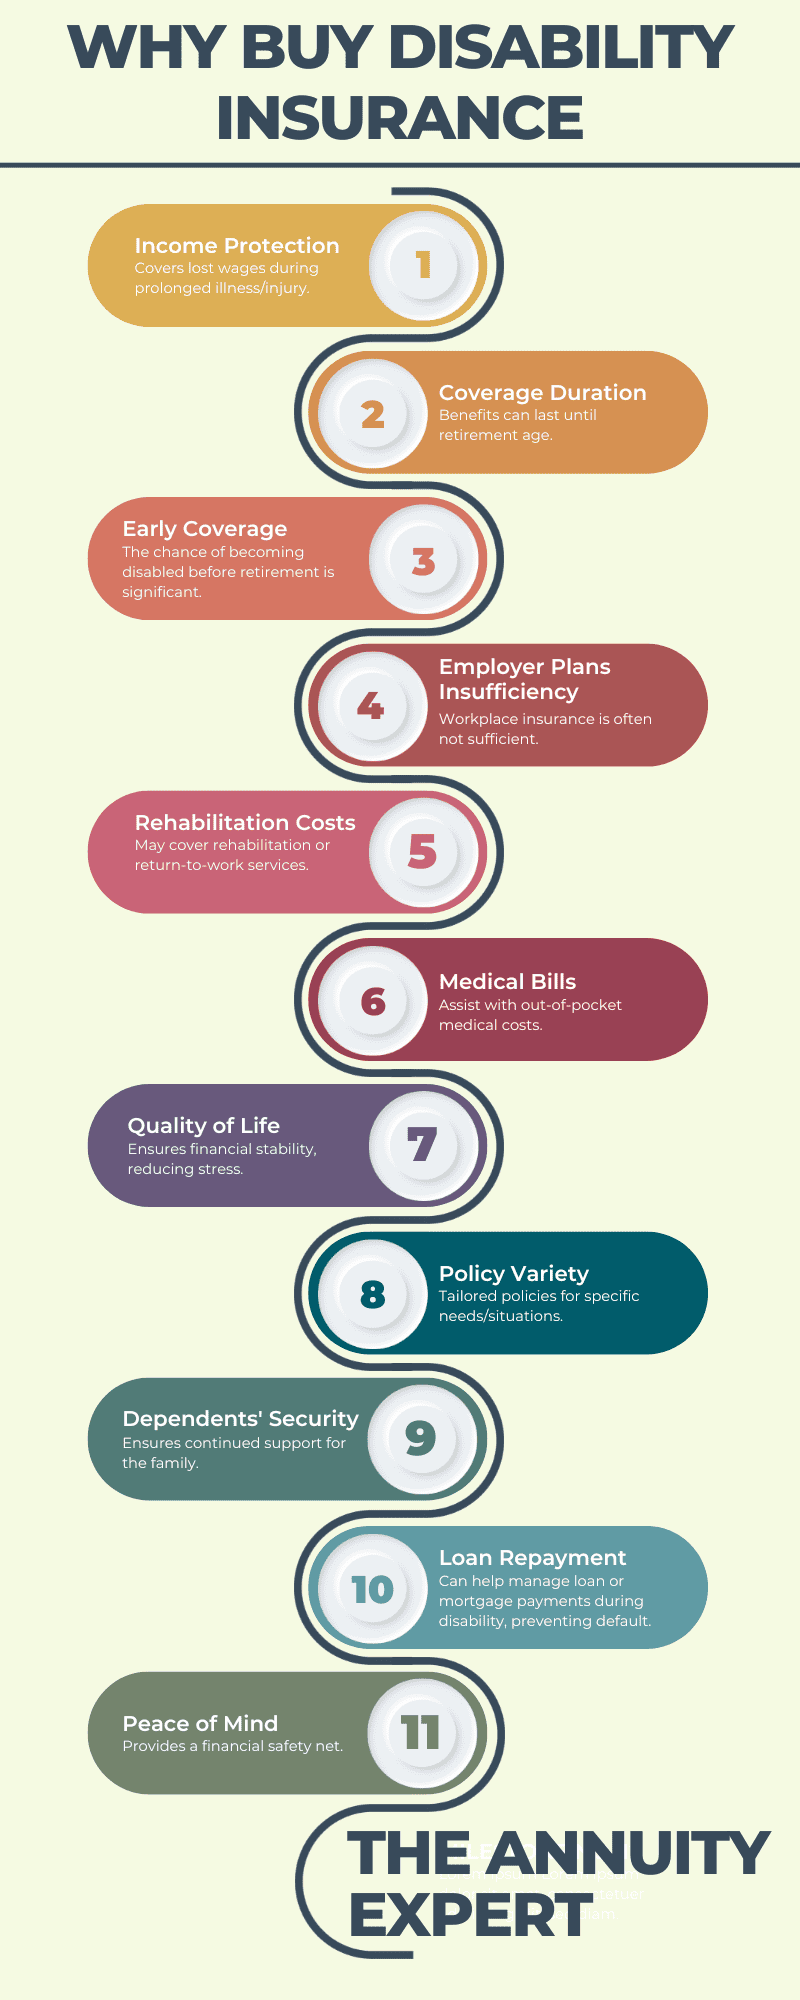
Disability insurance offers income replacement if you become unable to work due to illness or injury. This type of insurance ensures you can maintain your standard of living even when you can’t earn an income.
- Why It’s Important: Replaces income if you’re unable to work due to injury or illness.
- Pros: Provides financial security if you can’t earn a paycheck.
- Cons: Costs vary based on coverage and occupation.
- Who Needs It: Workers who depend on their income, particularly those in physically demanding jobs.
Long-Term Care Insurance
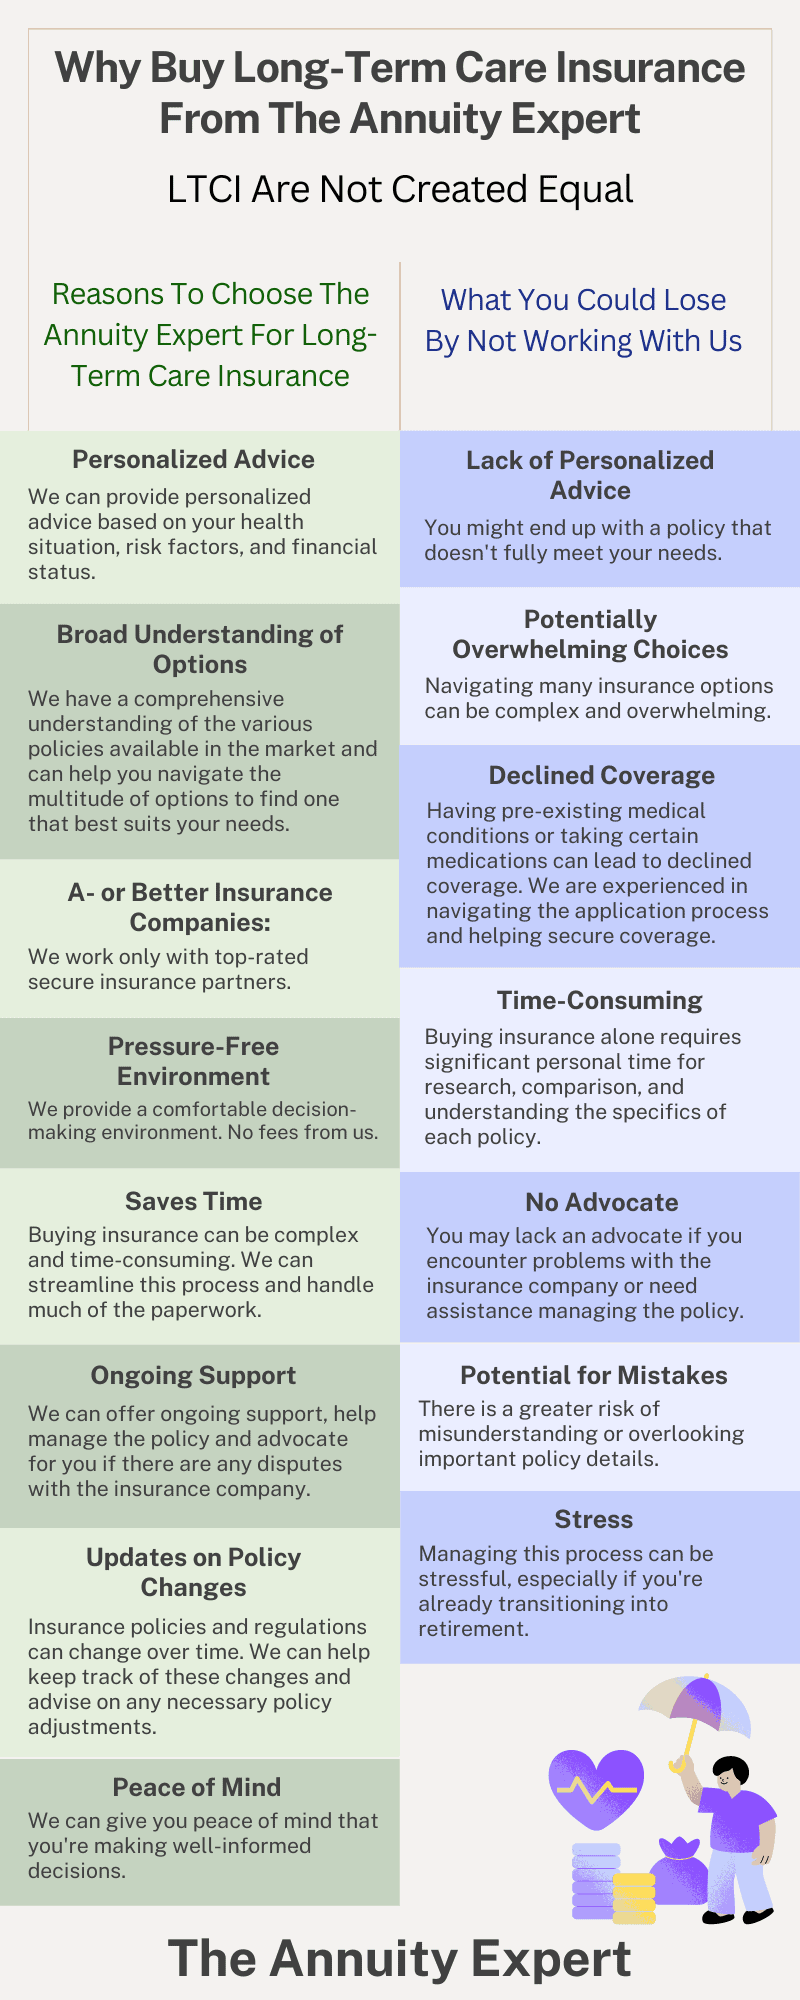
Long-term care insurance covers the costs of long-term services like in-home care, assisted living, or nursing home care. It’s particularly important as you age or if you have a chronic illness.
- Why It’s Important: Pays for nursing homes, assisted living, and home healthcare.
- Pros: Helps cover the high costs of long-term care and preserves assets.
- Cons: Can be expensive, especially if purchased later in life.
- Who Needs It: Those planning for aging-related care, typically in their 50s and older.
Annuities (Retirement Income Insurance)
- Why It’s Important: Provides guaranteed lifetime income during retirement.
- Pros: Ensures a steady cash flow, protects against outliving savings, and offers tax advantages.
- Cons: Limited liquidity, potential high fees.
- Who Needs It: Retirees and anyone seeking a stable, guaranteed income in retirement.
Travel Insurance
- Why It’s Important: Covers trip cancellations, medical emergencies, and lost baggage.
- Pros: Protects against unexpected travel disruptions and medical expenses abroad.
- Cons: Limited coverage depending on policy terms.
- Who Needs It: Frequent travelers, international tourists, and business travelers.
Business Insurance
- Why It’s Important: Safeguards businesses against financial losses due to liability and property damage.
- Pros: Covers lawsuits, business interruptions, and employee-related risks.
- Cons: Premiums depend on industry and coverage needs.
- Who Needs It: Business owners, entrepreneurs, and self-employed individuals.
Pet Insurance
- Why It’s Important: Helps cover veterinary bills for pets.
- Pros: Reduces the financial burden of medical care for pets.
- Cons: May not cover pre-existing conditions.
- Who Needs It: Pet owners, especially those with breeds prone to health issues.
Umbrella Insurance
- Why It’s Important: Provides extra liability protection beyond standard policies.
- Pros: Covers high-cost lawsuits and legal claims.
- Cons: Requires existing home or auto insurance before purchasing.
- Who Needs It: High-net-worth individuals and those at risk of lawsuits.
What Insurance Do You Need?
Your coverage should align with your financial situation, risks, and long-term goals. Book a call with The Annuity Expert today for free quotes and expert guidance on choosing the right insurance for you.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.