

How Americans Living Overseas Can Create Protected Retirement Income
Americans living abroad face a unique retirement challenge. They may still hold retirement assets in accounts like a 401(k) plan, 403(b) plan, or an Individual Retirement Account (IRA), but managing those assets internationally can be complicated. Market volatility, foreign banking restrictions, and currency fluctuations can all impact retirement security.
Solution: Fixed Indexed Annuity with Guaranteed Lifetime Withdrawal Benefit (GLWB)
One solution is converting those retirement assets into a Fixed Indexed Annuity with a Guaranteed Lifetime Withdrawal Benefit (GLWB). This strategy can provide:
- Guaranteed lifetime income
- Protection from stock market losses
- Continued U.S. tax-deferred growth
- A potential death benefit for heirs
For many expatriates, the best annuity solutions include the Nationwide Peak 10 Annuity for lifetime income and the Oceanview CapLock Fixed Indexed Annuity for safe retirement growth.
Eligibility Requirements for Expats Buying Annuities
Most U.S. insurance companies will sell annuities to Americans living overseas, but strict requirements apply.
A U.S. Residential Address
Insurance carriers typically require a United States residential mailing address. Important details:
- The address must be a real residential location
- PO Boxes are not accepted.
- The address must be located within the United States.
This requirement exists because insurance contracts must be issued under a specific state’s insurance regulations.
A U.S. Bank Account
Expats must also maintain a U.S. bank account. Insurance companies use this account to:
- Deposit annuity income payments
- Process withdrawals
- Handle premium transfers
International bank accounts generally cannot be used for annuity transactions.
The Best Annuity for Expats Seeking Lifetime Income
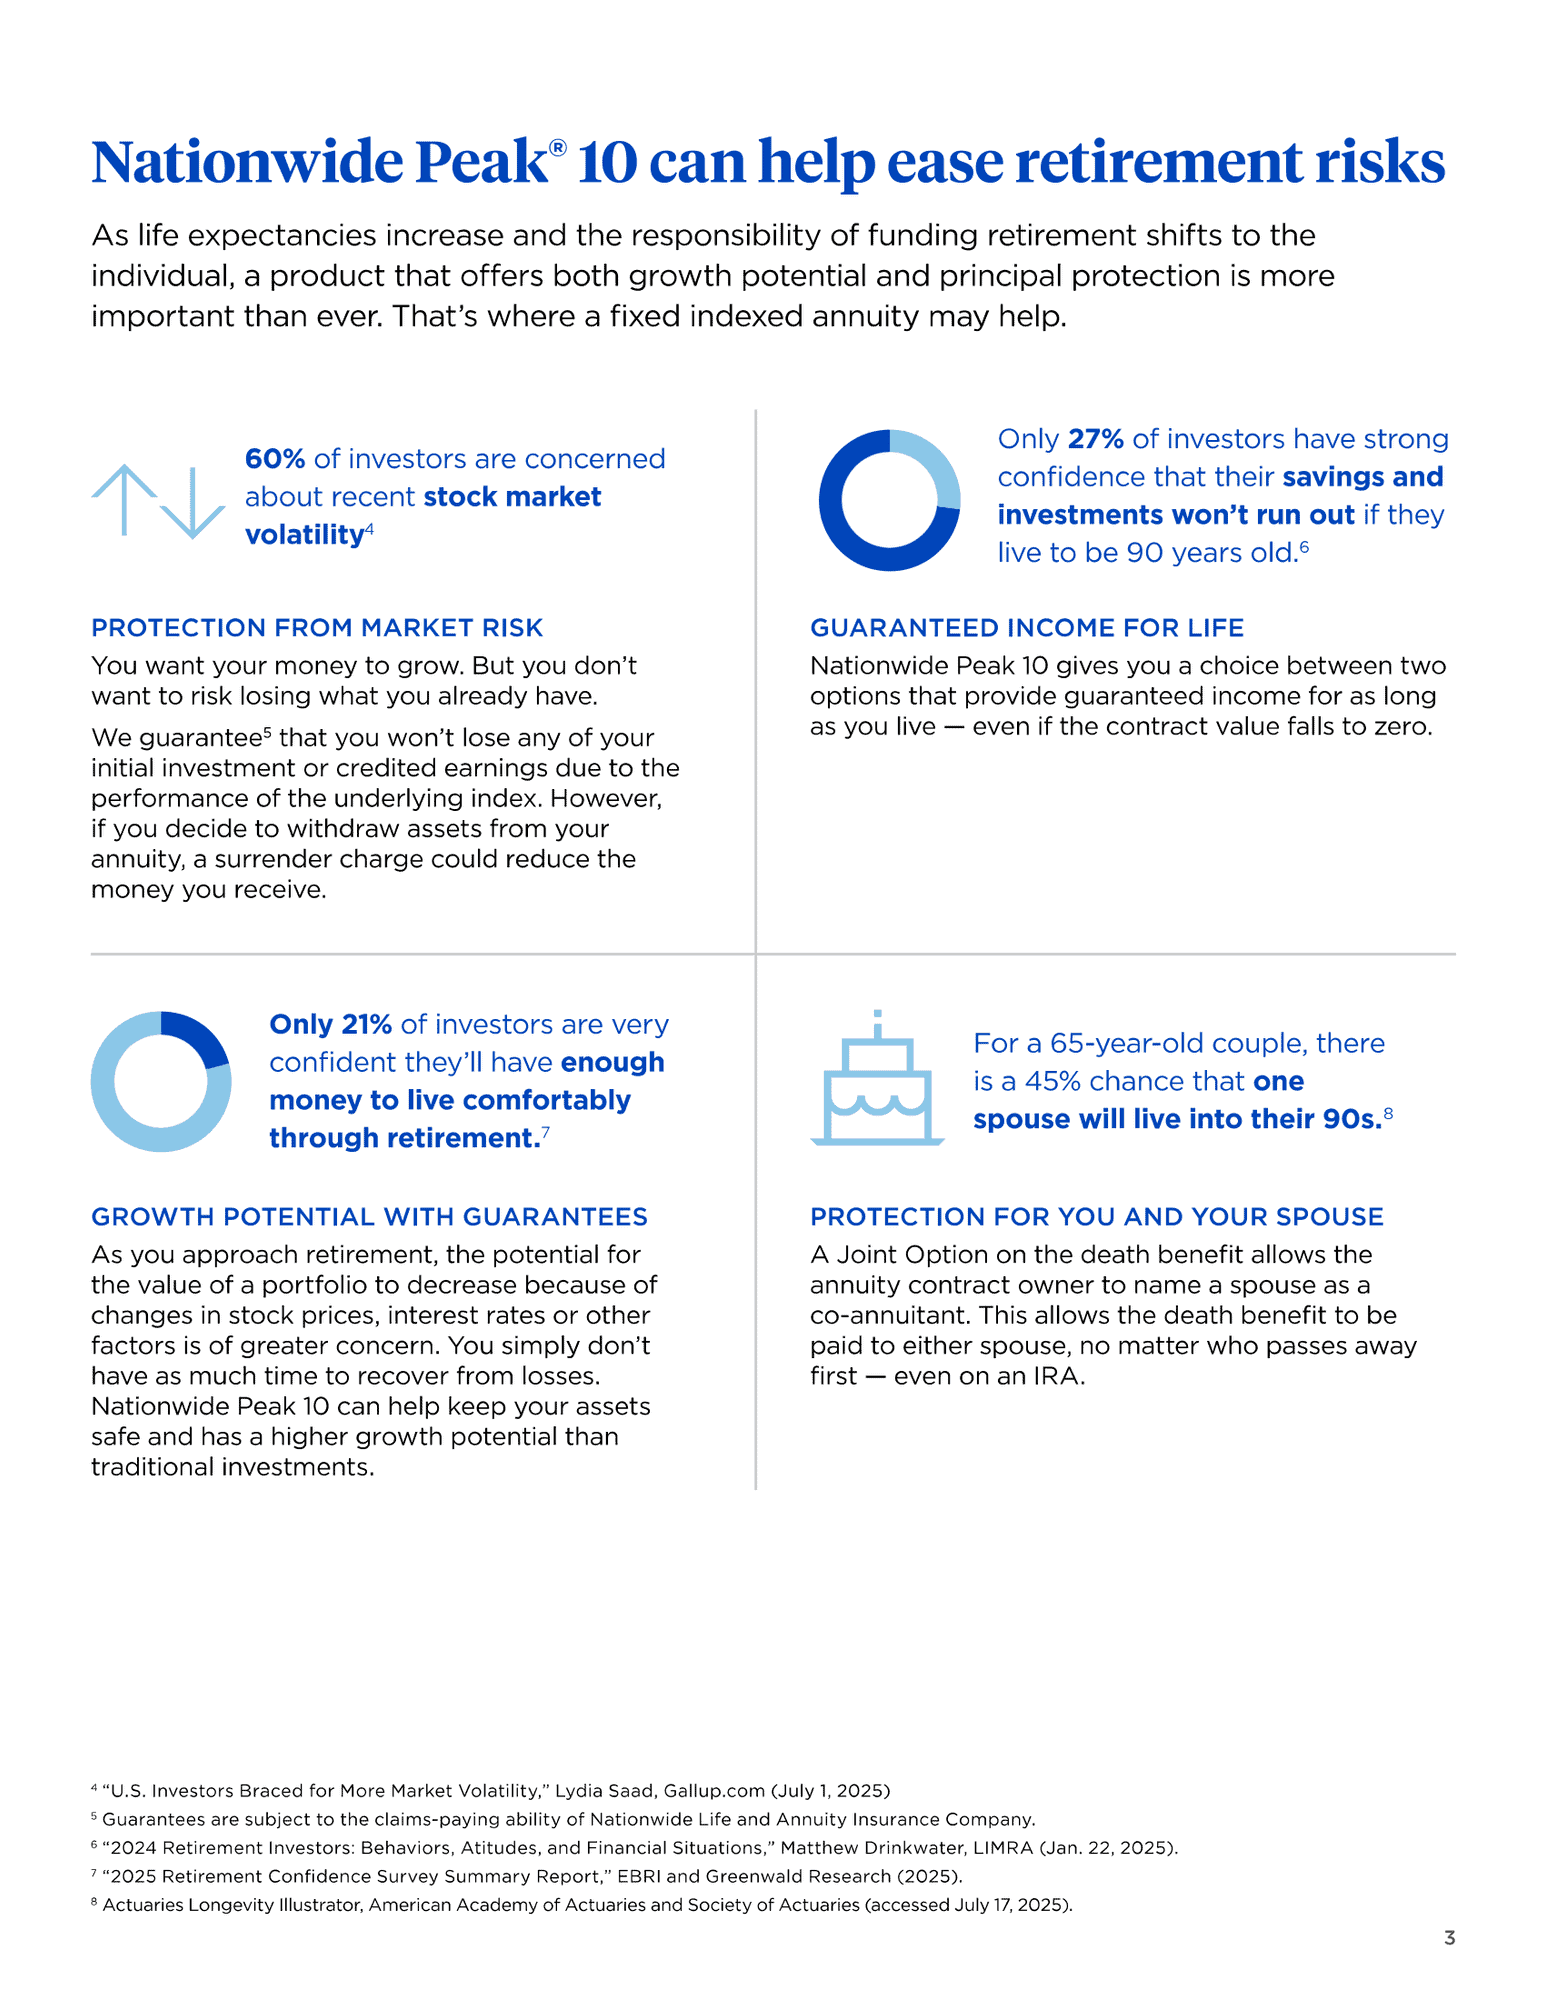
Recommended option: Nationwide Peak annuity with a GLWB rider.
Many Americans abroad want a predictable retirement income without relying on volatile investments. A GLWB annuity provides that stability.
How Lifetime Income Works
When a GLWB rider is activated:
- A separate income value determines the payout amount
- Monthly withdrawals can continue for life.
- Payments continue even if the account value reaches zero.
This structure solves the biggest retirement risk for expats: outliving their money. GLWB annuities often provide higher income payments than traditional joint-and-survivor annuity structures while still preserving flexibility.
Pros and Cons
Pros
- Lifetime income protection
- Principal protection from market losses
- Potential death benefit for beneficiaries
- Continued U.S. tax-deferred growth
Cons
- Rider fees may apply.
- Early withdrawals can trigger surrender penalties.
Who Needs It
- Expats seeking predictable retirement income
- Americans retiring overseas
- Investors concerned about market volatility.
Who Does Not Need It
- Investors who are comfortable managing stock market portfolios independently.
The Best Annuity for Expats Seeking Safe Growth
Recommended option: Oceanview CapLock fixed indexed annuity.
Some expatriates are not ready to activate their lifetime income yet. They may want safe growth while maintaining principal protection. Fixed indexed annuities offer:
- Protection from market downturns
- Interest based on market indexes such as the S&P 500 Index
- Tax-deferred growth inside the annuity
This structure helps preserve retirement savings while still offering growth potential.
Pros and Cons
Pros
- Principal protection
- Tax-deferred accumulation
- Flexible income options later
Cons
- Growth caps limit upside compared to direct stock investing.
Who Needs It
- Expats approaching retirement
- Investors seeking safer alternatives to market volatility

Joint Lifetime Income for Married Expats
Married expatriates must consider income security for both spouses. Many fixed indexed annuities allow joint lifetime withdrawals, meaning payments continue as long as either spouse is alive.
Advantages include:
- Income protection for surviving spouses
- Stable retirement income regardless of longevity
However, joint payouts are typically lower than single-life payouts because the insurer expects to make payments for a longer period.
Another strategy is purchasing separate annuities for each spouse, which can increase overall income flexibility. Some couples also purchase life insurance to protect the surviving spouse or children with a tax-free death benefit.
Death Benefits and Asset Protection for Expats
Annuities can provide death benefits if funds remain in the contract at death.
Beneficiaries typically receive:
- The remaining account value
- A lump sum distribution
Some contracts offer enhanced death benefit riders that increase the amount passed to heirs. This feature can provide inheritance protection for families living in multiple countries.
International Health Insurance Is Essential for Expats
Healthcare coverage is one of the most overlooked risks for Americans living abroad. Medicare generally does not cover medical expenses outside the United States, which means retirees living overseas must secure alternative coverage. This is why expatriates often purchase international health insurance. These policies typically provide:
- Global medical coverage
- Hospital and physician services abroad
- Emergency evacuation coverage
- Access to international hospital networks
Without this coverage, a medical emergency overseas could quickly drain retirement savings.
Other Insurance Expats Should Consider
Life Insurance
Many expatriates maintain life insurance to protect their families financially if they pass away. Life insurance provides a tax-free death benefit that can replace lost income or provide inheritance protection.
Long-Term Care Insurance
Expats may eventually return to the United States or require long-term care later in life. Long-term care insurance helps protect retirement savings from nursing home or assisted living expenses.
Why Comparing Annuities Matters
Not all annuities provide the same income or growth potential. Key factors that affect performance include:
- Income rider structure
- Index crediting strategies
- Age at retirement
- Insurance company pricing
Comparing multiple annuity products helps retirees identify contracts that provide the strongest lifetime income guarantees. An experienced insurance agent can help navigate these options and streamline the process.
Bottom Line
Americans living abroad can still benefit from U.S. annuities as long as they meet the basic eligibility requirements:
- A valid U.S. residential address (not a PO Box)
- A U.S. bank account
For many expatriates, the best annuity strategies involve fixed indexed annuities that provide principal protection and guaranteed lifetime income. Two strong options include:
- Nationwide Peak annuity for lifetime income planning
- Oceanview CapLock FIA for safe accumulation
These annuities can help expats maintain financial stability while living anywhere in the world.
Contact The Annuity Expert to compare the best annuities for expats and receive free quotes for annuity strategies designed to generate lifetime retirement income while living abroad.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.