

Our Professional Opinion on the Nationwide Peak 10 Annuity
We recommend the Nationwide Peak 10 for joint lifetime income when its actual guaranteed payout is competitive with the other A- or better-rated income annuities available for the couple’s ages, state, premium, and desired income start date.
Peak 10 is generally a really good joint-income annuity. In fact, joint income is where we think this product stands out the most.
The Bonus Income+ Joint Option is designed to continue the same level of guaranteed income for the surviving spouse after the first spouse dies. That is important because some joint-income annuities reduce the payment after the first death.
Peak 10 can keep the surviving spouse’s income level instead of forcing that spouse to absorb an income reduction at the same time Social Security or other household income may also decrease.
The current joint payout structure is also relatively competitive compared with the single-life payout structure. The income calculation is based on the younger spouse, which is normal for a joint-life annuity, but the reduction for covering two lives is generally reasonable.
We also like the Bonus Income+ rider’s guaranteed income design. It provides an immediate bonus to the Income Benefit Base and a contractually guaranteed simple roll-up while lifetime income is deferred.
That is much better than relying entirely on index performance to determine the couple’s future retirement paycheck. The contract may receive additional value from positive index performance, but the income plan does not depend solely on that performance.
However, the Income Benefit Base is not cash. The bonus and roll-up are calculation tools used to determine lifetime income. They cannot be surrendered or withdrawn as a lump sum.
We would therefore never recommend Peak 10 merely because the Income Benefit Base looks large on an illustration. The only number that ultimately matters is the actual guaranteed annual income the contract will pay.
If Nationwide provides one of the strongest joint-life payouts available, we recommend the product. If another A- or better-rated company guarantees materially more joint income from the same premium, we would choose the higher-paying annuity.
Another good feature is that there is no required waiting period before lifetime income begins. A couple can start income relatively soon or defer it to build a larger Income Benefit Base and reach a higher payout age.
The rider also permits one nonlifetime withdrawal before lifetime income begins without automatically stopping the guaranteed roll-up or locking in the lifetime withdrawal percentage. That provides more flexibility than many deferred-income riders.
The rider fee needs to be considered. Joint coverage costs more than single-life coverage, and the charge is deducted from the contract value. In years with little or no credited interest, the fee can reduce the remaining account value.
That can affect future liquidity and the amount left to beneficiaries, even though the scheduled lifetime income can continue after the account value reaches zero.
We would not buy Peak 10 primarily for accumulation. The product offers a traditional S&P 500 strategy along with several manufactured or volatility-controlled indexes, but future caps, participation rates, spreads, and fixed rates can change when the applicable strategy term renews.
Peak 10 is not a cap-lock annuity. If safe growth is the primary objective rather than guaranteed lifetime income, we would use an accumulation-focused FIA with stronger contractual rate guarantees.
The contract also has a long surrender period and a Market Value Adjustment. It should be funded with money the couple can leave in place for the long term.
Our bottom line: Nationwide Peak 10 is a good income annuity and can be a great option for joint lifetime income. We like that the surviving spouse can continue receiving the same level of income, the income base receives contractual guaranteed growth, and income can begin without a lengthy mandatory wait. The actual joint payout still has to beat the market, and buyers need to understand the rider fee, long surrender period, and renewal-rate risk.
Compare Peak 10 With the Entire Income Annuity Market
Joint-income payouts can change as insurers adjust rider terms and product pricing. The result depends on both spouses’ ages, state, premium, income start date, and whether the surviving spouse needs the full payment to continue.
Contact The Annuity Expert for a free custom annuity income heat map based on your actual information. We will compare Peak 10 with current joint-life income annuities from A- or better-rated insurance companies.
What We Like
- Strong Joint Income: Peak 10 is generally one of the better products to compare when income needs to cover both spouses.
- Full Spousal Continuation: The same level of scheduled income can continue for the surviving spouse under the Joint Option.
- Competitive Joint Structure: The reduction from single-life to joint-life income is relatively reasonable under the current design.
- Guaranteed Income Growth: The Bonus Income+ rider provides contractual growth of the Income Benefit Base before lifetime income begins.
- Immediate Income Availability: There is no mandatory multi-year wait before scheduled lifetime withdrawals can begin.
- One Nonlifetime Withdrawal: An eligible withdrawal can be taken before income begins without automatically stopping the roll-up or locking the withdrawal percentage.
- Lifetime Income After Depletion: Scheduled payments can continue after the contract value reaches zero, assuming the rider terms are followed.
- Principal Protection: Negative index performance does not directly reduce the contract value.
- Traditional S&P 500 Option: Buyers are not forced to allocate everything to engineered indexes.
- Strong Insurance Company: Nationwide comfortably exceeds our A- minimum financial-strength standard.
What We Don’t Like
- The Joint Rider Costs More: Covering two lives requires a higher annual rider charge than single-life coverage.
- The Benefit Base Is Not Cash: The bonus and roll-up cannot be surrendered or taken as a lump sum.
- The Payout Still Has to Win: A strong joint-income design does not justify accepting less guaranteed income than another financially strong carrier will pay.
- Rider Charges Can Reduce Contract Value: Low or zero credited interest may allow the annual charge to reduce the account value.
- Renewal-Rate Risk: Nationwide can change future caps, participation rates, spreads, and fixed-account rates.
- Engineered Indexes: Several strategies use manufactured or volatility-controlled indexes that are harder to evaluate than the true S&P 500.
- Not a Cap-Lock FIA: Current traditional-index terms are not guaranteed for the full surrender period.
- Long Surrender Period: Excess withdrawals may trigger surrender charges and a Market Value Adjustment.
- Excess Withdrawals Can Damage the Guarantee: Taking more than the rider permits can permanently reduce future lifetime income.
Nationwide Peak 10 Fixed Indexed Annuity Overview
The Nationwide Peak 10 Fixed Indexed Annuity (FIA) is built primarily for people who want contractually guaranteed lifetime income without exposing their retirement savings to stock market losses. It combines principal protection, tax-deferred growth, and a Guaranteed Lifetime Withdrawal Benefit (GLWB) that can generate income for life without forcing the contract owner to annuitize the policy, fostering confidence in its stability.
This annuity’s main strength is its joint lifetime income feature, making it especially appealing for married couples wanting income to continue for the surviving spouse.
However, like most income-focused annuities, the trade-off is a long surrender period and capped growth potential.
Understanding both the benefits and limitations of this annuity is essential before making a purchase decision, ensuring informed choices.
How The Nationwide Peak 10 Fixed Indexed Annuity Works
Product Type: Fixed Indexed Annuity (FIA)
A fixed indexed annuity protects the principal from stock market losses while allowing the account to earn interest linked to market indexes.
If the market index increases, interest is credited subject to caps, spreads, or participation rates. If the market declines, the contract simply earns zero interest for that period instead of losing value. The Nationwide Peak 10 is a single-premium deferred annuity, meaning the owner deposits a lump sum that grows tax-deferred until withdrawals begin.
Funding Sources
This annuity can be funded using:
- Retirement accounts, such as Traditional IRA, Roth IRA, SEP IRA, SIMPLE IRA, 401(k), 403(b), and 457 plans.
- After-tax savings, including cash or personal savings and existing annuities through a 1035 exchange.
Funds grow tax-deferred, with interest compounding without annual taxation until withdrawals begin.
Key Contract Details
- Surrender period: 10 years
- Minimum investment: $25,000
- Maximum investment: Typically $1,000,000 or higher with approval
- Penalty-free withdrawals: Up to 10% annually
- Market Value Adjustment: Yes
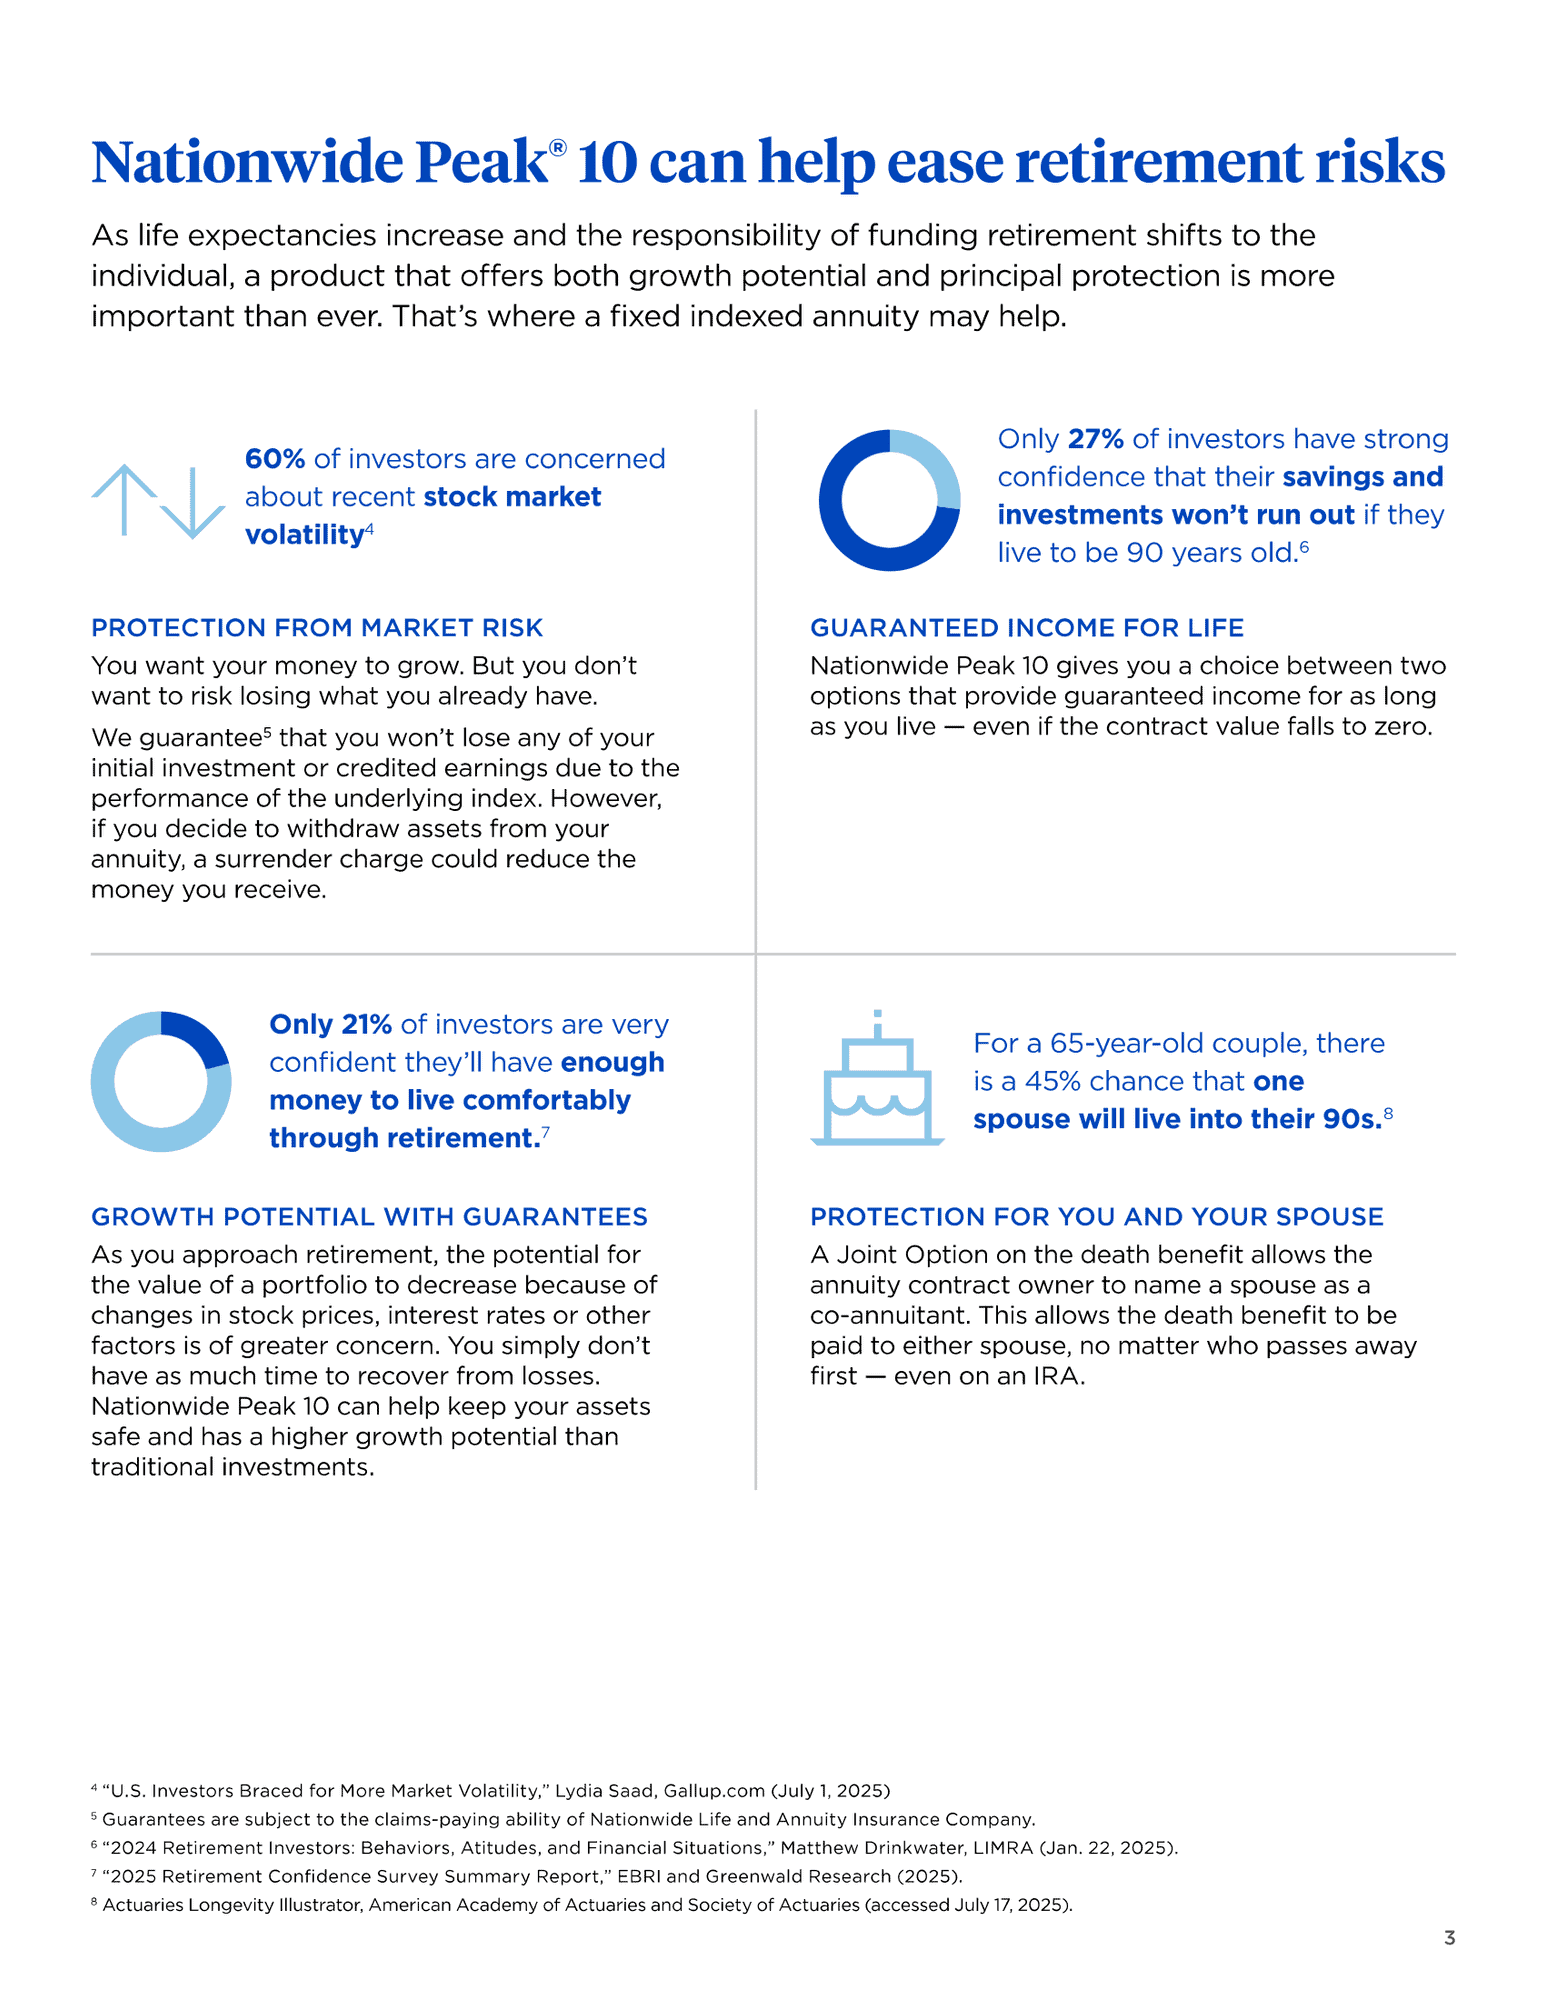
Index Crediting Strategies
The annuity offers interest crediting strategies linked to market indexes like S&P 500 and global multi-asset indexes. Strategies include:
- 1-year point-to-point using cap rates
- 2-year strategies using participation rates and spreads
The 1-Year Fixed Account
Most FIAs include a declared fixed interest option.
The fixed account credits a declared interest rate guaranteed for one year, after which the insurer may adjust the rate annually.
This option is often used by conservative investors who prefer predictable interest instead of index-linked returns.
The Guaranteed Lifetime Withdrawal Benefit (GLWB)
The most important feature of this annuity is the Guaranteed Income Solution rider, which allows the owner to withdraw income for life—even if the account value eventually declines to zero. Unlike annuitization, GLWB income is revocable, meaning the contract owner keeps control of the account value.
Income Benefit Base
The rider uses an income benefit base, which is a calculation value used to determine lifetime income. This value cannot be withdrawn as cash.
During the early years of the contract, the income base grows through annual roll-up credits until withdrawals begin.
Lifetime Withdrawal Percentages
When withdrawals begin, the income payout percentage is determined by the owner’s age.
Generally speaking, the longer withdrawals are delayed, the higher the income percentage becomes.
Step-Up Income Feature
One of the best features of this annuity is the income step-up opportunity.
Each year after withdrawals begin, the insurer compares the account value to the income benefit base.
If the account value is higher, the income benefit base increases, which permanently increases lifetime income.
This means a banner growth year can significantly increase the lifetime income payment, which is rare among guaranteed income products.
Optional Enhanced Income Rider
The annuity also offers an optional rider designed to increase income potential.
This rider typically includes:
- An income-based bonus
- Additional roll-up growth
- An annual rider fee
Liquidity and Withdrawal Rules
- 10% penalty-free withdrawals allowed annually
- Excess withdrawals can trigger surrender charges and Market Value Adjustments (MVAs)
An MVA may increase or decrease the surrender value depending on changes in interest rates.
An MVA may increase or decrease the surrender value depending on changes in interest rates.
Withdrawal Waivers
The annuity typically includes waivers allowing penalty-free withdrawals in certain situations:
- Terminal illness waiver: Allows full withdrawal if diagnosed with a qualifying illness.
- Nursing home confinement waiver: Allows full withdrawal if confined to a nursing facility for a qualifying period.
Death Benefit
If the contract owner dies, the annuity pays the contract value to the named beneficiaries .
A spousal continuation option allows the surviving spouse to continue the annuity contract rather than receiving a lump sum
What Happens After The Surrender Period
- Withdraw the entire account without penalties
- Continue earning interest in the annuity
- Reallocate among available strategies
- Continue lifetime withdrawals through the GLWB
- Convert the contract to annuitized lifetime income
Because annuitization is irreversible, we generally prefer using the GLWB for lifetime income instead.
Pros and Cons
Pros
- Contractually guaranteed lifetime income: The GLWB provides income for life even if the account value eventually reaches zero.
- Joint lifetime income protection: Income can continue for a surviving spouse.
- Potential income increases: Strong market performance can increase future lifetime income payments.
- Principal protection: The contract protects against stock market losses.
- Tax-deferred growth: Interest compounds without annual taxation until withdrawals begin.
Cons
- Long surrender period: A 10-year surrender schedule limits liquidity.
- Capped growth potential: Like all FIAs, market gains are limited.
- Engineered index options: Some index strategies use complex volatility-controlled structures.
- Optional rider costs: Enhanced income riders may add annual fees.
- Not FDIC insured: Annuities are backed by insurance companies and SGA rather than banks.
Who Should Consider This Annuity
- Those wanting contractually guaranteed lifetime income
- Individuals wanting principal protection from market losses
- Married couples seeking a joint lifetime income
- People who can commit to a long-term contract
Who Should Avoid It
- Those needing frequent access to their money
- Individuals preferring simple fixed interest products
- Investors looking for direct stock market participation
- People requiring short-term savings vehicles
Other Insurance That May Be Needed
- Life insurance for wealth replacement and inheritance
- Long-term care insurance for protecting savings against care costs
- Medigap coverage for medical expenses not covered by Medicare
Compare Annuities Before You Buy
Each annuity has unique strengths. The Nationwide Peak 10 is income-focused, and comparing various annuities ensures the best fit for retirement goals.
Shop and Compare Annuities With The Annuity Expert
Contact The Annuity Expert for comparing and purchasing the best annuities tailored to your plan. Our specialists can review existing contracts to ensure they meet your objectives.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Frequently Asked Questions
Is the Nationwide Peak 10 annuity safe?
Yes, fixed indexed annuities protect principal from market losses but are not FDIC insured. Guarantees rely on the insurer’s financial strength.
Does this annuity provide lifetime income?
Yes, the GLWB ensures lifetime income even if the account value declines to zero.
What accounts can fund this annuity?
It can be funded by IRA rollovers, Roth IRA transfers, 401(k) or 403(b) rollovers, SEP IRAs, SIMPLE IRAs, or after-tax savings.
Can lifetime income increase after withdrawals begin?
Yes, if strong growth causes the account value to exceed the income base, lifetime income payments can increase.