

Retirement Income Strategies for Married Couples
Married couples face a different retirement challenge than single investors. One spouse may live much longer than the other. The retirement strategy must provide income for both lives, protect the surviving spouse, and ideally leave something behind for beneficiaries.
Several annuity strategies solve this depending on the couple’s priorities.
The Best Annuity for Married Couples Who Want the Highest Lifetime Income
Best option: Fixed Index Annuities with Joint GLWB Riders
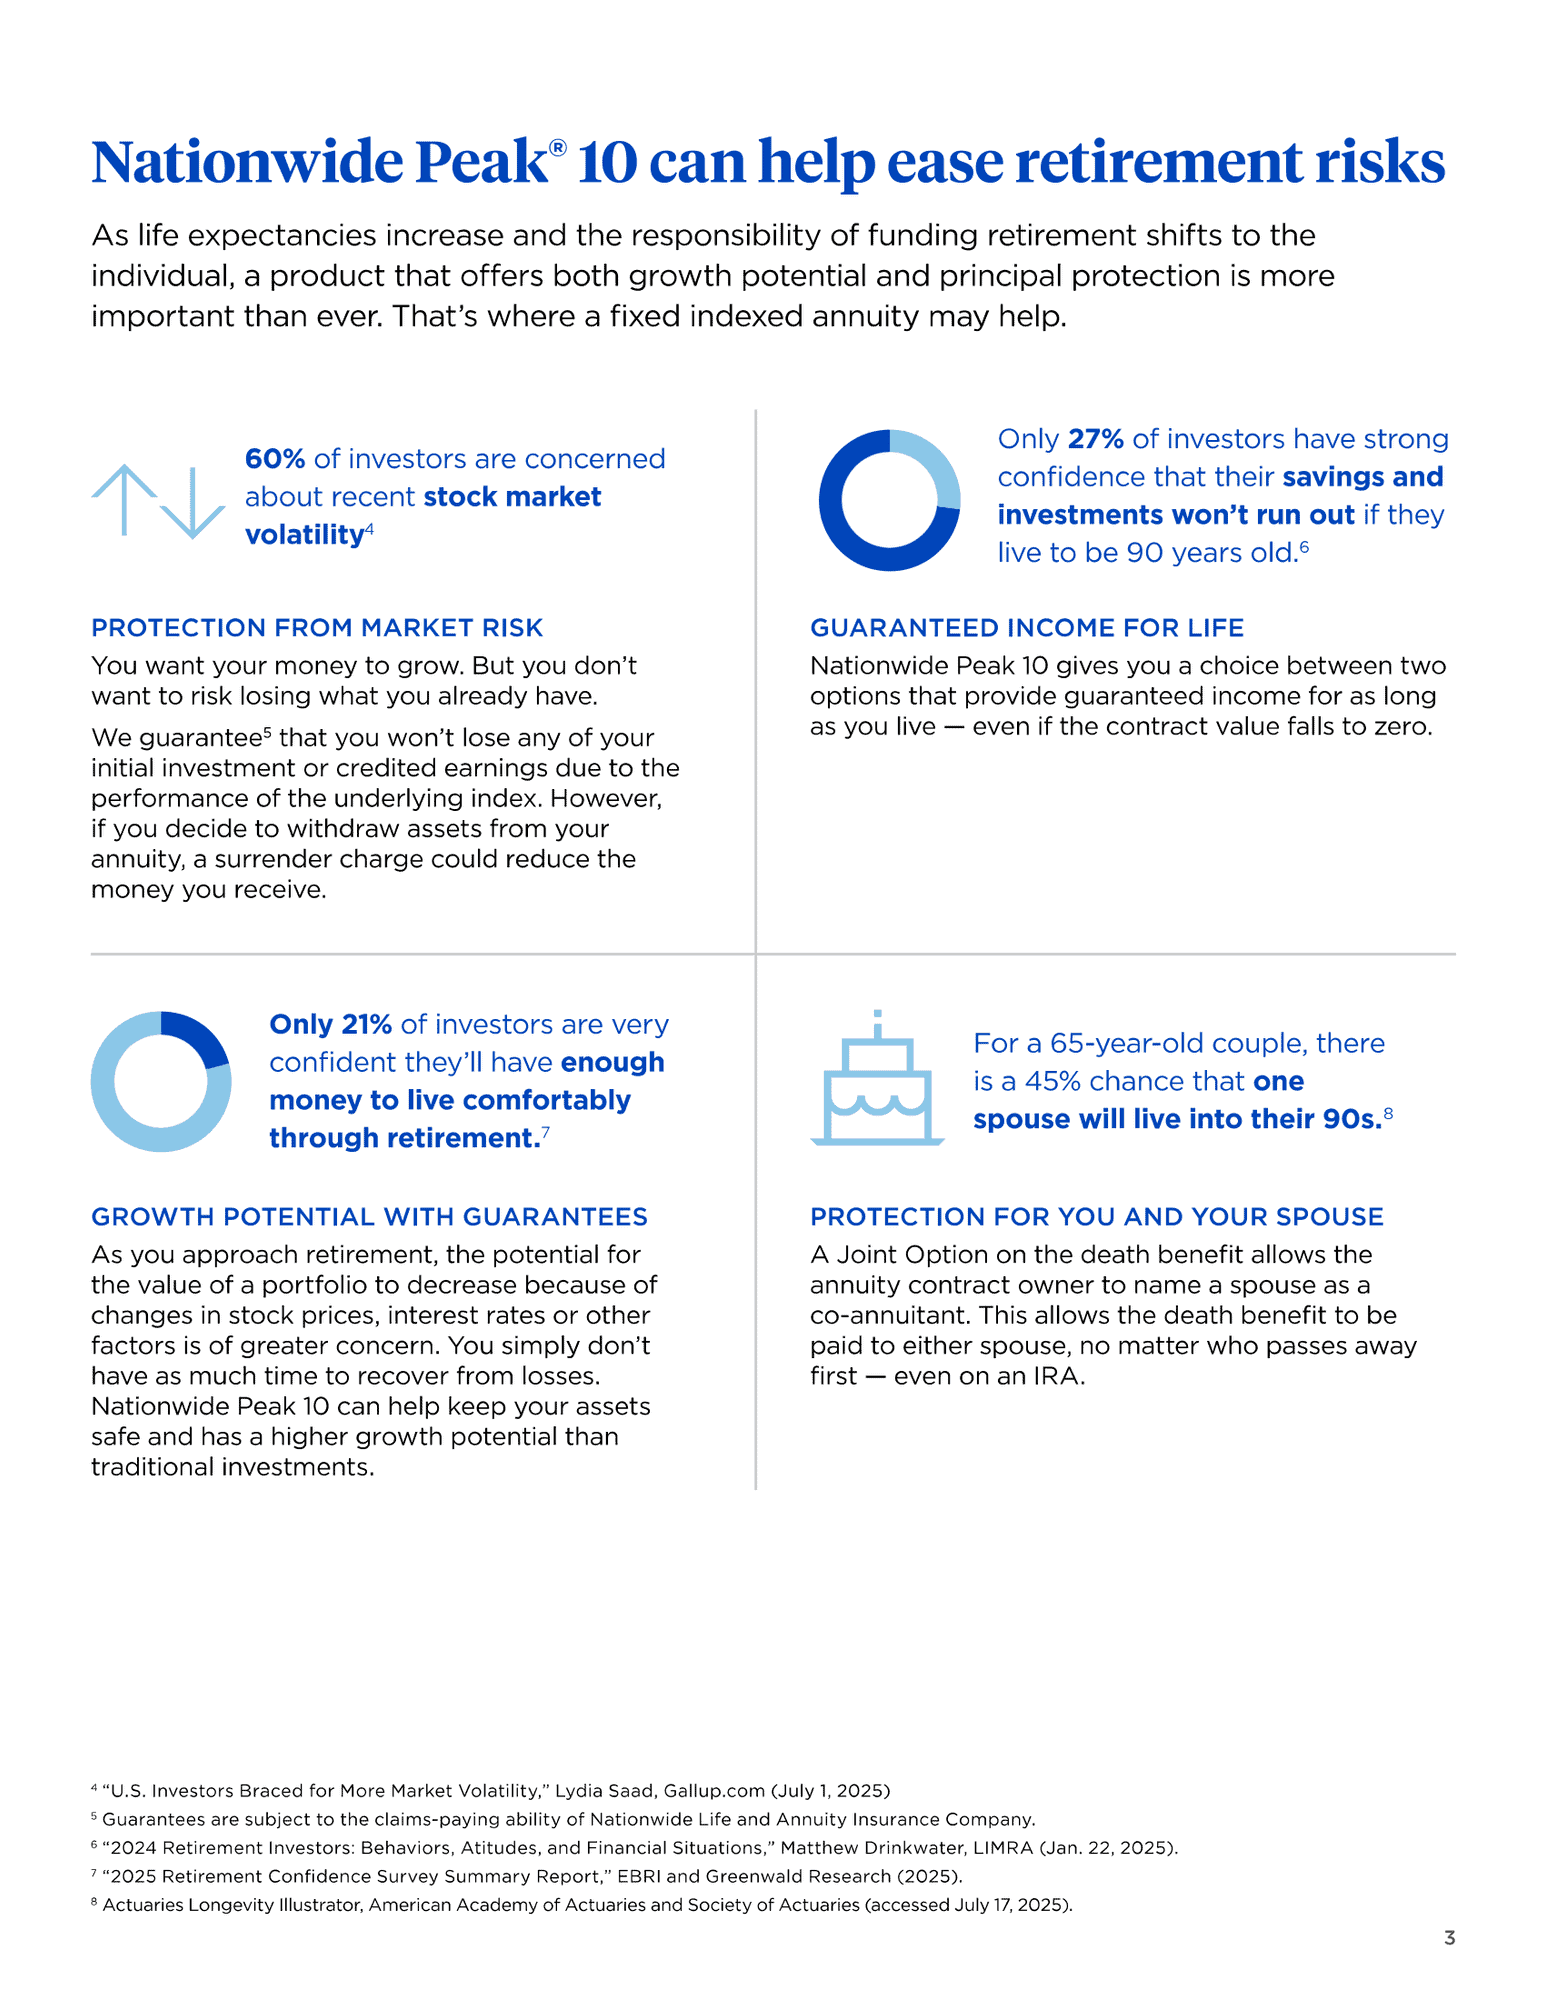
One strong option is the Nationwide Peak 10 Fixed Indexed Annuity.
How It Works
A fixed indexed annuity credits interest based on indexes like the S&P 500 while protecting the principal from market losses. When a Guaranteed Lifetime Withdrawal Benefit (GLWB) rider is added, couples can take lifetime withdrawals based on a separate income value.
Unlike traditional annuitization, the couple still owns the contract.
Why GLWBs Are Often Better for Couples
GLWB income payouts are typically higher than joint and survivor annuity payments because the contract remains invested instead of fully annuitized.
They also typically provide a lump-sum death benefit equal to the remaining account value, which traditional income annuities usually do not.
Pros
- Higher income potential than joint annuitization
- Lifetime income for both spouses
- Lump sum death benefit (remaining balance)
- Principal protection from market losses
- Couples retain control of the account value.
Cons
- Income riders reduce accumulation potential.
- Surrender charges apply during the early years.
- Income value is separate from account value.
Who Needs It
Couples approaching retirement who want the highest lifetime income and still want flexibility.
Who Does Not Need It
Investors seeking aggressive stock market growth.
The Best Annuity for Married Couples Who Want Guaranteed Survivor Benefits
Best option: Joint and Survivor Annuities
How It Works
A joint and survivor annuity pays income for as long as either spouse is alive. If one spouse dies, payments continue to the surviving spouse. Couples can choose the survivor percentage:
- 100% continuation
- 75% continuation
- 50% continuation
Higher survivor protection lowers the starting payment.
Pros
- Guaranteed lifetime income for both spouses
- Survivor income protection
- Simple pension structure
Cons
- Lower income than GLWB annuities
- Usually, there is no lump sum death benefit.
- Payments cannot usually be reversed.
Who Needs It
Couples who want the simplicity of a pension-style income stream.
Who Does Not Need It
Couples who want flexibility or death benefits for heirs.
The Best Annuity for Married Couples Who Want Spousal Continuance
Best option: Fixed Indexed Annuities with Spousal Continuance
Helpful Tip: If you need to look up the exact state laws, contract provisions, and IRS tax codes for this process, see our dedicated guide explaining how a spousal continuation annuity transfers ownership following a spouse’s passing.
How It Works
Many annuities allow a spousal continuance provision. If one spouse dies, the surviving spouse becomes the new contract owner and continues the annuity without triggering taxes or forcing liquidation.
This allows the surviving spouse to keep the annuity intact and continue the growth or income strategy.
Pros
- Allows the surviving spouse to maintain the annuity
- Avoids forced distributions at death
- Preserves tax deferral
Cons
- Only available when the spouse is the primary beneficiary
- Contract terms remain the same after death.
Who Needs It
Couples who want the surviving spouse to maintain full control of the annuity.
The Best Annuity Strategy for Couples With Unequal Life Expectancies
Best option: Separate annuities for each spouse
How It Works
Each spouse purchases an individual annuity designed for their own age and retirement timeline. The couple then uses life insurance to protect the surviving spouse.
This strategy often works well when:
- One spouse is significantly younger
- One spouse has health concerns.
- The couple wants a higher income.
Pros
- Each spouse receives income based on their own age.
- Higher potential payouts than joint structures
- Flexibility in retirement planning
Cons
- Requires more planning
- Two contracts instead of one
Who Needs It
Couples with large age differences or complex retirement planning needs.
The Best Annuity Strategy for Couples Using Life Insurance
Best option: Separate annuities combined with inexpensive life insurance
This strategy often produces higher retirement income and stronger survivor protection.
How It Works
1. Each spouse purchases their own annuity for retirement income.
2. A low-cost life insurance policy replaces income if one spouse dies early.
Because life insurance death benefits are typically tax-free, this strategy can protect the surviving spouse more efficiently than some annuity structures.
Pros
- Higher potential income
- Tax-free death benefit
- More flexible planning
Cons
- Requires underwriting for life insurance
- Multiple financial products to manage
Who Needs It
Couples focused on maximizing income while still protecting the surviving spouse.
Other Insurance Married Couples Should Consider
Annuities address income risk, but other insurance protects the broader retirement plan.
- Life insurance: Creates a tax-free inheritance and replaces lost income.
- Long-term care insurance: Protects retirement assets from nursing home expenses.
- Disability insurance: Protects income during working years.
Medicaid Planning Using an Annuity
Bottom Line
The best annuity strategies for married couples focus on income for both spouses and protection for the survivor. The strongest options are:
- Fixed indexed annuities with GLWB riders, like Nationwide Peak, for the highest income and a lump-sum death benefit
- Joint and survivor annuities for simple pension-style income
- Spousal continuance annuities to protect the surviving spouse
- Separate annuities combined with life insurance for maximum income and survivor protection
Each strategy solves a different retirement challenge couples face. Contact The Annuity Expert to compare the best annuities for married couples and receive free quotes for joint lifetime income strategies and survivor protection.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.