

What You Need To Know
Yes, you can have both a 403(b) and a 401(k) at the same time, but there are important rules and limits to consider:
- Contribution Limits: The combined contribution limit for both 403(b) and 401(k) accounts in 2026 is $24,500 if you’re under 50, $32,500 if you’re 50 or older, or $35,750 if you’re between ages 60 and 63 (including the catch-up contribution).
- Employer Contributions: Both plans allow for employer contributions, but the total combined contribution (employee + employer) cannot exceed $72,000 annually.
- Tax Considerations: Contributions to both 403(b) and 401(k) accounts are tax-deferred, which can lower your taxable income now but will be taxed when you withdraw the funds in retirement.
- RMDs: Required Minimum Distributions (RMDs) start at age 73 for both types of accounts, which means you’ll need to start withdrawing money and paying taxes on it by this age.
The Smart Order To Fund Both (So You Don’t Leave Money On The Table)
1) Capture Every Employer Match First (Both Plans)
Why: Free money beats everything. Get the full match in each plan before doing anything else.
- Who benefits: Employees with matches in both plans; anyone prioritizing guaranteed returns on contributions.
- Who doesn’t: Those with no match in one plan and very high fees in that plan.
- Pros: Immediate, risk-free return; accelerates savings rate.
- Cons: Small matches in a high-fee plan may drag long-term performance.
2) Max The Rest Of Your Shared Deferral In The Better Plan
Why: After matches, concentrate most remaining deferrals in the plan with lower fees, better funds, or Roth access, while keeping within the shared $24,500 (plus any catch-ups).
- Who benefits: Savers comparing costs/menus and optimizing taxes (Traditional vs. Roth).
- Who doesn’t: Those restricted by plan rules, low compensation, or tight cash flow.
- Pros: Lowers all-in costs; simplifies monitoring; potentially better after-tax outcome.
- Cons: Less diversification of plan features; may miss a smaller secondary match window.
3) Use Catch-Ups Correctly
Why: Maximize legal extra space.
- Age-50 catch-up: +$8,000 if the plan allows.
- 60–63 enhanced catch-up (SECURE 2.0): Up to $11,250 in 2026 if your plan allows.
- 403(b) 15-year service catch-up: Up to $3,000/year; lifetime $15,000; applied before the age-50 catch-up.
- Who benefits: Long-tenured 403(b) participants; late-career savers boosting contributions fast.
- Who doesn’t: Early-career workers without eligibility; plans that don’t offer catch-ups.
- Pros: Increases tax-advantaged space; can supercharge savings near retirement.
- Cons: Rules are technical; misordering can cause excess deferrals.
4) If You Also Have a 457(b), Double-Stack
Why: 457(b) deferrals are separate, letting many public-sector workers save far more in the same year.
- Who benefits: Government/eligible nonprofit employees offered 403(b) and 457(b).
- Who doesn’t: Private-sector workers without a 457(b).
- Pros: Dramatically higher tax-advantaged savings capacity.
- Cons: More accounts to manage; must track multiple distribution rules.
When Annuities Make Sense Here
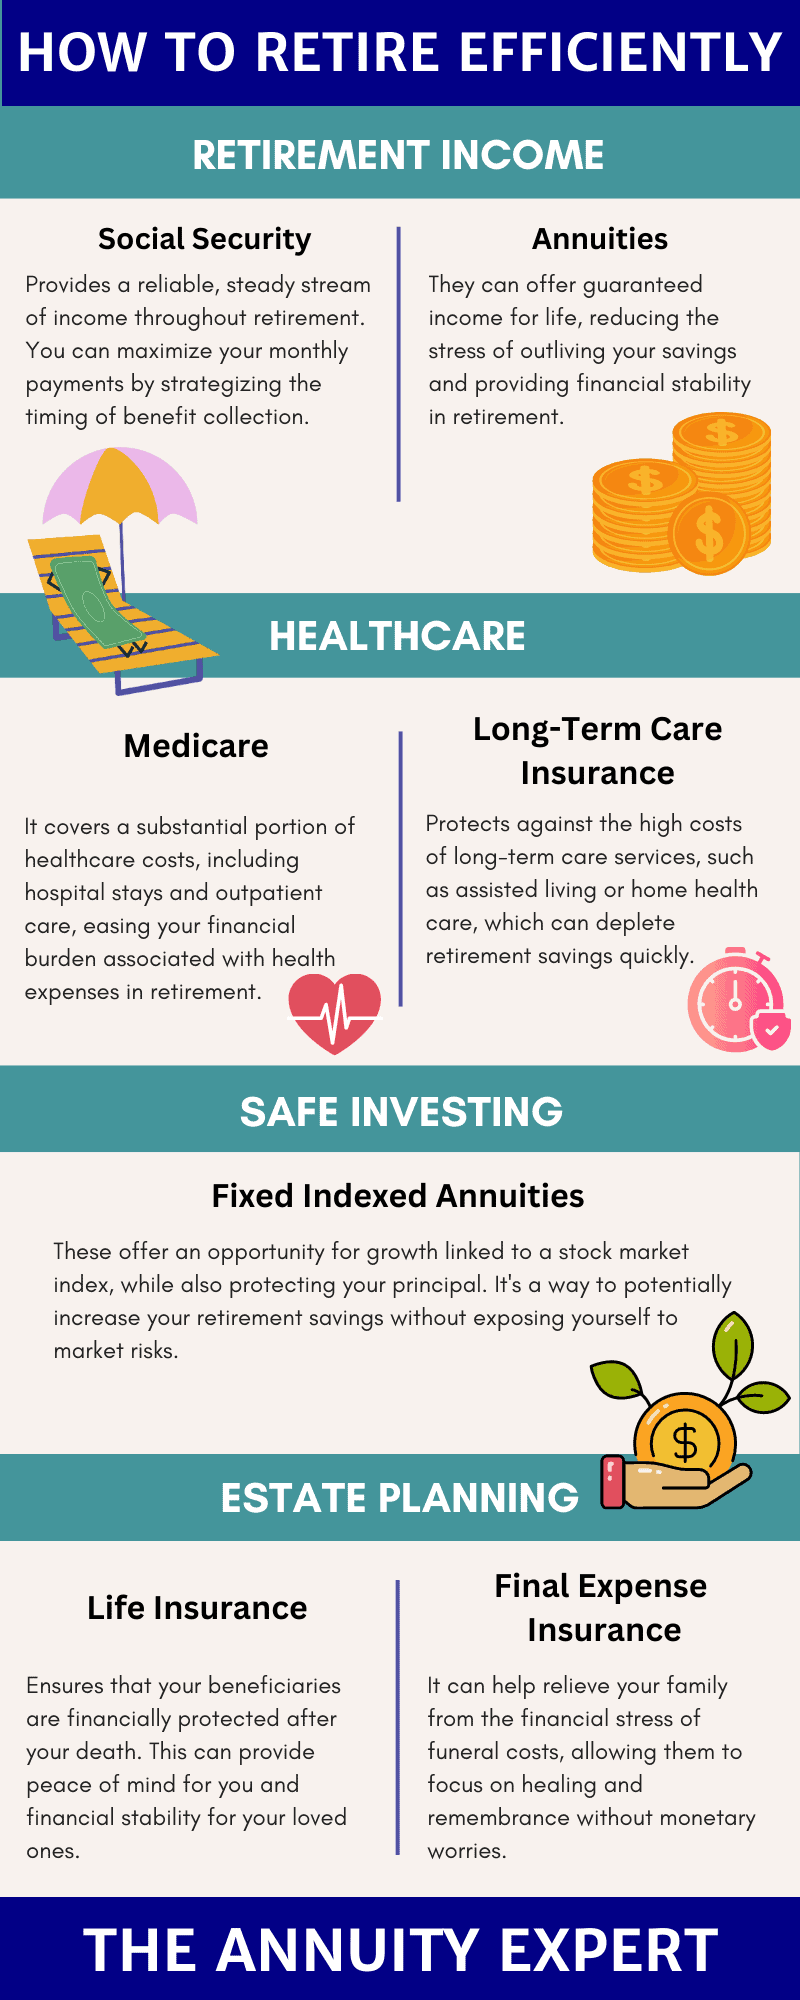
Inside many 403(b)s, annuity options may appear alongside mutual funds. For conservative savers close to retirement, fixed annuities or fixed index annuities can provide principal protection and predictable crediting. Some prefer to roll over to an IRA or to an annuity at retirement for lower costs or clearer income features. We can help you compare these paths.
- Pros: Can reduce sequence-of-returns risk; creates predictable income options.
- Cons: Product variability; surrender schedules; not all contracts are competitively priced.
- Who benefits: Near-retirees prioritizing stability; teachers/health-system staff facing limited 403(b) menus; anyone planning a rollover for income.
- Who doesn’t: Long-horizon investors are comfortable with market risk and low-cost index funds.
How We Help
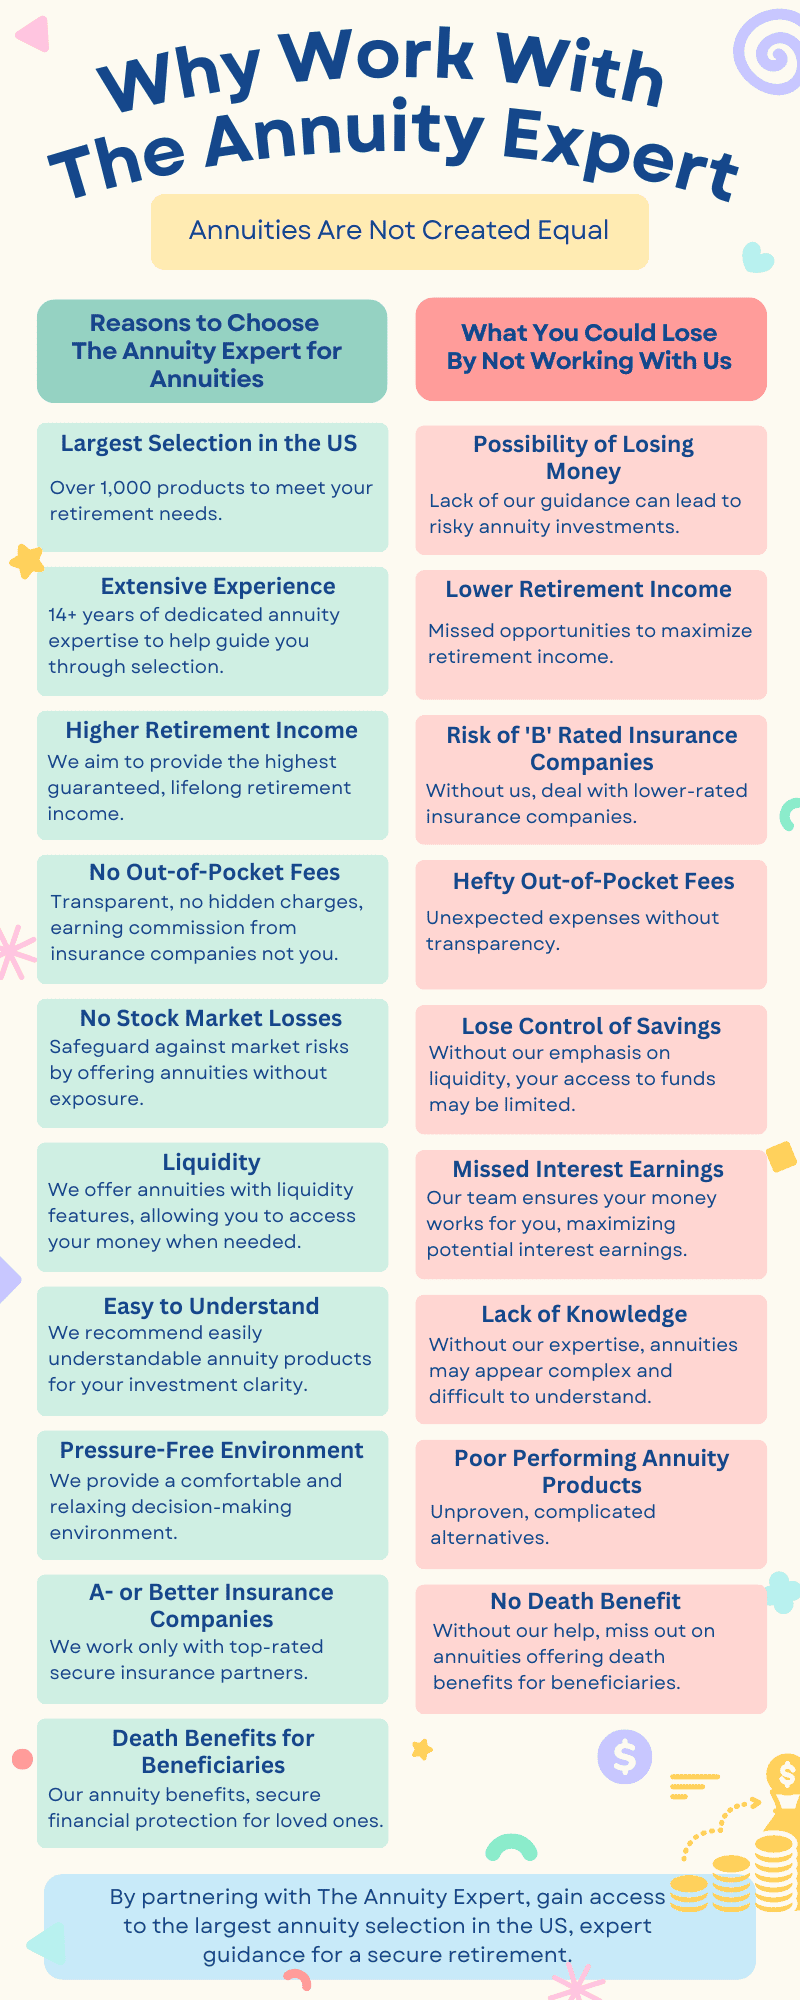
At The Annuity Expert, we’re an independent retirement planner. We compare 401(k)/403(b)/457 funding strategies, plan fees, and rollover options—then price out annuities and insurance only when they truly improve your outcome. Bring your plan details, and we’ll map the clearest path to maximize matches, minimize fees, and lock in the right level of protection.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.