

Understanding the Two Ways to Access Income From Annuities
What Are Annuity Payments (Annuitization)?
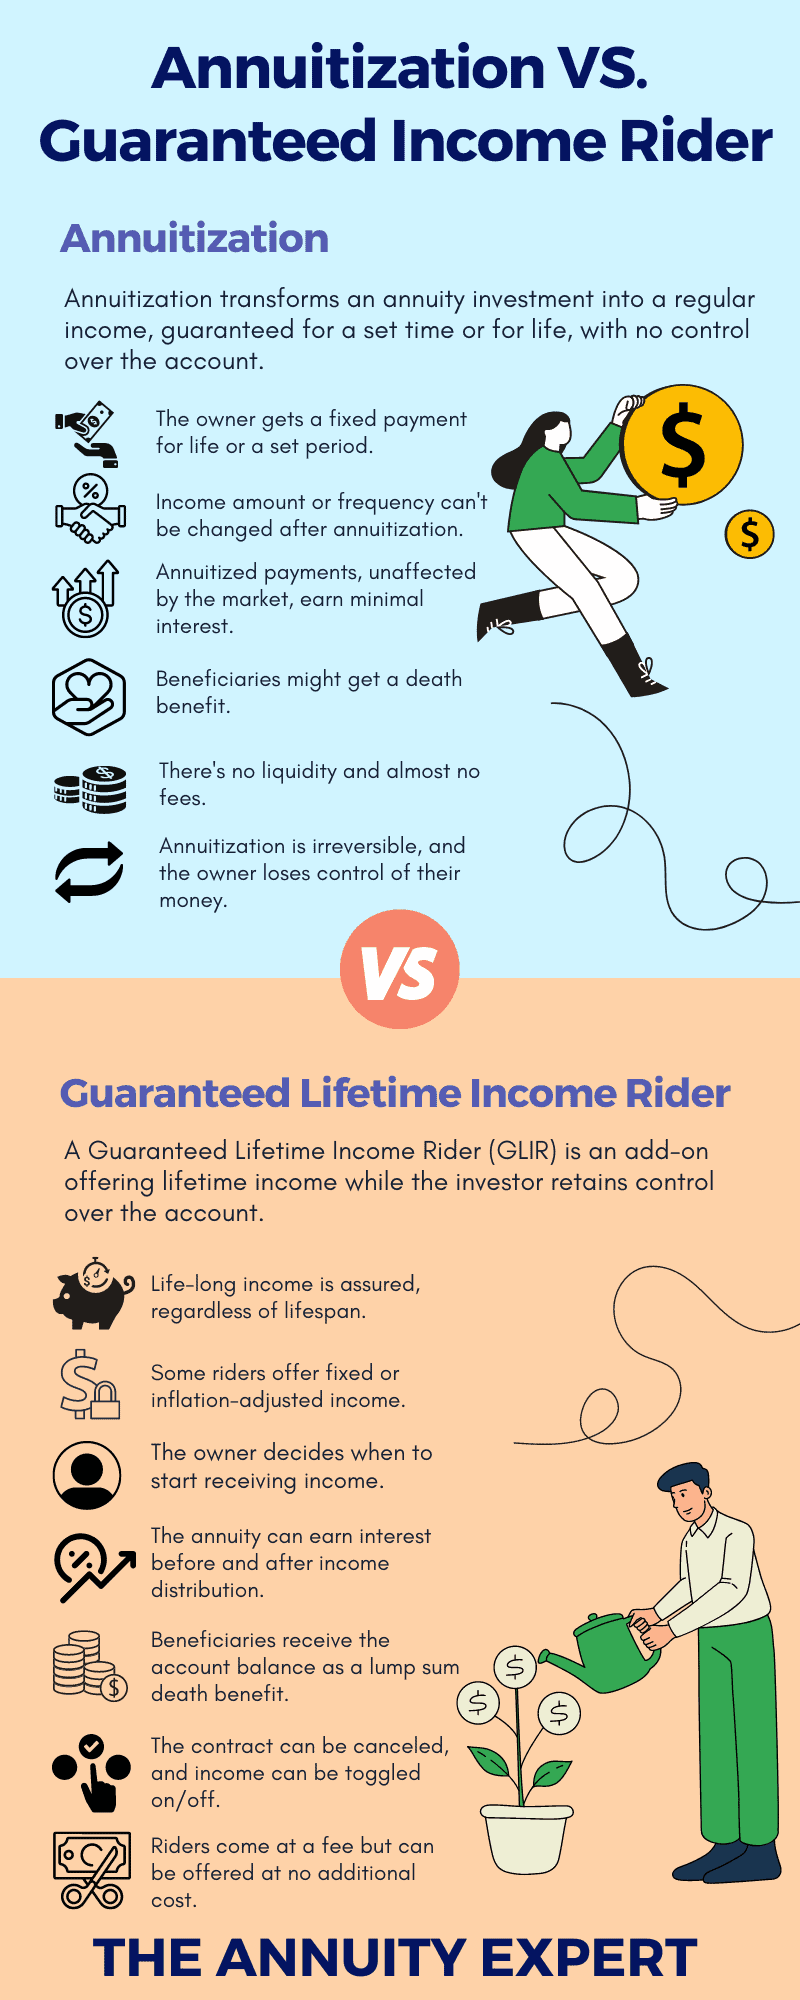
Annuitization is the irrevocable process of converting the annuity contract’s accumulation value into a guaranteed income stream, usually for life or a set period.
- How It Works: You give up access to your lump sum in exchange for a guaranteed monthly payment for the rest of your life or for a certain term (e.g., 10 or 20 years). You can also elect “life with period certain” or “joint life” options, which offer protections for spouses or beneficiaries.
- Pros:
- Higher payouts initially compared to income riders (because the insurer takes full control over the contract value).
- Simple structure—you don’t have to worry about market volatility.
- Medicaid-compliant for certain long-term care planning strategies.
- Cons:
- Irreversible—once you annuitize, you can’t take it back or access your account value.
- No liquidity—you can’t take extra withdrawals in an emergency.
- Death benefits are limited unless you choose a refund or period certain option.
- No control over remaining funds—your beneficiaries may receive little or nothing.
- Who Needs It:
- Early retirees under 59½ looking for a Medicaid-compliant payout with a non-qualified annuity, avoiding IRS penalties.
- Retirees who don’t need access to the principal and want maximum lifetime income.
- People with no heirs or estate planning needs.
- Who Doesn’t Need It:
- Anyone who values flexibility, legacy planning, or access to their money.
- Retirees wanting to preserve control and pass assets to family.
What Are Lifetime Withdrawals (Using Income Riders like GLWBs)?
Lifetime withdrawals allow you to withdraw a guaranteed amount of income for life without giving up ownership or control of your annuity’s value. This is usually done through a guaranteed lifetime withdrawal benefit (GLWB) rider.
- How It Works: You pay a small fee (or use a no-fee version), and in return, the insurer guarantees a lifetime income based on a protected “benefit base,” even if the account value hits $0. You still own the annuity and can access funds (subject to contract terms).
- Pros:
- Full control of account value.
- Death benefit passes to heirs.
- Revocable—you can stop withdrawals or change strategies.
- Spousal continuation is often built in.
- Income continues even if the account is depleted.
- Cons:
- Payouts are usually lower than annuitization at the start.
- Fees may apply, especially with performance-based riders.
- Income may not rise with inflation unless an inflation-adjusted rider is selected.
- Renewal rates and growth potential depend on carrier discretion.
- Who Needs It:
- Retirees looking for lifetime income with flexibility.
- Those who want to leave a death benefit.
- People unsure about committing their money permanently.
- Individuals who want income but not annuitization.
- Who Doesn’t Need It:
- Someone seeking maximum immediate payout and doesn’t care about legacy or control.
- People with very short life expectancies and no beneficiaries.
Which Is Better: Annuitization or Lifetime Withdrawals?
| Feature | Annuitization | Lifetime Withdrawals (GLWB) |
|---|---|---|
| Reversible? | No | Yes (you can stop at any time) |
| Liquidity | None | Partial (subject to contract rules) |
| Death Benefit | Limited or none | Full account value goes to heirs |
| Initial Payouts | Typically higher | Lower, but with control |
| Best Use Case | Medicaid spend-down, early retirement | Flexible income planning in retirement |
| Control Over Account | Lost upon annuitization | Retained |
Other Insurance to Consider
- Life Insurance: If you choose annuitization, consider buying permanent life insurance to replenish your estate or provide legacy benefits, especially since annuitization usually ends the account value at death.
- Long-Term Care Insurance: If you’re using lifetime withdrawals from an FIA or VA, some products offer long-term care riders, or you can pair it with standalone LTC coverage for broader protection.
- Deferred Fixed Annuity (MYGA or FIA): You can grow your funds before converting to income. FIAs offer index-linked growth and can be paired with a GLWB for future guaranteed income.
What Types of Accounts Can Fund Each Strategy?
Both annuitization and GLWB withdrawals can be funded from:
- IRA or Roth IRA
- 401(k), 403(b), or other qualified plans (via rollover)
- Non-qualified brokerage or savings accounts
Note: Roth IRAs offer tax-free income, while traditional IRAs and other pre-tax accounts result in taxable income upon withdrawal.
Bottom Line
Choosing between annuitization and lifetime withdrawals is one of the most important income decisions you’ll make. If you need maximum income and don’t care about flexibility, annuitization may suit you. But if you want control, flexibility, and the ability to leave a legacy, a GLWB is usually the smarter, safer option.
Compare both options before you commit. Always start with your goals, not just payout figures.
Get Help From a Retirement Income Specialist
Need help deciding which option works for your situation? Contact The Annuity Expert today for free quotes and a personalized plan. We’ll help you compare annuity income options and find the best product based on your goals, funding source, and income needs.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.