

American Equity EstateShield 10 Annuity Review
The American Equity EstateShield 10 is a fixed indexed annuity built around three goals: future lifetime income, a temporary income increase after certain health events, and an enhanced death benefit for beneficiaries.
The product uses a separate Benefits Account Value, or BAV, to calculate its lifetime-income and enhanced-death-benefit features. The BAV receives a first-year bonus and can grow when interest is credited to the underlying contract, but it is not the same as the contract value or cash surrender value.
Our Professional Opinion on the American Equity EstateShield 10 Annuity
We generally do not recommend the American Equity EstateShield 10 when the buyer’s primary goal is predictable guaranteed lifetime income in the future.
The problem is the income-rider design. You must wait until after the tenth contract anniversary before lifetime income can begin, and the Benefits Account Value grows partly through a multiplier applied to the interest actually earned by the annuity.
That makes the future income more performance-based than we prefer. If the contract earns less interest than expected during the first decade, the BAV and future income can also be lower than expected.
We would rather use a fixed indexed annuity with a contractually guaranteed income-base roll-up. A guaranteed roll-up tells us how the income calculation value will grow each year regardless of whether the index strategies perform well or poorly.
EstateShield 10 does include the lifetime-income rider and enhanced death benefit without a separate rider charge. That sounds great, but the absence of a stated rider fee does not mean the benefits are free.
The cost is built into the overall product economics. The buyer accepts a long waiting period, performance-based BAV growth, and weaker accumulation potential than we would expect from an annuity designed strictly for growth.
The accumulation potential stinks on the traditional strategies. Based on the supplied rate sheet, the true S&P 500 and fixed-account options are not competitive enough for us to recommend EstateShield as an accumulation annuity.
The proprietary index options may show larger headline participation rates, but those indexes use volatility controls, excess-return calculations, cash components, or other engineered rules. A larger participation rate on an engineered index cannot be compared directly with the same participation rate on the true S&P 500.
The fixed-interest strategy can also reset after its initial guarantee period. It is not a substitute for a multi-year guaranteed annuity when the buyer wants a fixed rate locked for several years.
Where we do like EstateShield 10 is as a niche legacy-planning annuity. The BAV bonus, interest multiplier, and enhanced death-benefit choices can create a larger inheritance than the standard contract value alone.
The catch is how the enhanced death benefit is paid. Beneficiaries can receive a reduced portion of the BAV as a lump sum or receive the full applicable BAV through equal payments over five years, subject to the contract limits.
That can still be valuable, especially for someone who cannot qualify for traditional life insurance or wants to reposition retirement assets for beneficiaries. However, the buyer and beneficiaries need to understand that the largest illustrated BAV is not unrestricted cash available immediately at death.
The Wellbeing Benefit is also useful but limited. It can temporarily increase lifetime income after the ten-year waiting period when the owner or spouse meets the activities-of-daily-living requirements. The enhancement is available for a defined period and requires the contract value to remain above zero.
This is not a substitute for actual long-term care insurance. It is a temporary annuity-income enhancement with specific waiting periods, health requirements, and account-value conditions.
Our opinion comes down to the job you are asking the annuity to perform. For future lifetime income, we would normally choose a guaranteed roll-up product with a competitive payout. For pure accumulation, we would choose a stronger accumulation FIA. For an enhanced legacy benefit, EstateShield 10 can be worth comparing.
Compare EstateShield 10 With Today’s Best Fixed Indexed Annuities
EstateShield 10 tries to combine income, health-related income enhancement, and legacy benefits inside one contract. That can be useful, but it also means the product may not be the best at any single job.
What We Like
- Enhanced Death Benefit: Beneficiaries may receive an amount based on the BAV instead of only the standard contract value.
- First-Year BAV Bonus: Eligible first-year premiums receive an immediate increase for purposes of calculating the income and legacy benefits.
- BAV Interest Multiplier: Positive interest credited to the contract receives an additional multiplier when applied to the BAV.
- No Separate Rider Fee: The lifetime-income, Wellbeing, and enhanced-death-benefit features are built into the product.
- Joint Lifetime Income: Payments can be structured to continue for the surviving spouse under the rider provisions.
- Income Start-and-Stop Flexibility: Lifetime withdrawals can generally be stopped and restarted without traditional annuitization.
- Wellbeing Benefit: Qualifying health conditions can temporarily increase lifetime income after the waiting period.
- True S&P 500 Option: The product includes a traditional S&P 500 strategy in addition to engineered indexes.
- Principal Protection: Negative index performance does not directly reduce the contract value.
- Nursing Home and Terminal Illness Access: The no-fee Enhanced Benefit Rider can provide additional access to contract value for qualifying events.
- Strong Insurance Company: American Equity meets our A- or better financial-strength requirement.
What We Don’t Like
- Ten-Year Income Wait: Lifetime withdrawals cannot begin until after the tenth contract anniversary.
- Performance-Based Future Income: BAV growth depends partly on the interest actually credited to the contract.
- No Guaranteed Roll-Up: The BAV does not grow through the type of fixed contractual income-base roll-up we prefer for deferred income planning.
- Weak Traditional-Index Growth: The true S&P 500 and fixed-account terms are not competitive enough for us to use this as an accumulation annuity.
- Engineered Index Reliance: Much of the stronger-looking upside is attached to proprietary or volatility-controlled indexes.
- BAV Is Not Cash: The Benefits Account Value cannot simply be surrendered or withdrawn in a lump sum.
- Reduced Lump-Sum Legacy Option: Beneficiaries generally must accept payments over time to receive the full applicable enhanced death benefit.
- Wellbeing Benefit Has Conditions: The enhancement requires the waiting period, qualifying health conditions, and a contract value above zero.
- No First-Year Free Withdrawal: Standard penalty-free access to accumulation value begins after the first contract year.
- Long Surrender Period: The contract has a ten-year surrender schedule and an MVA.
- No Return-of-Premium Feature: The buyer cannot assume the original premium will be available during the surrender period.
Our bottom line: EstateShield 10 is not one of our first choices for future guaranteed lifetime income because the buyer waits ten years and the income benefit depends too heavily on contract performance. The growth potential is not great either. Its best use is as a niche enhanced-death-benefit annuity for someone who understands the beneficiary payout rules.
American Equity EstateShield 10 Product Details
| Product Type | Modified Single Premium Deferred Fixed Indexed Annuity |
| Primary Purpose | Future Lifetime Income and Enhanced Legacy Benefits |
| Surrender Period | 10 Years |
| Issue Ages | Generally ages 40 through 75 |
| Premium Funding | Initial premium plus eligible additions during the first contract year |
| Lifetime Income Rider | Built in with no separate rider fee |
| Income Start | After the tenth contract anniversary under the rider provisions |
| Income Options | Single or joint lifetime withdrawals |
| Enhanced Death Benefit | Based on the applicable BAV, with lump-sum and multi-year payout choices |
| Wellbeing Benefit | Temporary enhanced income for qualifying ADL limitations after the waiting period |
| Free Withdrawals | Annual penalty-free access beginning after the first contract year |
| Market Value Adjustment | Yes |
| Return of Premium | No |
| Index Choices | Traditional S&P 500 plus proprietary and volatility-controlled strategies |
American Equity is a good annuity company. Current product materials list A financial-strength ratings from AM Best, Fitch, and Standard & Poor’s. That comfortably exceeds our A- minimum for an annuity recommendation. Our concerns with EstateShield 10 are about the performance-based income design, weak accumulation potential, long waiting period, and beneficiary payout rules—not the financial strength of the insurer.
How EstateShield 10 Works
EstateShield 10 tracks two primary values:
- Contract Value: The actual account value used for withdrawals, surrender, the standard death benefit, and other contract calculations.
- Benefits Account Value: A separate benefit-base value used to calculate lifetime income and the enhanced death benefit.
Eligible premium paid during the first contract year receives a BAV bonus. When the contract receives positive interest, the BAV receives an enhanced credit based on the contract’s multiplier.
The BAV is a measuring value, not cash. A BAV that is larger than the contract value does not mean the owner can surrender the annuity and receive that amount.
Lifetime Income Benefit
The built-in Lifetime Income Benefit Rider can provide guaranteed lifetime withdrawals without requiring traditional annuitization.
Lifetime income cannot begin until the required ten-year deferral period has been completed. The payout is based on the applicable BAV, the age when income begins, whether income covers one or two lives, and the contract’s payout factor.
The payment may increase after positive interest is credited and the BAV grows. However, those increases are not guaranteed because they depend on future contract performance.
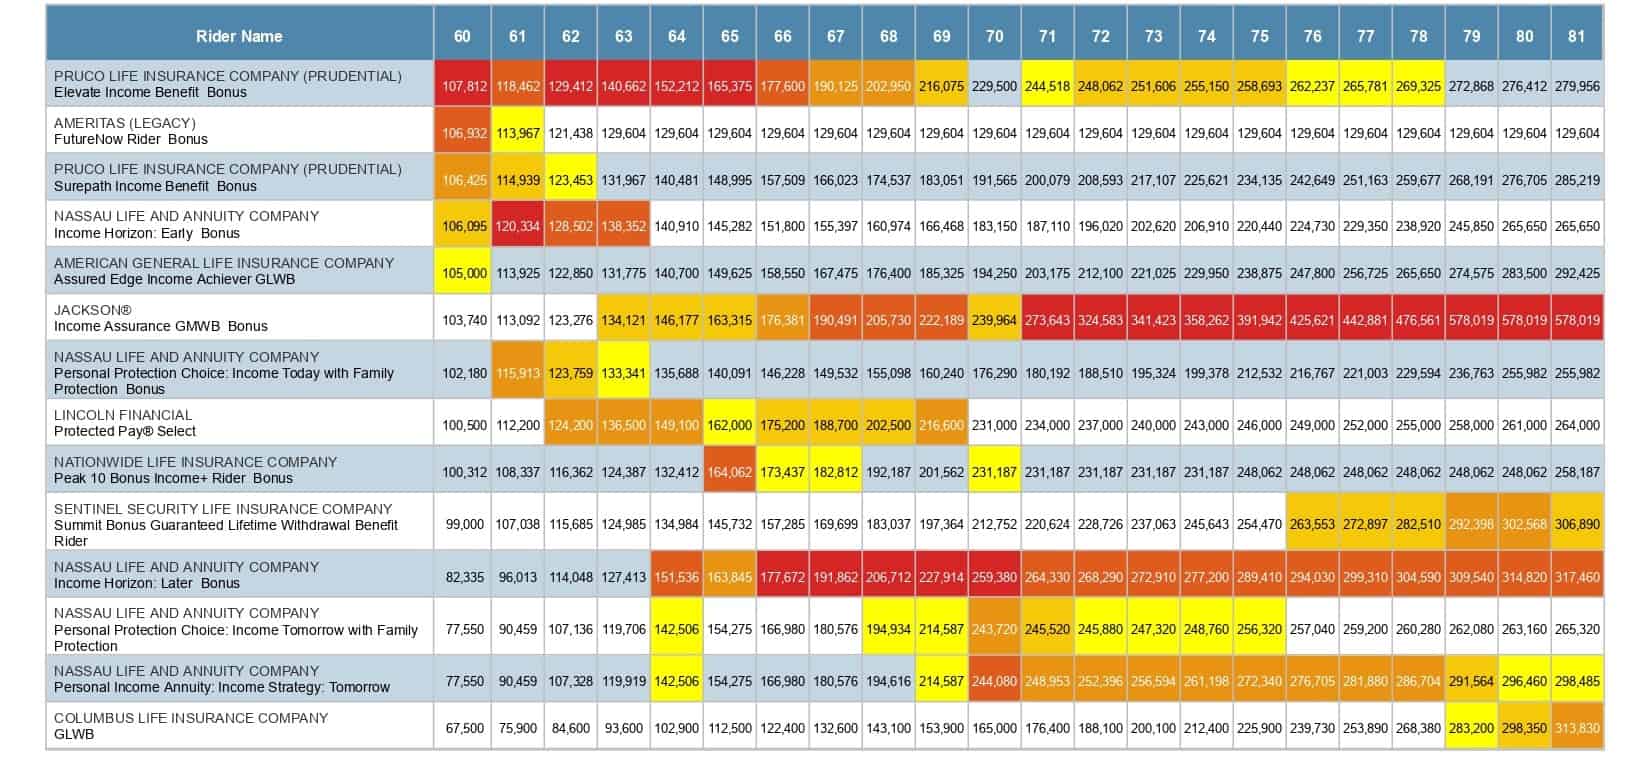
Compare EstateShield 10 Income Payouts
Do not buy EstateShield 10 because the BAV illustration looks large. Compare the actual guaranteed annual income against annuities with contractual roll-ups from A- or better-rated insurers.
Contact us for a custom income heat map based on your age, state, premium, single- or joint-life needs, and desired income start date.
Wellbeing Benefit
The Wellbeing Benefit can temporarily increase the lifetime-income payment when the owner or spouse is unable to perform at least two of the six activities of daily living and satisfies the rider requirements.
The enhancement is available only after the ten-year waiting period, lasts for a defined number of years, and requires the contract value to remain above zero.
This benefit can help with increased expenses after a health event, but it does not reimburse actual care costs and should not be treated as comprehensive long-term care coverage.
Enhanced Death Benefit
Beneficiaries may elect the enhanced death benefit in place of the base contract death benefit.
The lump-sum option generally pays a reduced portion of the applicable BAV. The multi-year option can pay the full applicable enhanced benefit through equal payments over five years, subject to the contract’s maximum-benefit limits.
This is the feature we find most compelling. Someone focused on inheritance should compare EstateShield 10 with the best annuities for enhanced death benefits before purchasing.
High-net-worth retirees who do not need their required distributions for living expenses should also compare broader annuity strategies for high-net-worth households, including the use of RMDs to fund life insurance or long-term care coverage.
Index-Crediting Strategies and Growth Potential
EstateShield 10 offers a fixed-interest strategy, traditional S&P 500 crediting methods, and proprietary strategies linked to BlackRock and the S&P Dividend Aristocrats.
The available crediting methods include annual and two-year point-to-point strategies, monthly strategies, caps, and participation rates.
We generally prefer one-year strategies and transparent traditional indexes when the economics are competitive. The current traditional-index and fixed-account terms are weak, which is why we would not buy EstateShield for accumulation.
If protected growth is the goal, compare the current contract with annuities designed to reduce renewal-rate risk through cap locks, rate guarantees, or MYGA structures.
Liquidity, Surrender Charges, and MVA
EstateShield 10 has a ten-year surrender-charge period. Standard free withdrawals begin after the first contract year.
Withdrawals above the free amount can be subject to surrender charges and a Market Value Adjustment. The MVA can increase or reduce the surrender value based on changes in interest rates.
The no-fee Enhanced Benefit Rider can provide additional access after the first year for qualifying nursing-home confinement or terminal illness.
Retirement Accounts Accepted
Who Should Consider EstateShield 10?
- Someone Focused on Leaving a Legacy: The enhanced death benefit is more important than maximizing cash-value growth.
- Someone Who Can Wait at Least Ten Years: You do not need lifetime income during the first decade.
- Someone Comfortable With Performance-Based Growth: You understand that future BAV growth depends partly on interest credited to the contract.
- Someone Who Cannot Qualify for Life Insurance: The enhanced death benefit may provide an alternative way to leave additional money to beneficiaries.
- Someone Whose Beneficiaries Can Accept Payments Over Time: Receiving the full applicable enhanced benefit generally requires a multi-year payout.
Who Should Probably Buy Something Else?
- Someone Seeking the Most Predictable Future Income: We prefer a contractual guaranteed roll-up GLWB.
- Someone Starting Income Within Ten Years: EstateShield does not allow rider income during the required deferral period.
- Someone Seeking Maximum Safe Growth: The current accumulation terms are not competitive enough.
- Someone Needing Strong Liquidity: The contract has no standard first-year free withdrawal and a long surrender schedule.
- Someone Wanting a Simple Lump-Sum Legacy: The full enhanced benefit generally requires payments over time.
- Someone Needing Return-of-Premium Protection: The contract does not provide a contractual return-of-premium feature.
What We Recommend
We would not use EstateShield 10 as our first choice for deferred guaranteed lifetime income. The ten-year wait and performance-based BAV growth create too much uncertainty compared with a guaranteed roll-up income rider.
We would also skip it for pure accumulation because the current growth potential is not great.
EstateShield 10 deserves consideration when the primary goal is an enhanced legacy benefit and the buyer understands the BAV, beneficiary payout options, Wellbeing Benefit limitations, and long surrender period.
Contact The Annuity Expert for free quotes and a no-obligation comparison of EstateShield 10 against guaranteed-roll-up income annuities and other enhanced-death-benefit strategies.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.