

Annuity.org looks like an annuity brokerage, but its own disclosures show that its business model is very different from working directly with an annuity professional.
If you’re planning for retirement and searching online for annuity rates or quotes, there is a good chance you’ll come across Annuity.org. The website is polished, ranks prominently in search results, publishes hundreds of educational articles, and offers calculators, rate tables, and opportunities to request annuity quotes.
At first glance, you might assume you’re dealing directly with an annuity brokerage or retirement-planning firm.
That’s where consumers need to understand the distinction.
Annuity.org is a licensed insurance agency, but Annuity.org itself states that it does not sell annuities or insurance products directly. Instead, consumers interested in purchasing an annuity are connected with outside insurance agents and financial professionals through its partner network.
That doesn’t automatically mean Annuity.org is illegitimate. But it does mean its business model is substantially different from calling an independent annuity broker who personally researches products, prepares quotes, recommends contracts, and remains responsible for servicing the relationship afterward.
And that distinction matters when you’re potentially moving $100,000, $500,000 or even $1 million or more of your retirement savings.
Annuity.org: A Lead Generation Site, Not a Broker
Annuity.org is one of the digital brands operated by Launch That, an Orlando-based digital marketing company.
Launch That describes itself as a company that develops digital brands in financial, legal, and medical markets. Its services and expertise include search engine optimization, paid advertising, content creation, conversion optimization, and lead generation. Annuity.org is specifically listed as one of its brands.
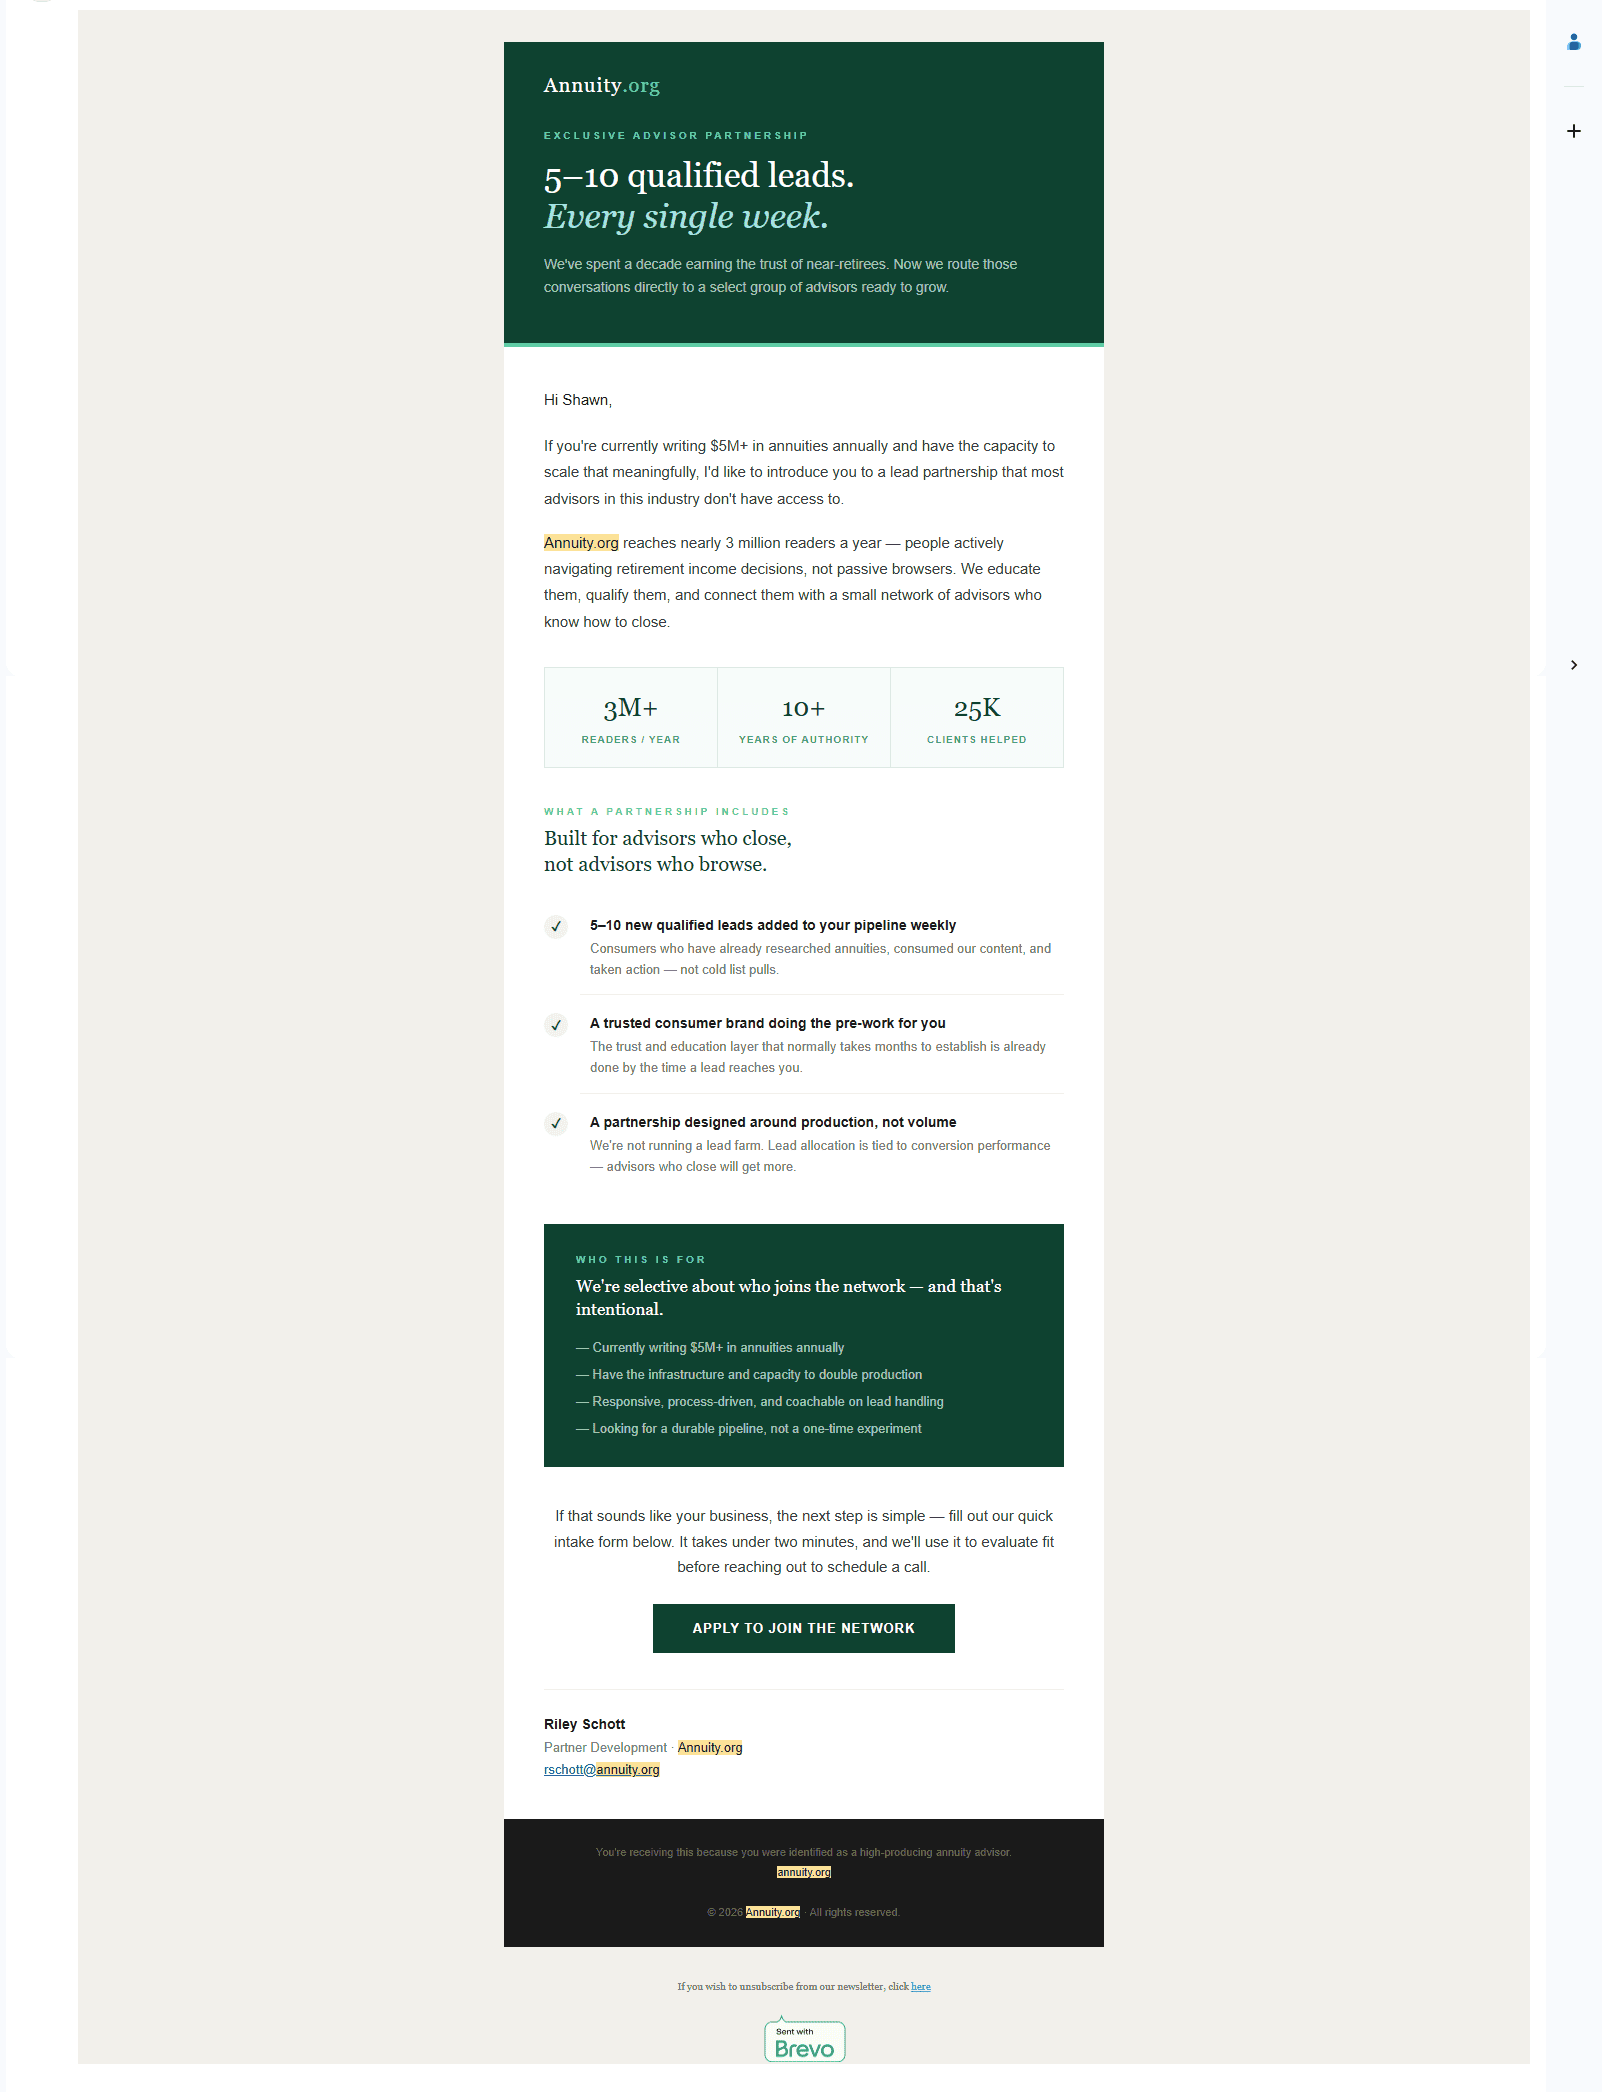
Launch That is remarkably direct about how the model works. It says it builds digital brands and marketing campaigns that generate leads and customers for outside service providers. Annuity.org’s own partnership page goes even further, explaining that its business model can include cost-per-click, cost-per-lead, and cost-per-acquisition arrangements and stating that one of its goals is generating qualified annuity leads for its partners.
That is a much better description of what consumers need to understand:
Annuity.org is an educational and lead-generation platform that also holds insurance-agency licenses. It is not the same thing as working directly with the annuity agent or broker who will ultimately sell and service your contract.
What Happens When You Request an Annuity Quote?
This is probably the most important issue for consumers.
You may believe you’re submitting information so Annuity.org can shop annuity companies and personally provide your quote.
According to Annuity.org’s own disclosures, however, Annuity.org does not sell the annuity. Instead, it connects interested consumers with outside professionals.
Its privacy policy is even more specific.
Annuity.org states that when consumers request information about annuities or insurance, their information can be shared with nonaffiliated businesses within its partner network. The policy also states that, in some circumstances, Annuity.org may sell information to a nonaffiliated partner in order to fulfill a consumer’s request. Those partners may subsequently contact the consumer by phone, email, or mail.
That’s something you should know before submitting your name, phone number, email address, age, investment amount, or other financial information.
You’re not necessarily requesting a quote directly from the person or organization that will ultimately sell you the annuity.
Why The Agent-Matching Model Can Be a Problem
Annuity.org says it carefully selects partners and works with licensed agents. That’s an important clarification, and consumers shouldn’t be told otherwise.
The issue is different.
You didn’t independently select the agent.
When you’re working with a substantial portion of your retirement savings, you should know exactly who is advising you before handing over your financial information.
Ask questions such as:
- How many years has this person actually sold annuities?
- How many insurance companies can they represent?
- Do they specialize in fixed annuities, indexed annuities and retirement income?
- Can they compare multiple carriers?
- How are they compensated?
- Are they recommending this product because it’s best for you or because it’s the product available through their particular distribution relationship?
- Who services your contract five or ten years from now?
- What happens if the agent leaves the business?
Being licensed is important, but having an insurance license does not automatically make someone an annuity expert.
Annuities can involve hundreds of contract variations involving surrender schedules, income riders, participation rates, caps, spreads, bonuses, market value adjustments, simple versus compound interest, death benefits, long-term care benefits and withdrawal provisions.
Experience matters.
You’re entering a matching system.
A Visit to Annuity.org’s “Office” Reveals the Truth
While visiting friends from UCF, I personally stopped by the Launch That office in downtown Orlando, which is the parent company behind Annuity.org. It confirmed everything we’re warning you about:
- There was no retirement planning firm.
- There was no team of annuity advisors or licensed brokers.
- It’s a digital marketing agency, not a place where you can sit down with a financial professional to discuss your retirement.
In other words, there’s no way to meet with someone in person to discuss your financial goals. They are not a local annuity brokerage that sells annuities directly to consumers, and no actual quotes or personalized recommendations are offered through the site.
Writers Without Financial Expertise
The articles and “educational resources” are written by freelance content creators with little to no field experience, not financial professionals. These writers are often assigned articles by editors with SEO goals in mind—not retirement planning knowledge.
You may be getting content that’s optimized to rank on Google—but it’s not written by someone who doesn’t sell annuities regularly, build a retirement income plan, or be licensed to do so. Check out their LinkedIn profiles for proof:
- Christian Simmons – writer at DrugWatch
- Jennifer Schell – Content Writer at Launch That
- Terry Turner – Senior Medical Writer at DrugWatch?
The list goes on and on, and where’s your info going to?
The Bigger Concern: How Annuity Rates Are Presented
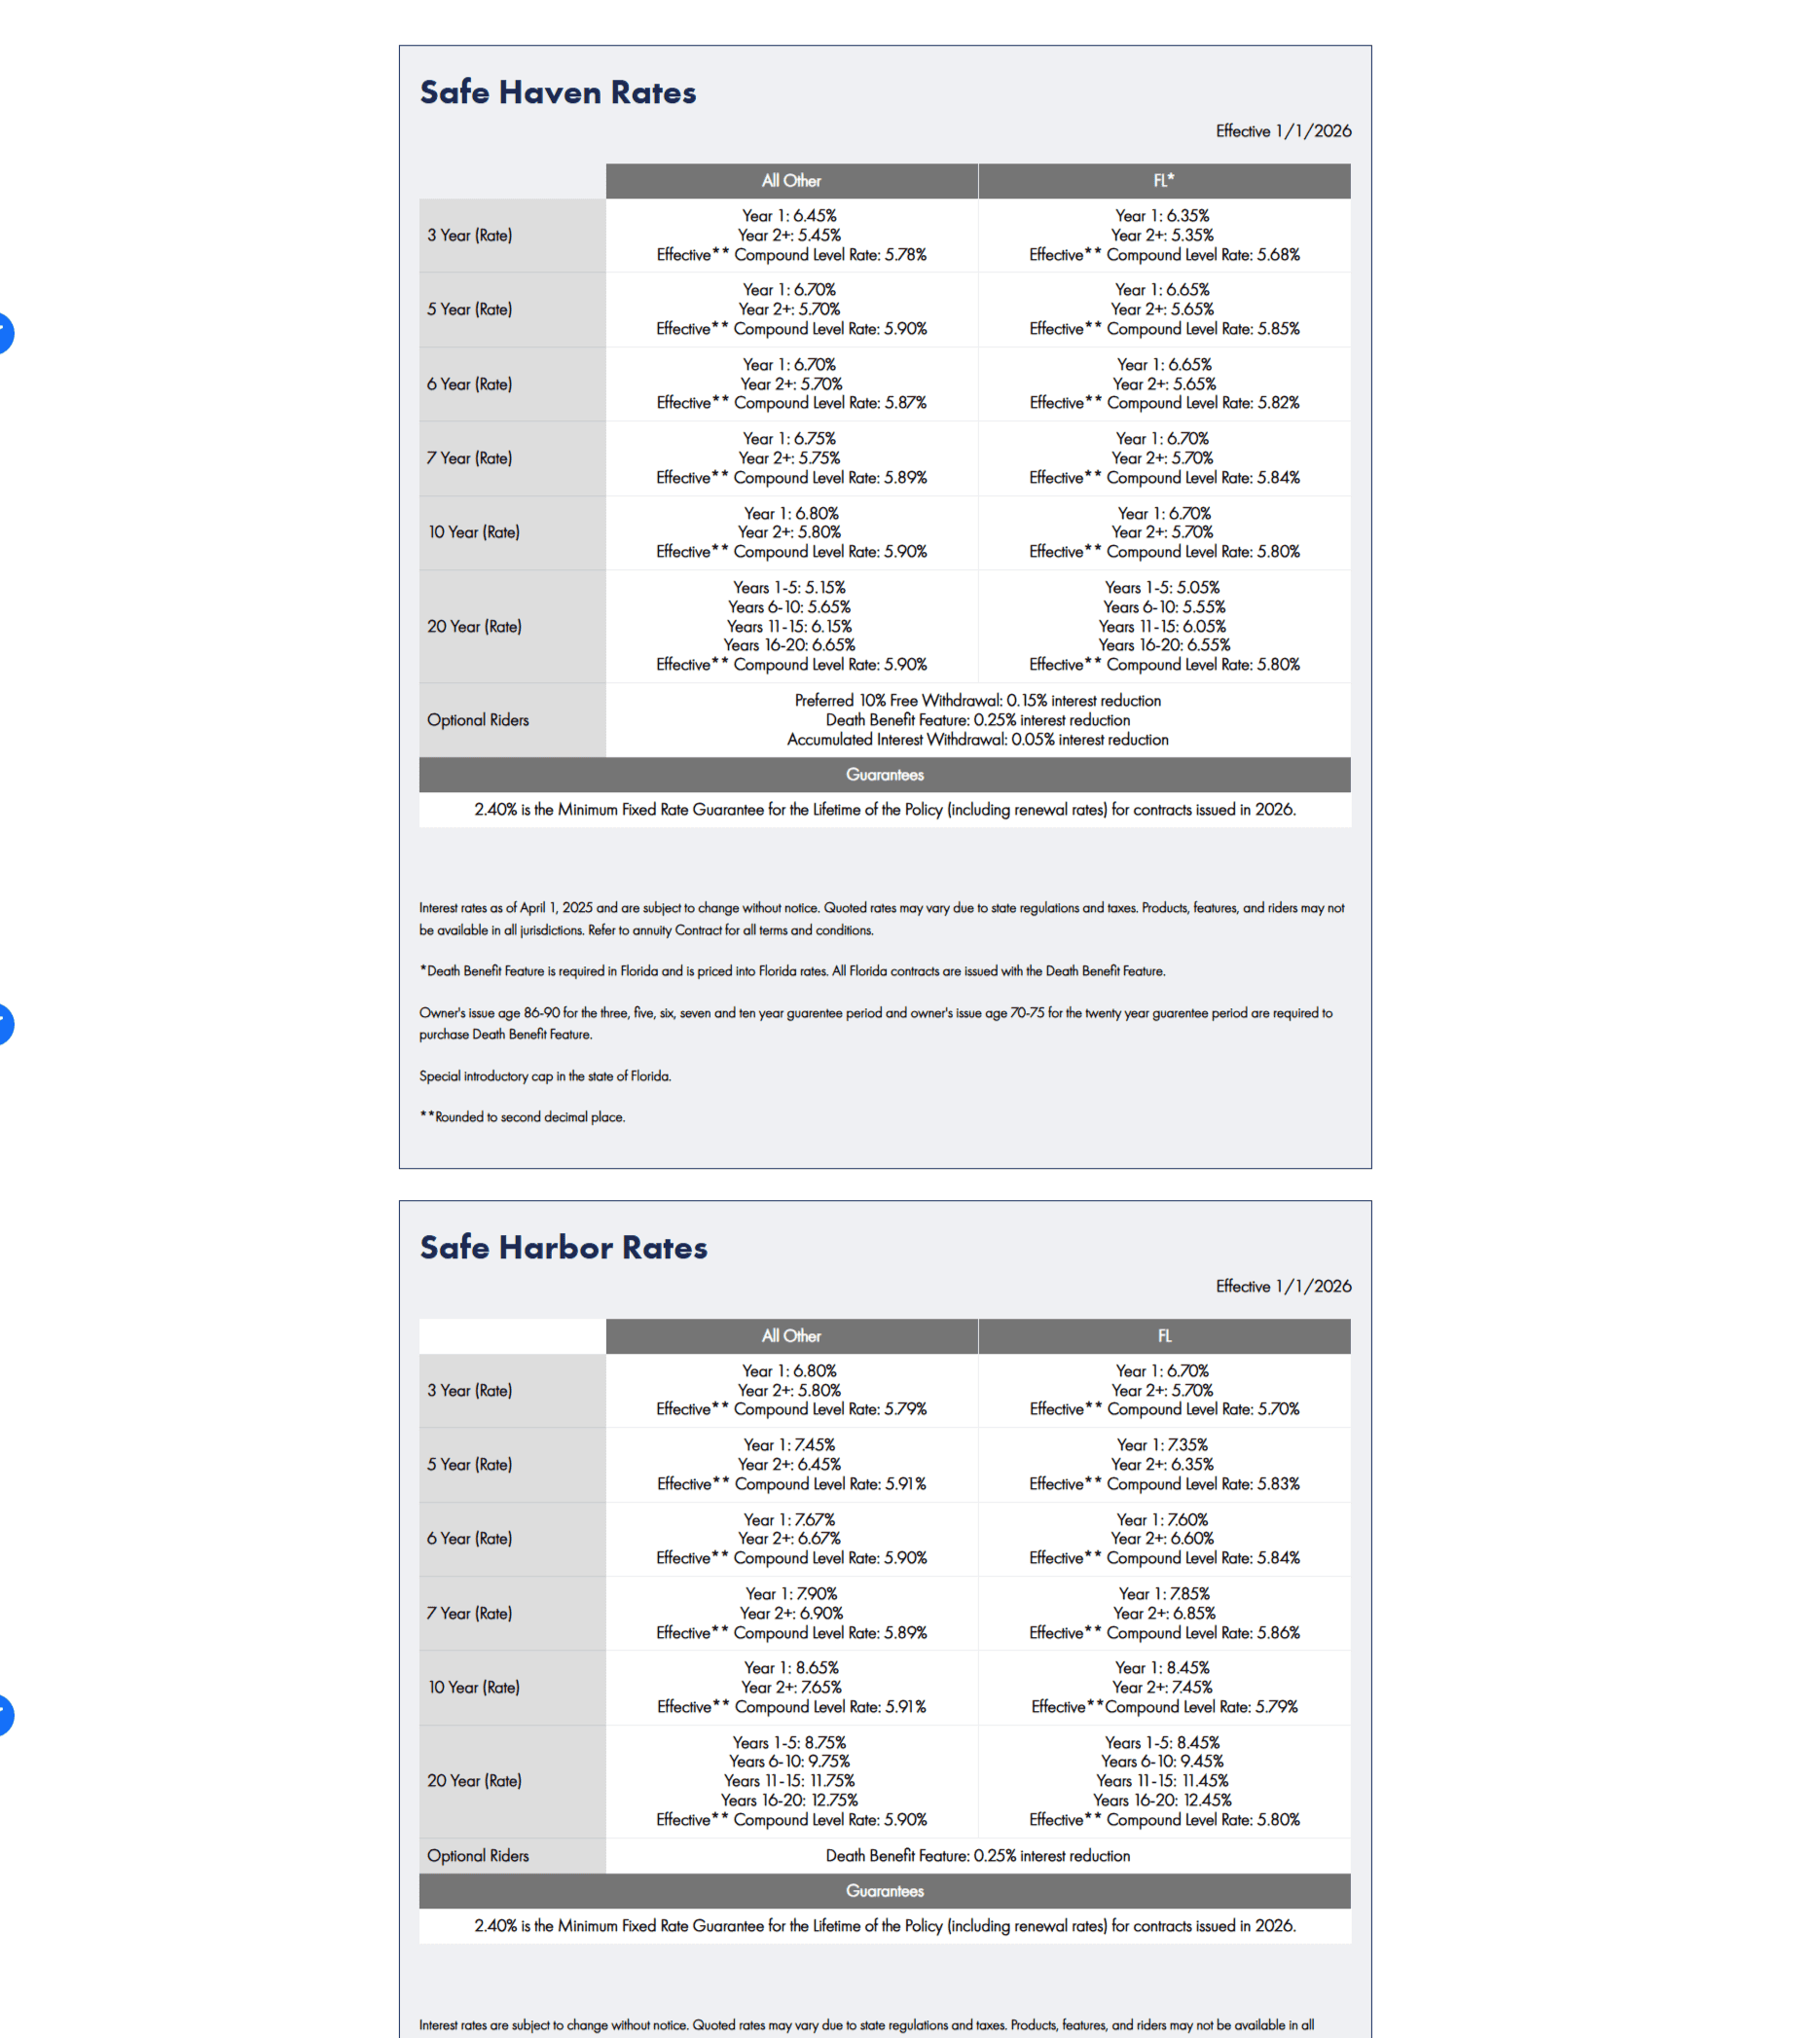
Annuity.org also inflates its interest rates or promotes non-MYGA annuities to attract callers. Here you can see they illustrate Global Atlantic ForeCare, which is a long-term care annuity used primarily for LTC expenses, not for fixed interest rates, and the rate is good for 1 year before the cost of insurance is withdrawn, which becomes way less than advertised. Atlantic Coast Life is offering simple interest with teaser rates that don’t compound to the correct APY. This is a classic bait-and-switch marketing tactic.

Reviews: Don’t Just Take Our Word for It
Check their Trustpilot profile. Some reviewers report being misled into thinking they were dealing with a licensed firm, only to be bombarded with cold calls from salespeople they never asked to speak with.
- Scammers collecting sales information. I asked for and never got, a simple list of rates, terms etc by company,
as I asked for. - Just a scam to collect data to sell to ‘advisors’. No info on various types of annuities or current rates.
✔ Pros and ✘ Cons
- ✔ Pros:
- Easy to navigate.
- Contains tons of general educational content for beginners.
- ✘ Cons:
- ❌ Owned by Launch That, an SEO marketing company—not a financial firm.
- ❌ Not a licensed broker that sells directly to you. No direct quotes, no advisors, no in-person service.
- ❌ Writers often lack any financial credentials.
- ❌ They sell your personal information to third-party agents.
- ❌ Can’t meet with anyone in person—even if you’re local.
- ❌ You lose control over who contacts you.
Why Using an “Insurance Matchmaker” Is a Bad Idea for Buying Annuities
Insurance matchmakers make buying an annuity look simple: enter your information and get connected with someone who can help.
The problem is that you don’t choose the advisor who receives your information.
You Don’t Know Who You’re Getting
The person contacting you could have:
- Six months of annuity experience or 20 years.
- Limited access to insurance companies.
- Complaints on their insurance or FINRA record.
- Little experience with retirement-income planning.
- A preference for products that pay higher commissions.
You should independently vet the person handling hundreds of thousands of dollars of your retirement savings.
Your Information Can Pass Through Multiple Parties
With a matchmaker, your information may be collected by the website, handled by a call center or marketing company, and then provided to an outside insurance agent or financial professional.
That information can include your:
- Name and contact information.
- Age.
- Retirement timeline.
- IRA or 401(k) balance.
- Investment amount.
- Income needs.
The fewer unnecessary parties handling your financial information, the better.
The Advisor May Not Be There Later
Annuities can last decades, but agents often:
- Retire.
- Change firms.
- Leave the insurance business.
- Sell their book of business.
- Stop participating in a lead program.
If that happens, you may have to start over with another advisor who knows nothing about why you originally purchased the annuity.
Compensation Can Influence Recommendations
Annuity sales can generate substantial commissions.
That doesn’t mean every agent using leads is doing something wrong. But consumers should always ask whether the recommended annuity is actually the best option or simply one the salesperson prefers to sell.
If I’m potentially moving $500,000 of my retirement savings, I’d rather know exactly who I’m talking to before giving that person details about my finances.
That’s why blindly accepting whoever a matchmaker sends you isn’t something I recommend.
Before working with any annuity professional, consumers should independently check the individual’s insurance license through their state insurance department and, when applicable, review their FINRA BrokerCheck record.
Why This Model Fails Consumers
1. You can’t buy from them — and you lose control of your data.
Because Annuity.org doesn’t sell or manage annuities, your contact information, investment details, and sometimes income level are distributed to outside agents. Once shared, you have no control over how your information is used or how many people contact you.
2. Privacy is critical when dealing with large investments.
Most annuity buyers invest hundreds of thousands of dollars or are elderly (age 80 and older), often representing their life savings or retirement income. Privacy and data security should be paramount. Unfortunately, these matchmaking websites treat your information as a commodity, not a confidential financial disclosure. This business practice is also confusing.
3. No efficient vetting process for the agents who contact you.
There is no standardized or transparent method for screening the agents or advisors who buy your data. You don’t know their experience level, disciplinary history, or whether they’re licensed in your state. That leaves you vulnerable to sales pressure, misinformation, or worse — unethical product placement.
4. High risk of being sold unsuitable or misleading products.
Because these matchmakers connect you with whoever paid for the lead, you may encounter agents offering:
- Low-performing annuities with limited upside potential
- Lower income payouts compared to stronger products on the market
- MYGAs with hidden gimmicks like teaser rates or restrictive liquidity clauses
- An agent may promote and sell annuities from a lower-rated financial company.
- Indexed annuities show unrealistic, astronomical illustrated returns that can’t be replicated in real life
These sales practices can result in contracts that underperform your expectations or even lead to abandonment reimbursement issues if you attempt to replace the policy later.
5. No accountability or post-sale service.
Once your data is sold, the matchmaker has no further involvement. They don’t provide illustrations, explain riders, or service your contract. If you buy an annuity through one of their leads and later need help with withdrawals, income elections, or death benefit claims, you’re on your own.
Why Working with a Licensed Independent Broker Is Better
A legitimate independent annuity broker or agency:
- Holds active state licenses and is authorized to sell and service annuities directly. There’s transparency and accountability to protect your best interests.
- Compares annuities from multiple top-rated insurers to find the best fit for your goals.
- Provides real product illustrations and fully explains income riders, surrender charges, liquidity, and death benefits before you buy. Informs you which annuity products to avoid.
- Maintains strict privacy and never sells your data.
- Offers ongoing service and annual reviews so your annuity continues to meet your needs.
When you work with a true independent broker, you get personalized recommendations, not a sales referral — and your financial data stays private and protected.
The True Cost of “Free” Matchmaking
Annuities are sophisticated financial tools that involve large sums of money and long-term commitments, requiring precision and experience to structure correctly. Because of their complexity, even small mistakes can lead to costly outcomes. A so-called “free annuity quote” from a matchmaker can ultimately cost you far more than you expect.
- Potential compliance problems or surrender penalties if you replace the contract later due to dissatisfaction.
- Lower returns or income because you’re steered into limited or subpar carriers.
- Reduced growth potential from conservative annuity designs that favor the agent’s commission, not your performance.
- Persistent spam from multiple agents using your data.
Whether you choose us or another professional, protect your privacy and your finances by working directly with a licensed insurance agent, financial advisor, or independent broker whom you’ve personally researched and vetted. Always confirm their license, carrier appointments, and experience before sharing your personal or financial information.
Buy from a licensed independent broker, not a data broker.
The Annuity Expert is an independent annuity and insurance agency licensed in all 50 states. We compare multiple A- or better-rated insurers, explain every feature, and safeguard your privacy. Get free, real quotes and expert guidance today — call 1-770-755-1565 or request your comparison online.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.