

Why Some Annuity Companies Should Be Avoided
1. Poor Financial Strength Ratings
Companies rated below A- by AM Best, Baa by Moody’s, or BBB by S&P are considered vulnerable during economic downturns. A company with a weak balance sheet may not be able to meet its future annuity obligations.
- Who Needs to Avoid Them: Anyone relying on guaranteed lifetime income or leaving a legacy. A downgrade or insolvency could disrupt your payouts.
- Who Might Still Consider Them: Investors chasing a bonus-only play with no intention to hold long-term (still very risky).
- Better Alternative: Choose insurers rated A or higher with long histories of stable performance.
Helpful Tip: If you are searching for a complete blacklist of specific red-flagged insurers rather than general contract traps, read our master directory of the worst annuity companies to avoid before making any financial decisions.
2. New or Unproven Insurance Companies
New or small insurers—especially those founded in the last 18 years —often lack long-term claims history, scale, or consistent renewal strategies. This includes Canvas Annuities and other marketing-only platforms backed by offshore or limited-purpose carriers.
- Who Needs to Avoid Them: Anyone wanting predictable renewal caps, consistent service, or stable GLWB income payouts.
- Who Might Not Be Concerned: Those planning to surrender early (but this undermines the purpose of an annuity).
- Better Alternative: Consider companies like MassMutual, Midland National, or Pacific Life with decades of performance history.
3. Companies Offering Only Engineered Indexes
Firms that don’t offer traditional indexes (like the S&P 500) and instead only use proprietary or volatility-controlled indexes often promise higher back-tested returns—but no verifiable long-term real-world history.
- Who Needs to Avoid Them: Growth-oriented annuity buyers who want transparency and legitimate upside.
- Who Might Use Them: Income-focused buyers using a GLWB where the crediting strategy doesn’t impact guaranteed income.
- Better Alternative: Look for annuities with traditional index options and at least one real estate or commodity index.
4. Fee-Heavy Variable or RILA Providers
Variable Annuities (VAs) and Registered Index-Linked Annuities (RILAs) can come with annual fees of 2–4% or more, especially with riders. If the carrier adds M&E fees, admin charges, and performance-based riders, your growth is limited—even in a bull market.
- Who Needs to Avoid Them: Conservative investors or retirees looking for guaranteed income and principal protection.
- Who Might Use Them: Younger investors who are comfortable with risk and want tax-deferred investment access.
- Better Alternative: Fixed Indexed Annuities (FIAs) offer growth potential with no direct downside and often include a 1-Year Fixed Interest Account.
- Root Cause: High-fee contracts are often pushed by “captive” advisors at banks or large wirehouses who can’t offer you better alternatives. It is important to ask who sold you this annuity? Because the source of the advice is often just as dangerous as the product itself.
5. Carriers With Poor Customer Service or Claim Payout History
Some companies get low marks for payout delays, claim denials, or service issues. Watch for consumer complaints on the Better Business Bureau, NAIC, and state insurance departments.
- Who Needs to Avoid Them: Everyone. Poor service can result in missed RMDs, delayed withdrawals, and botched beneficiary payments.
- Better Alternative: Work with a broker to find highly-rated companies with clean service records and clear claim policies.
Why Avoid Annuities from “B” Rated Insurance Companies?
Annuities from “B” rated insurance companies are generally considered the worst. Here’s why:
- Risk of Financial Stability: “B” rated companies may have weaker financial stability than “A” rated firms.
- Lower Reliability: These companies might not be as reliable regarding long-term commitments.
- Better Alternatives Available: With many annuity products in the market, opting for a more reliable “A” rated company usually makes more sense.
Misconceptions About High AM Best Ratings
A high AM Best rating, like “A++,” does not necessarily correlate to the quality of the annuity product. Here’s what to consider:
- Income Potential: Some products from highly-rated companies might offer less income potential.
- Growth Opportunities: These annuities might have minimal growth.
- Control Over Savings: There could be restrictions that limit control over your savings.
- Death Benefits: Some may not offer a death benefit.
Buyer’s Due-Diligence Checklist
- Index Transparency: Confirm which index is used and how returns are credited (cap, participation, spread).
- Cap Stability: Ask to see cap rates for multiple years—not just year one.
- Surrender Terms: Clarify how long the surrender charge period lasts, what the penalties are, and whether there are exceptions (e.g., terminal illness, nursing home).
- Liquidity Options: Are penalty-free withdrawals or riders available for emergencies?
- Downside Guarantees: Check if there’s a floor or just a buffer. A full floor (no loss) is safer for risk-averse buyers.
- Fees/Riders: Understand income riders, death benefits, or any additional costs.
- Comparison Shop: Use standardized illustrations to compare similar products side-by-side.
- Read the Prospectus: Critical terms, exclusions, and fine print are all there—don’t skip it.
Importance of Independent Annuity Brokers
Using an independent annuity broker is recommended because:
- Unbiased Advice: They are not tied to any specific company and can offer unbiased advice.
- Wider Range of Options: Independent brokers have access to a broader range of products.
- Tailored Solutions: They can find annuities that suit your specific needs and goals.

Annuities That Help You Avoid These Problems
- GLWB Annuities with Strong Carriers: These let you get guaranteed income without giving up control or legacy protection.
- Fixed Indexed Annuities (FIAs): Offer market-linked growth with no downside risk. Choose one with GLWB riders for income.
- Traditional Fixed Annuities (MYGAs): Compare current fixed annuity rates, and verify the withdrawal allowance on each contract before buying.
What You Can Do Today
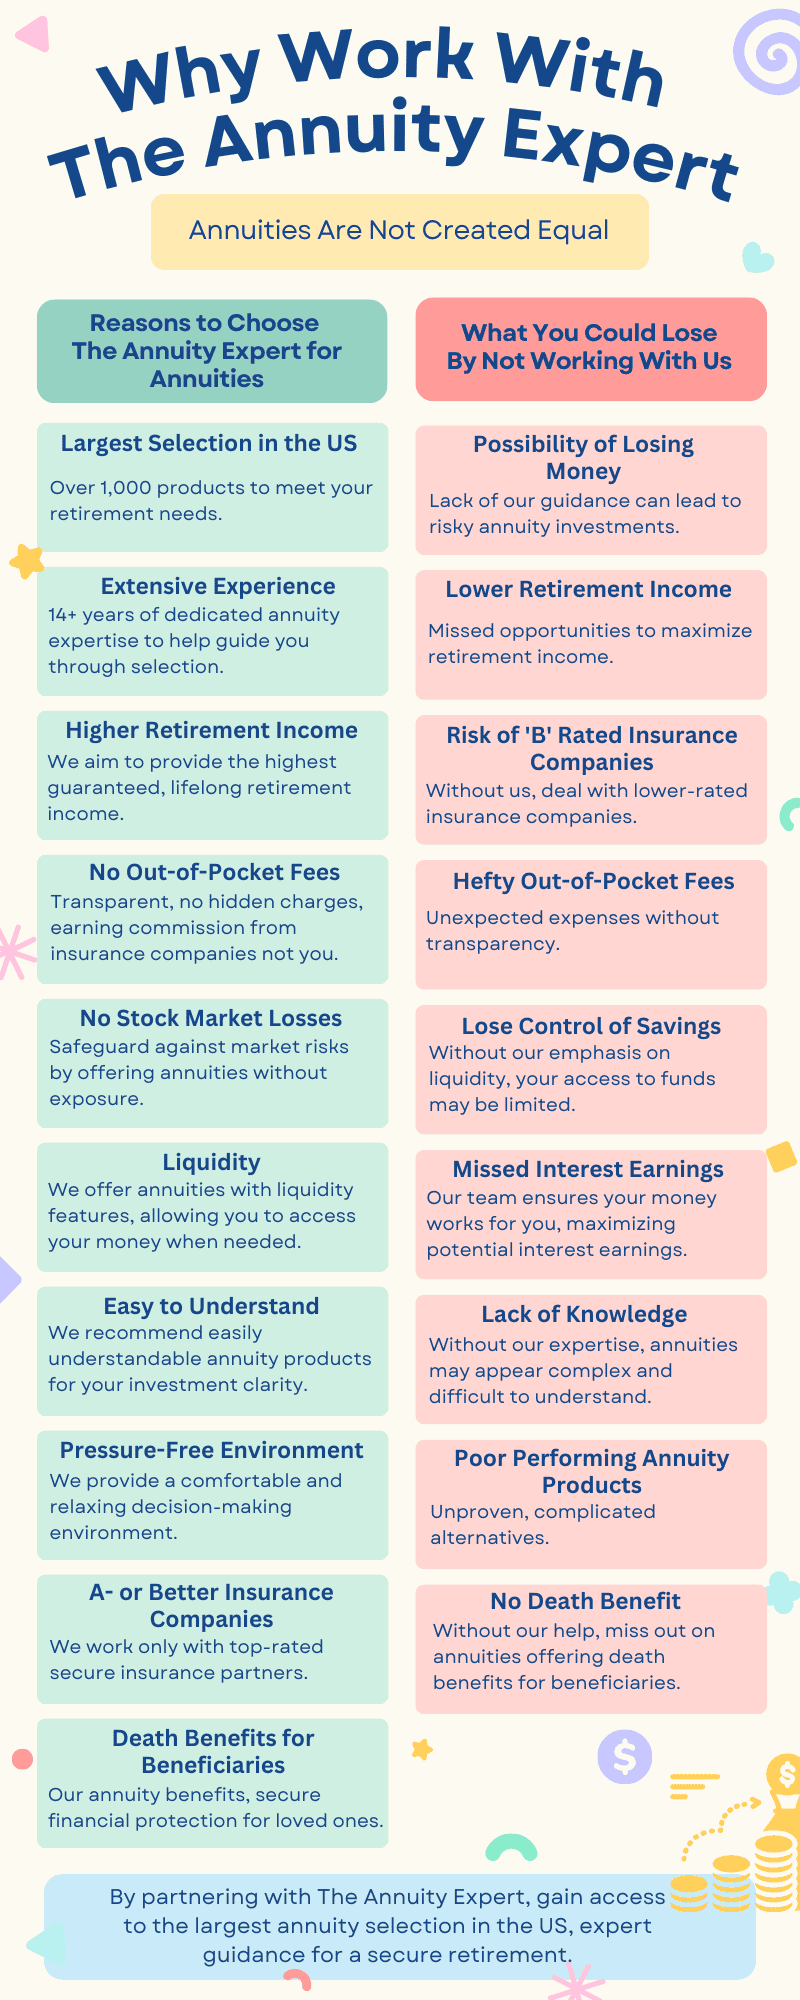
- Check Financial Strength Ratings. Only consider annuity companies rated A- or better by AM Best.
- Ask About Index Choices. Make sure at least one index is a traditional one like the S&P 500.
- Compare Surrender Schedules. Avoid long lockups with harsh penalties.
- Never Buy Direct. Always use an independent broker who represents multiple companies, not just one.
- Get an Income Rider You Control. GLWB riders let you stop, start, and leave a legacy. Avoid forced annuitization.
Need Help Comparing Safe Annuity Companies?
Speak to a licensed broker at The Annuity Expert to compare the safest annuity companies with the best income and growth options. We’ll show you who to avoid, who to trust, and how to get free quotes—so you don’t overpay or make a decision you’ll regret.
👉 Contact The Annuity Expert today for free annuity quotes and a custom plan built around your goals.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.