

Our Professional Opinion on the Symetra Select Pro MYGA
We recommend the Symetra Select Pro MYGA when its guaranteed rate is competitive, especially for buyers who want unusually strong annual liquidity without a Market Value Adjustment.
Symetra is a good annuity company. It is rated A by AM Best and comfortably meets our financial-strength standard.
Select Pro is available in 3-, 5-, and 7-year terms. In today’s high-interest-rate environment, the 5- or 7-year version can be attractive when you want to preserve a competitive rate for longer without giving up as much access as most MYGAs require.
The liquidity is the main reason to consider Select Pro. The contract generally allows annual withdrawals of up to 15% of the contract value beginning in the first year, and it does not use a Market Value Adjustment. That is substantially more flexible than many MYGAs offering only interest withdrawals or 10% access after the first anniversary.
Symetra also offers a version with a guaranteed return-of-premium feature. That protection can be useful if you are concerned about needing to surrender the contract early, but it comes with a lower guaranteed rate.
Do not buy the return-of-premium option automatically. If you have adequate emergency savings and expect to hold the contract through the full term, you may be giving up interest for protection you are unlikely to use. Compare the standard Select Pro and return-of-premium versions using the same premium and term.
We also like the account-value death benefit, spousal continuation, RMD treatment, additional first-year purchase payments, and health-related waivers. The nursing-home and terminal-illness waivers provide access to existing contract value; they are not a replacement for long-term care insurance.
After the initial guarantee period, the contract moves to an annually declared rate rather than automatically placing you into another multi-year surrender schedule. That gives you time to compare renewal rates without becoming trapped again.
Bottom line: Select Pro is one of the more liquid MYGAs and is a good choice when its rate is competitive. We would use the standard version when liquidity is already sufficient and add return-of-premium protection only when the lower rate is worth the extra guarantee.
Compare Select Pro with the current fixed annuity rates before selecting a term or purchasing the return-of-premium option.
What We Like
- A-Rated Insurance Company: Symetra comfortably exceeds our A- minimum.
- 3-, 5-, and 7-Year Terms: The product provides useful short- and intermediate-term rate locks.
- 15% Annual Liquidity: Percentage-based access begins in the first contract year.
- No Market Value Adjustment: Withdrawals are not increased or reduced because market interest rates changed.
- Optional Return of Premium: Buyers who value a contractual principal floor can purchase that protection.
- Additional First-Year Premiums: The contract can accept additional purchase payments during the first year.
- No Automatic Multi-Year Re-Lock: The contract becomes annually renewable after the initial term.
What We Don’t Like
- Return of Premium Lowers the Rate: The extra protection is purchased through reduced guaranteed interest.
- The Standard Version Has No Return-of-Premium Guarantee: An early surrender can return less than the original deposit after charges.
- Liquidity Can Reduce the Headline Rate: Select Max or another less-liquid MYGA may pay more.
- No Flexible Lifetime-Income Rider: Lifetime income requires traditional annuitization rather than a GLWB.
- The Rate Still Has to Be Competitive: Excellent liquidity does not justify accepting a materially lower guaranteed return.
What Is the Symetra Select Pro Fixed Annuity?
The Symetra Select Pro is a modified single-premium fixed deferred annuity (MYGA) designed for conservative investors who want tax-deferred accumulation, downside protection, and the option to generate income later. This product allows for additional contributions during the first contract year and comes in 3-, 5-, or 7-year guaranteed interest rate terms.
It is issued by Symetra Life Insurance Company, a Bellevue-based carrier with over 60 years in the insurance industry. Symetra is owned by Sumitomo Life of Japan, adding global financial backing to its U.S. annuity contracts.
Key Features of Symetra Select Pro
- Minimum Premium: $10,000 lump sum; $1,000+ additions allowed in Year 1
- Terms Available: 3, 5, or 7 years of guaranteed interest
- Free Withdrawals: 15% of contract value annually with no penalty
- Qualified Plan Support: Accepts IRAs, Roth IRAs, and non-qualified funds
- Annuitization Options: Lifetime, period-certain, or joint-life options
- Waivers: Nursing home, terminal illness, hospitalization
- Spousal Continuation: Spouse can assume contract ownership with full benefits intact
- Death Benefit: Pays the greater of account value or guaranteed minimum value
How Interest Grows
You choose a 3-, 5-, or 7-year fixed interest term. Symetra guarantees the rate for the duration you select. After that period ends, the rate resets annually but can never fall below the contract’s minimum guaranteed rate. Compounding is daily, and interest is tax-deferred, meaning no income taxes are due until funds are withdrawn.
Liquidity and Access to Funds
The annuity provides several liquidity options:
- 15% free withdrawals annually, starting in the first year.
- RMDs (Required Minimum Distributions) are waived from surrender charges.
- Waivers for terminal illness, hospitalization, and long-term care confinement.
These access provisions help mitigate one of the major cons of MYGAs—liquidity restrictions.
Income Options: Annuitization Required
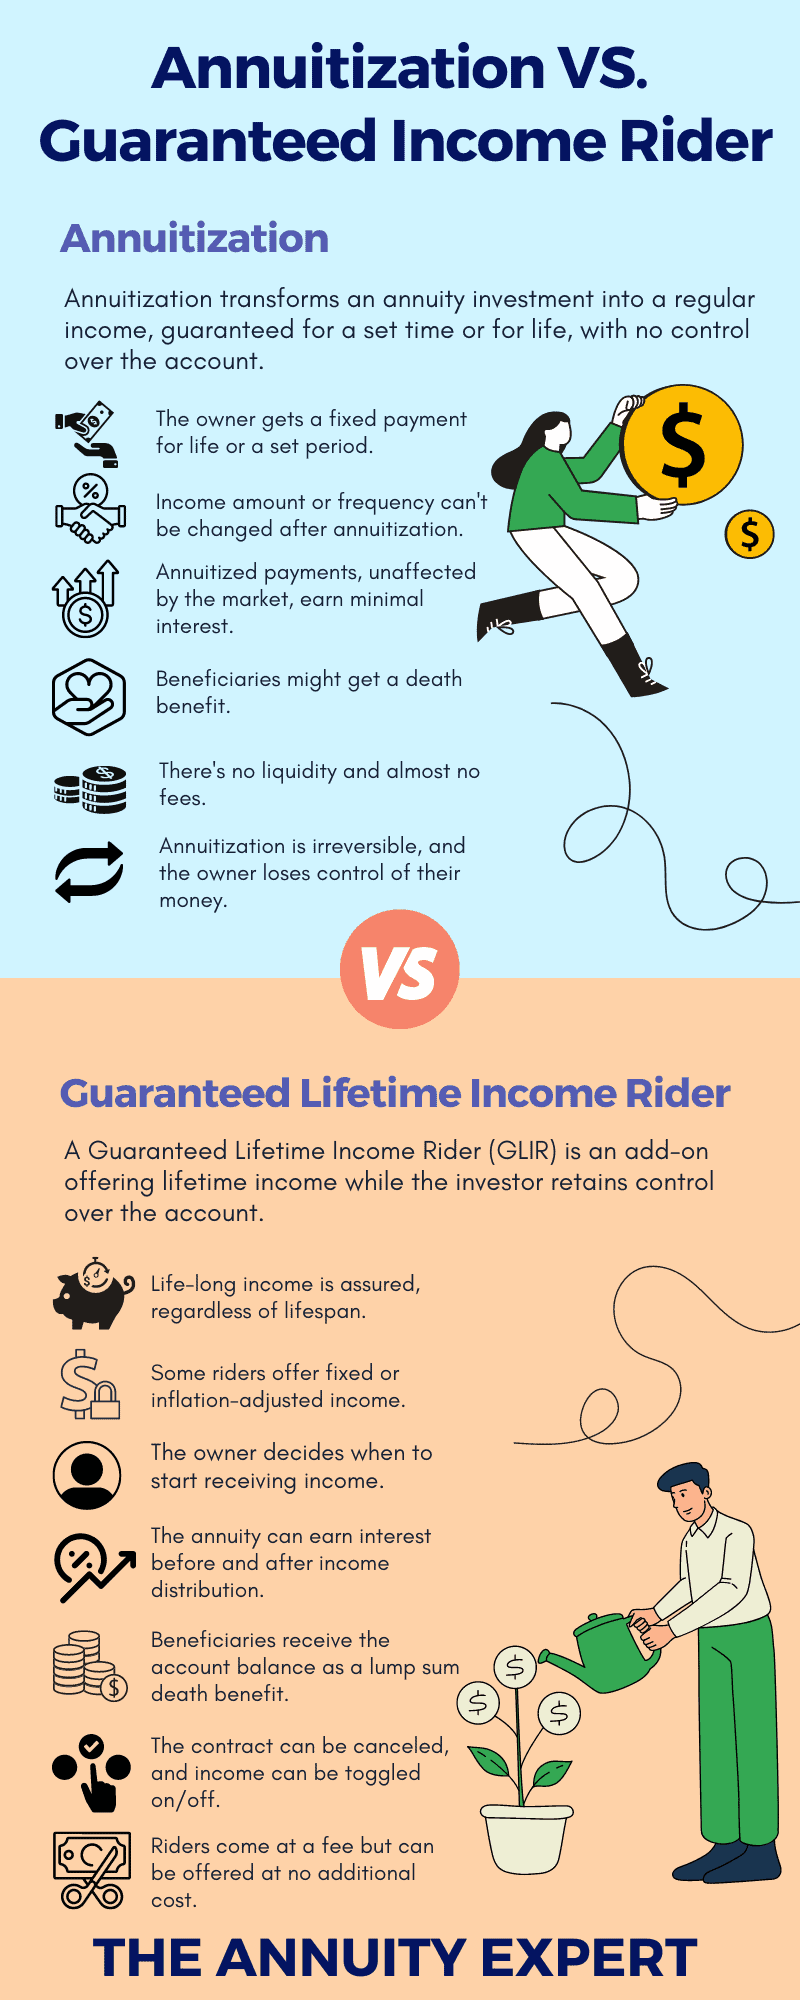
Unlike fixed index annuities with GLWB (Guaranteed Lifetime Withdrawal Benefit) riders, the Select Pro requires annuitization to turn the balance into a lifetime income stream. Annuitization is irrevocable, meaning once you choose your payout option, you lose access to the lump sum and the ability to change your income stream. Payout structures include:
- Lifetime income
- Joint-life income
- Period-certain income
This inflexibility may be a drawback for clients seeking lifetime income without giving up control of their asset.
What Happens After the Term Ends?
After the 3-, 5-, or 7-year guaranteed term:
- You may renew at a new one-year rate (which adjusts annually).
- You can annuitize the balance for income.
- You may surrender the contract, taking out the full account value.
- Funds can be rolled over into a new annuity.
There are no withdrawal charges after the term ends, providing full liquidity if you no longer need the contract.
Pros and Cons
Pros
- 15% free withdrawals annually
- Strong waiver provisions
- Tax-deferred compounding
- Daily interest crediting
- Strong spousal continuation benefits
Cons
- Income requires annuitization
- No GLWB rider available
- Not ideal for growth compared to index annuities
- No inflation protection
- Low liquidity if you exceed 15% early
Who Should Consider This Annuity?
This annuity is a good fit for:
- Investors nearing or entering retirement who want safety and moderate growth
- Those who value tax deferral and want to avoid market risk
- People looking for long-term savings with potential to convert to income
- Individuals who don’t mind using annuitization for income
Not ideal for:
- Investors wanting access to full funds in the early years
- Those looking for income now through a GLWB rider
- People who want participation in market gains
Are Other Types of Insurance Needed?
Because this annuity lacks income flexibility, pairing it with a life insurance policy could help restore liquidity or offset the irrevocability of annuitization. A Guaranteed Lifetime Withdrawal Benefit (GLWB) fixed indexed annuity might be a better fit for those who want lifetime income with control. Consider using:
- Fixed Index Annuities with GLWBs for income control
- Whole Life Insurance for death benefit replacement
- LTC Insurance to enhance long-term care benefits not fully covered by this annuity
Why Comparing Annuities Matters
The Symetra Select Pro is a solid MYGA for conservative accumulation, but if you’re not comparing it with other products, you might miss out on:
- Higher interest rates
- More flexible liquidity features
- GLWB riders
- Stronger carrier ratings
We recommend comparing products from A-rated or higher insurers that include enhanced income features or stronger growth options.
Bottom Line
The Symetra Select Pro is a well-rounded MYGA designed for guaranteed accumulation and eventual income via annuitization. It’s most suitable for conservative investors who prefer guarantees over growth, but not ideal for those who need flexible income options. Want to see how it compares? Contact The Annuity Expert for free quotes and recommendations. Let us help you find the right annuity for your goals.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.