

Take What You Give Up in Control, Growth, and Legacy Planning—and What to Do Instead
When it comes to turning your IRA into retirement income, annuitization sounds simple: hand your account over to an insurance company and receive guaranteed payments for life. But for most U.S. residents, especially those with IRAs, annuitizing the account is usually a bad idea. Here’s why it’s risky—and what smarter alternatives are available using insurance and annuity strategies.
What Does It Mean to Annuitize an IRA?
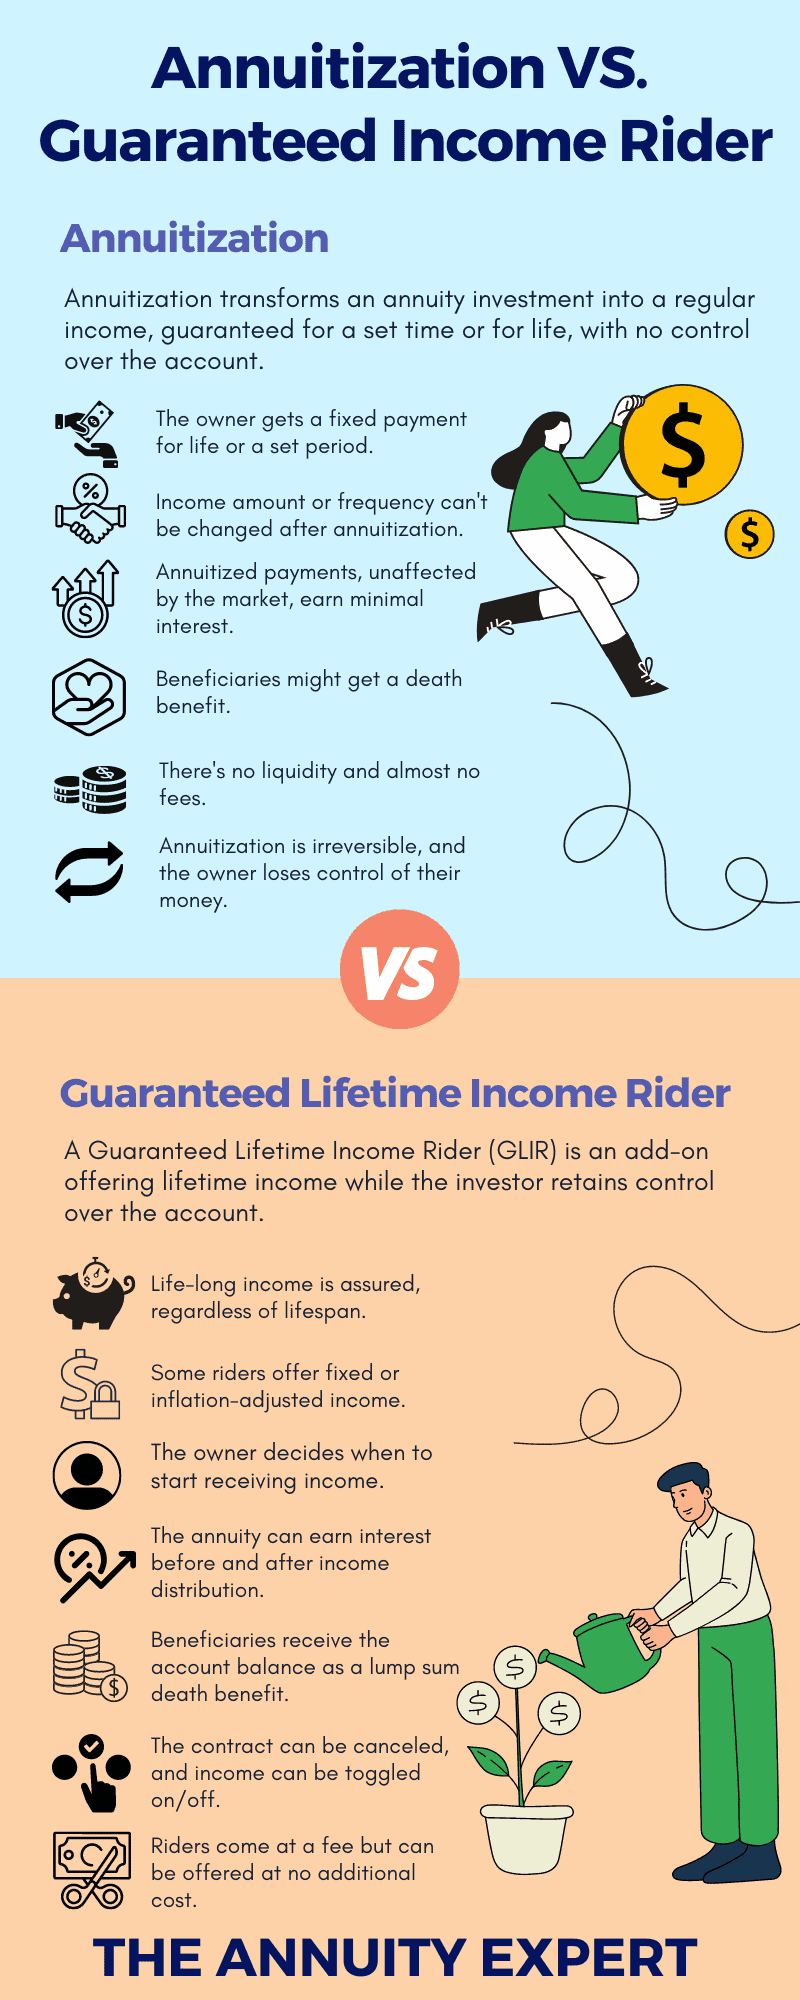
Annuitization is the irreversible process of converting a lump sum of money—such as your traditional or Roth IRA—into a stream of guaranteed payments, typically for life or a set number of years. You no longer own the asset; the insurance company does. In exchange, you receive a fixed periodic income.
Why Annuitizing an IRA Usually Doesn’t Make Sense
- You Lose Control of Your Money
- How It Works: Once you annuitize, you forfeit access to your IRA balance.
- Why It’s Bad: You can’t withdraw more in emergencies or respond to changes in spending needs, inflation, or market opportunities.
- Who This Hurts: Anyone who values flexibility, estate planning, or wants to respond to market changes.
- Your Heirs May Receive Nothing
- How It Works: Unless you choose a refund or period-certain option, payments stop at your death.
- Why It’s Bad: You could die shortly after annuitization, and your family receives nothing.
- Better Option: Use a guaranteed lifetime withdrawal benefit (GLWB) rider on a deferred annuity, which continues income and leaves remaining value to heirs.
- No Growth Opportunity
- How It Works: The insurance company calculates your monthly payments using your age and interest rates at the time of annuitization.
- Why It’s Bad: You miss out on potential market growth, higher interest rates, and rising income potential.
- Better Option: A fixed-indexed annuity with a GLWB provides guaranteed income and growth tied to a market index, with no downside risk.
- It’s Irrevocable
- How It Works: Once annuitized, the decision is permanent.
- Why It’s Bad: You can’t reverse it if tax laws change, your expenses increase, or you need to revise your strategy.
- Better Option: Deferred annuities with GLWBs allow you to delay or start income at your discretion.
- Tax Disadvantages
- How It Works: Traditional IRA annuity payments are taxed as ordinary income.
- Why It’s Bad: You lose tax deferral and may end up in a higher bracket if income is misaligned with other retirement sources.
- Better Option: Use Roth IRA conversions and income control features in GLWBs to manage taxes more efficiently.
When (Rarely) Annuitizing an IRA Might Make Sense
Annuitization is sometimes useful for:
- Medicaid-compliant annuities for long-term care planning in certain states.
- Early retirees under 59½ use a life-only SPIA (Single Premium Immediate Annuity) to avoid the 10% IRS penalty, but only when paired with life insurance to replace lost legacy value.
Even then, using GLWBs or MYGAs with penalty-free withdrawals is usually a better solution.
Who Shouldn’t Annuitize an IRA
- Those who want to leave a legacy
- Investors who need flexibility or control
- Anyone with a moderate or long life expectancy
- People are uncomfortable giving up access to their money
- Tax-sensitive retirees trying to manage IRA RMDs efficiently
Better Alternatives to Annuitization
- Fixed Indexed Annuity (FIA) with GLWB
- Provides guaranteed income for life
- Still allows growth and access to funds
- Passes the remaining value to beneficiaries
- Multi-Year Guaranteed Annuity (MYGA)
- Use for short-term guaranteed interest
- Offers penalty-free liquidity and tax deferral
- Ideal for RMD strategies or laddering income
- Deferred Income Annuity (DIA) with Refund Option
- Delays income, grows value for later
- Refund options protect legacy
- Safer than immediate annuitization
- Life Insurance
- Replaces lost legacy value when using SPIAs or GLWBs
- Also provides living benefits for LTC or terminal illness
Can You Fund Annuities from an IRA?
Yes. You can fund:
…all with:
Other Insurance to Consider
- Long-Term Care Insurance: Protects against devastating care costs without raiding your IRA.
- Hybrid Annuity and LTC Policies: Combine income with long-term care benefits.
- Life Insurance with LTC Riders: Covers both death benefit and living needs.
- Medicare Supplement Insurance: Keeps health expenses from disrupting your income plan.
Final Word
Annuitizing your IRA is a decision that trades flexibility, legacy, and growth for a fixed income. Most people can achieve the same or better outcomes using GLWB annuities, MYGAs, or other modern insurance strategies, with fewer trade-offs and more control.
Contact The Annuity Expert for free quotes and help building an IRA income strategy that protects your money, your lifestyle, and your family.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.