

What Is An Annuity Arbitrage?
Annuity arbitrage refers to the strategic purchase of annuities with o20ther financial tools—such as life insurance, pensions, or trusts—to take advantage of pricing, tax, and regulatory inefficiencies. These legal strategies are designed to either increase income, reduce taxes, improve legacy benefits, or protect against inflation and longevity risk.
Financial professionals, high-income earners, and retirees use annuity arbitrage to convert low-yielding or inefficient assets into higher-performing income streams or estate assets. But these aren’t exclusive to the wealthy. Middle-class Americans can also benefit—especially those facing key decisions like whether to annuitize a pension or protect a nest egg from taxes and long-term care costs.
Compare Annuity Rates
Our annuity calculator helps you find the best annuity rates for retirement. It provides personalized quotes from top-rated insurance companies and compares rates to give you accurate annuity payouts. This tool estimates guaranteed lifetime annuity payments, either immediately or deferred.
1. Life Insurance and SPIA Arbitrage
How it works: You purchase a Single Premium Immediate Annuity (SPIA) that pays out lifetime income immediately. Then you use part of that guaranteed income to purchase life insurance with a death benefit equal to (or greater than) the original investment in the annuity.
Why this works: SPIAs may offer favorable pricing for income, especially for those in average or below-average health. Meanwhile, healthy individuals can get inexpensive permanent life insurance. The arbitrage lies in using income from a taxable asset (SPIA) to fund a tax-free death benefit (life insurance).
Pros:
- Lifetime income with predictable cash flow
- Replaces lost annuity principal with a tax-free life insurance death benefit
- May increase estate value or legacy gifts
Cons:
- SPIA income is irrevocable and lacks flexibility
- If health declines, insurability for life insurance may be compromised
- No access to principal once annuitized
Who needs it: Retirees who want a guaranteed income now and still want to leave something behind for children or a spouse. This is also ideal for early retirees seeking income before age 59½ while avoiding early withdrawal penalties.
Who doesn’t: Anyone with major health issues that disqualify them from affordable life insurance. Those who need liquidity or flexibility.
Other insurance you may need: Permanent life insurance—either whole life or indexed universal life (IUL)—to fund the death benefit efficiently.
2. Pension Lump Sum vs. Private Annuity Arbitrage
How it works: When offered a lump sum from a pension plan, you compare the guaranteed income your employer’s annuity provides to what you could purchase on the open annuity market (like a Fixed Indexed Annuity with a GLWB). If private options offer more favorable payouts, joint income, or death benefits, you take the lump sum and purchase the private annuity.
Why this works: Corporate and government pension annuities typically offer limited income options (like single-life or joint-life) and little to no death benefit. Private annuities can include enhanced features, inflation protection, and market participation.
Pros:
- Option to choose annuities with better features or higher payout
- Ability to include spousal continuation or beneficiaries
- Potential to grow assets if using a fixed indexed annuity
Cons:
- Must shop the market and compare quotes
- A lump sum may be less secure than a pension if mismanaged
- Loss of some employer-sponsored benefits or inflation-adjustments
Who needs it: Retirees comparing employer pension annuities to what’s available on the retail annuity market, especially if they want more flexibility, better survivorship protection, or joint income.
Who doesn’t: Those whose pensions already offer better-than-market rates or generous COLAs (cost-of-living adjustments).
Other insurance you may need: Life insurance to supplement income or provide spousal legacy protection.
3. Deferred Income Annuity (DIA) and Life Insurance Pairing
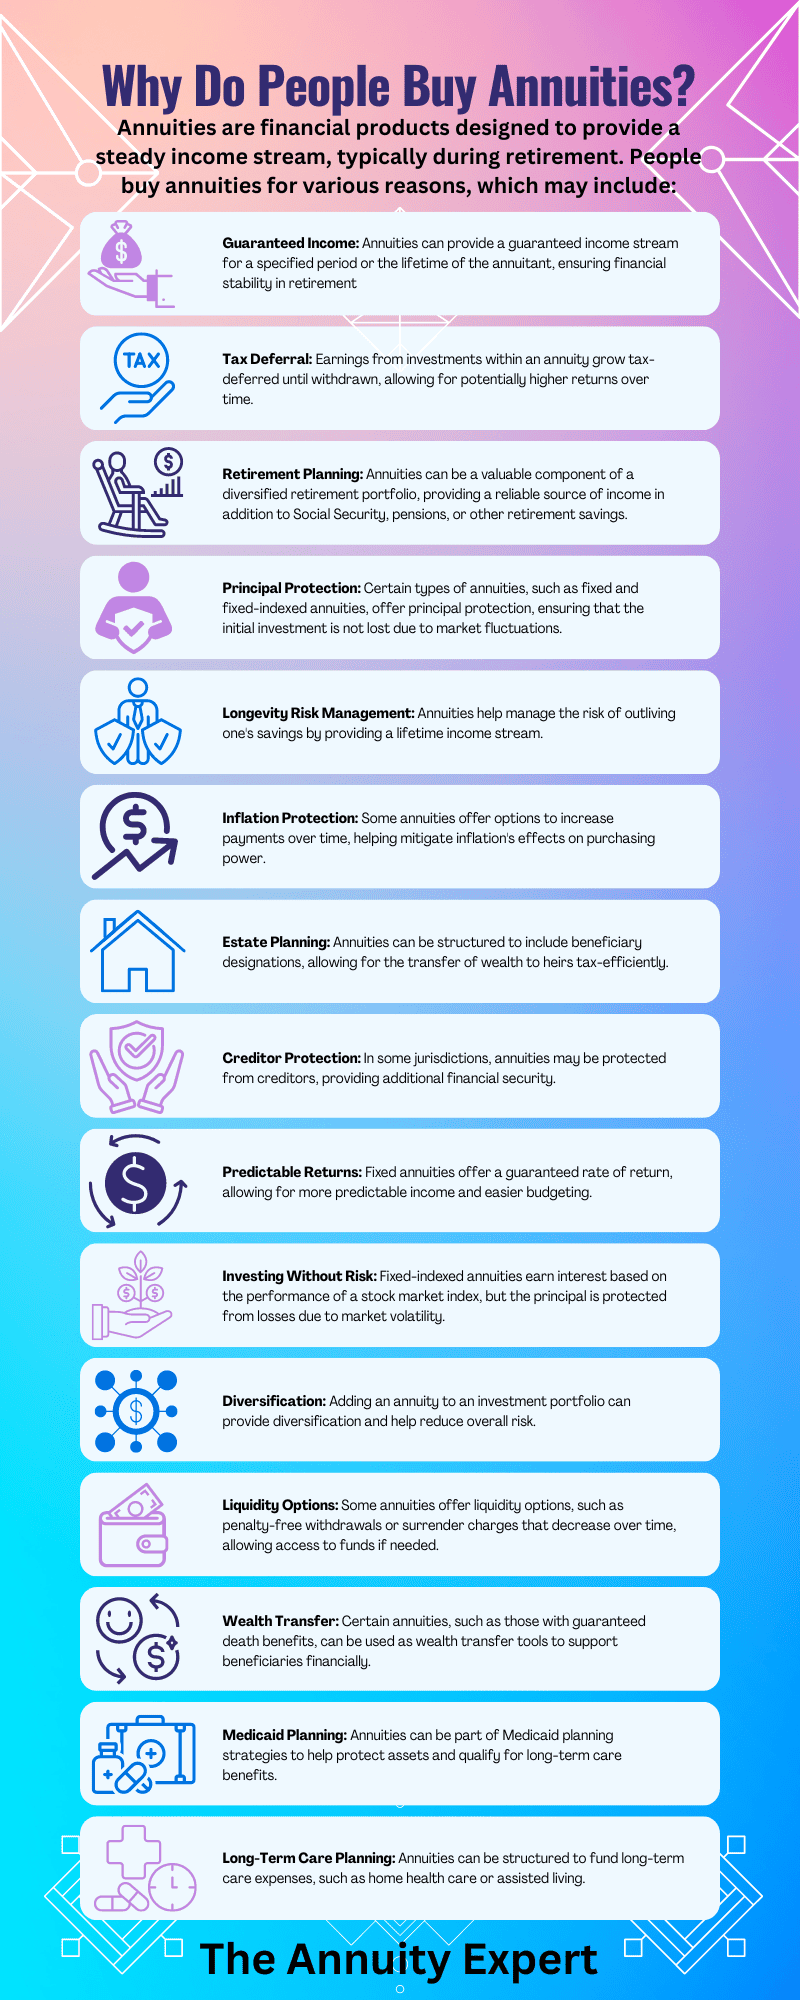
How it works: You buy a Deferred Income Annuity that begins paying in 10+ years and simultaneously fund a permanent life insurance policy today. The DIA handles future income, while the life insurance protects your family in the meantime.
Why this works: A DIA allows for income deferral and long-term planning, while the life insurance ensures your beneficiaries are protected if you die before income starts. This combo reduces tax burdens and creates a hedge against longevity risk.
Pros:
- Tax-deferred growth on DIA; fixed future income
- Income can’t be outlived
- Life insurance offsets premature death risk
Cons:
- Money is illiquid for years
- Requires careful timing and health qualification for life insurance
- DIA rates may change over time
Who needs it: High earners looking to reduce taxable income and fund future retirement while locking in legacy protection.
Who doesn’t: Someone with short-term income needs or who can’t qualify for affordable life insurance.
Other insurance you may need: Whole life or IUL policies structured for cash value and death benefit efficiency.
4. Charitable Gift Annuity (CGA) Arbitrage
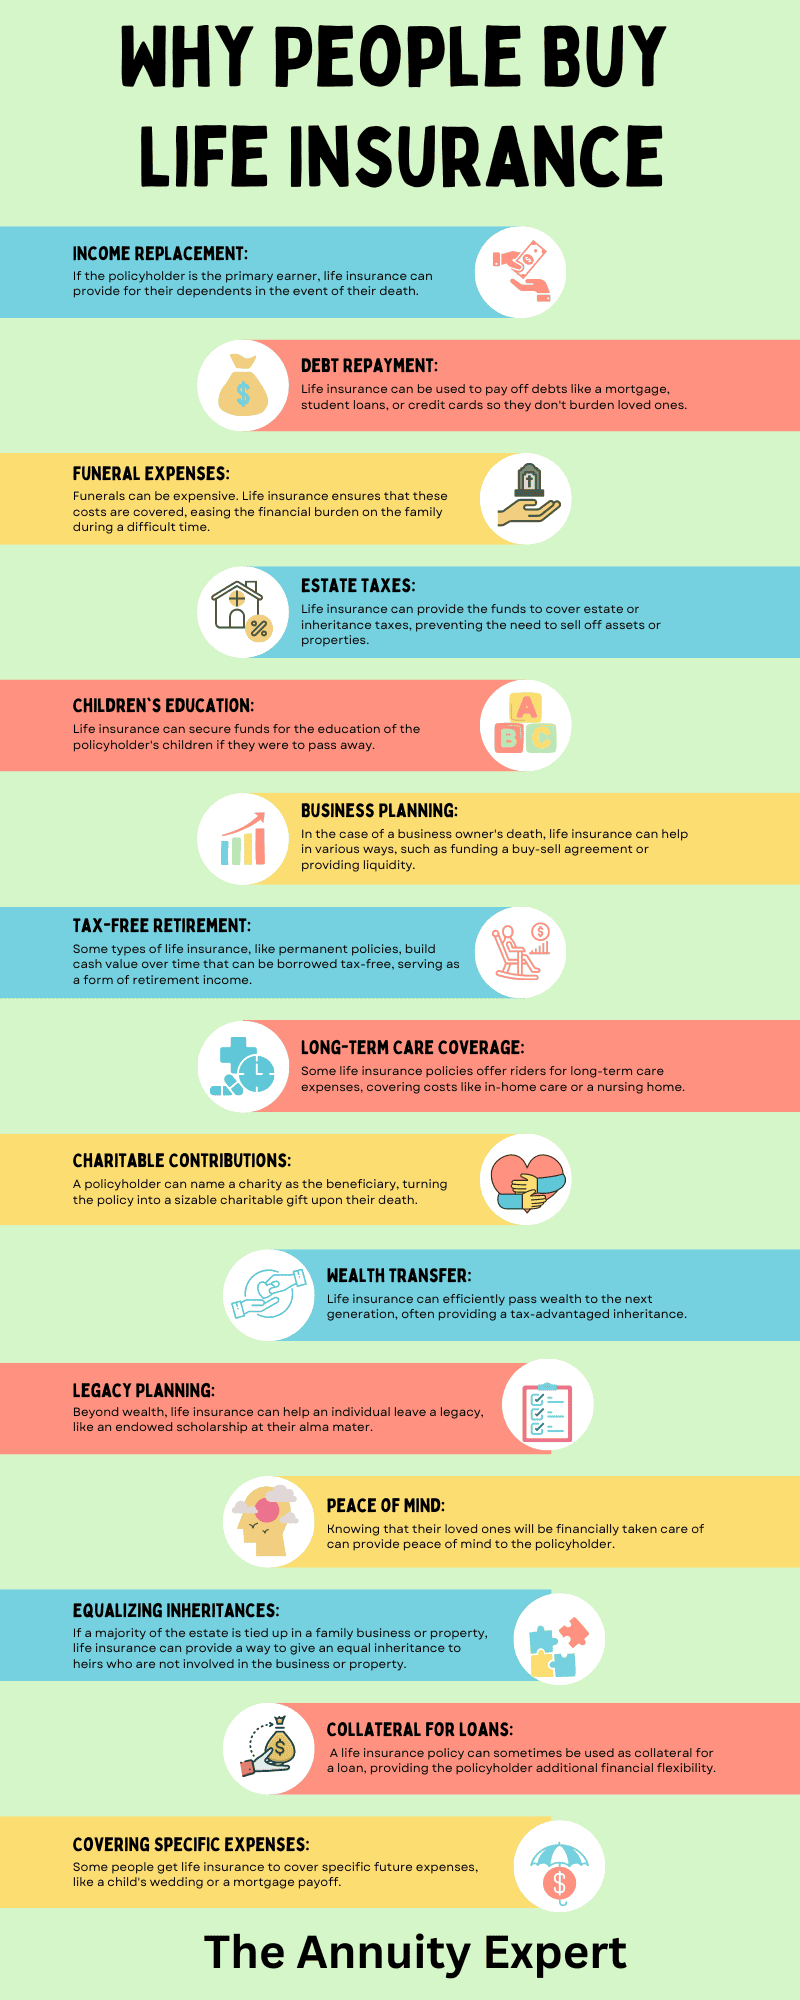
How it works: You donate assets to a nonprofit in exchange for a lifetime income stream and a charitable tax deduction. Then you use the income or tax savings to fund life insurance for your heirs, ensuring your legacy continues.
Why this works: The charitable deduction can significantly reduce taxable income, while the guaranteed lifetime income often exceeds what you could earn from low-risk investments. The life insurance replaces the donated asset for your heirs.
Pros:
- Lifetime income and a sizable tax deduction
- Supports your favorite charity
- Can replace donation value with tax-free life insurance
Cons:
- Irrevocable gift
- Income is partially taxable
- Charity assumes investment risk and payment responsibility
Who needs it: Donors aged 65+ who want to make a charitable impact while preserving personal income and family legacy.
Who doesn’t: Younger donors who may need access to principal or those without charitable intent.
Other insurance you may need: Guaranteed universal or whole life insurance to replace gifted wealth tax-free.

5. FIA with GLWB and Life Insurance Strategy
How it works: Buy a Fixed Indexed Annuity (FIA) with a Guaranteed Lifetime Withdrawal Benefit (GLWB) for income. Use the income stream or a portion of unused funds to purchase life insurance that builds cash value or replaces wealth.
Why this works: The FIA protects principal while offering market-linked growth potential. The GLWB ensures lifetime income, and the life insurance adds death benefits or estate liquidity.
Pros:
- No risk of principal loss
- Market participation without downside
- Legacy protection via life insurance
Cons:
- GLWB fees reduce potential returns
- Life insurance may reduce after-tax income
- Inflexibility in income withdrawals
Who needs it: Conservative investors nearing retirement who want income, protection, and tax-advantaged death benefits.
Who doesn’t: Investors who prefer direct stock exposure or who need access to their full principal.
Other insurance you may need: IUL or whole life to complement the GLWB’s income structure.
Additional Arbitrage Strategies
- 1035 Exchange Arbitrage: Move from an outdated annuity to one with better features (e.g., lower fees, new GLWB, better index options) without tax penalties.
- QLAC Arbitrage: Use up to $210,000 of qualified funds to defer RMDs until age 85 and lock in future income.
- MEC Arbitrage: Use modified endowment contracts for higher tax-deferred growth if income needs are low but death benefit efficiency is high.
Who Needs Annuity Arbitrage Strategies
- Pre-retirees with pensions, retirement plans, or lump sums to manage
- Individuals with high taxable income seeking legacy or charitable options
- Retirees who want a guaranteed income and a legacy for loved ones
- People in good health who qualify for cost-effective life insurance
Who Should Avoid These Strategies
- Anyone in poor health who can’t qualify for life insurance
- Those who need liquidity or access to funds
- People unfamiliar with annuities who are unwilling to compare product features or shop around
- Those who have no legacy goals or don’t need income planning
Final Thoughts
Annuity arbitrage strategies can dramatically improve financial outcomes for individuals willing to coordinate annuities, life insurance, and other planning tools. However, they are only as good as the products you choose and the way you structure them.
Don’t go it alone. Contact The Annuity Expert to compare annuity quotes, life insurance rates, and receive a personalized strategy that works best for your income and legacy goals.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.