

Fixed Indexed Annuities: A Compelling Option for Aggressive Retirement Growth
Aggressive investors want more upside potential than conservative annuities typically offer. The problem is that traditional stock market investing exposes retirement savings to permanent losses during market downturns.
Some fixed indexed annuities (FIAs) attempt to bridge that gap by offering principal protection combined with stronger growth potential than traditional fixed annuities.
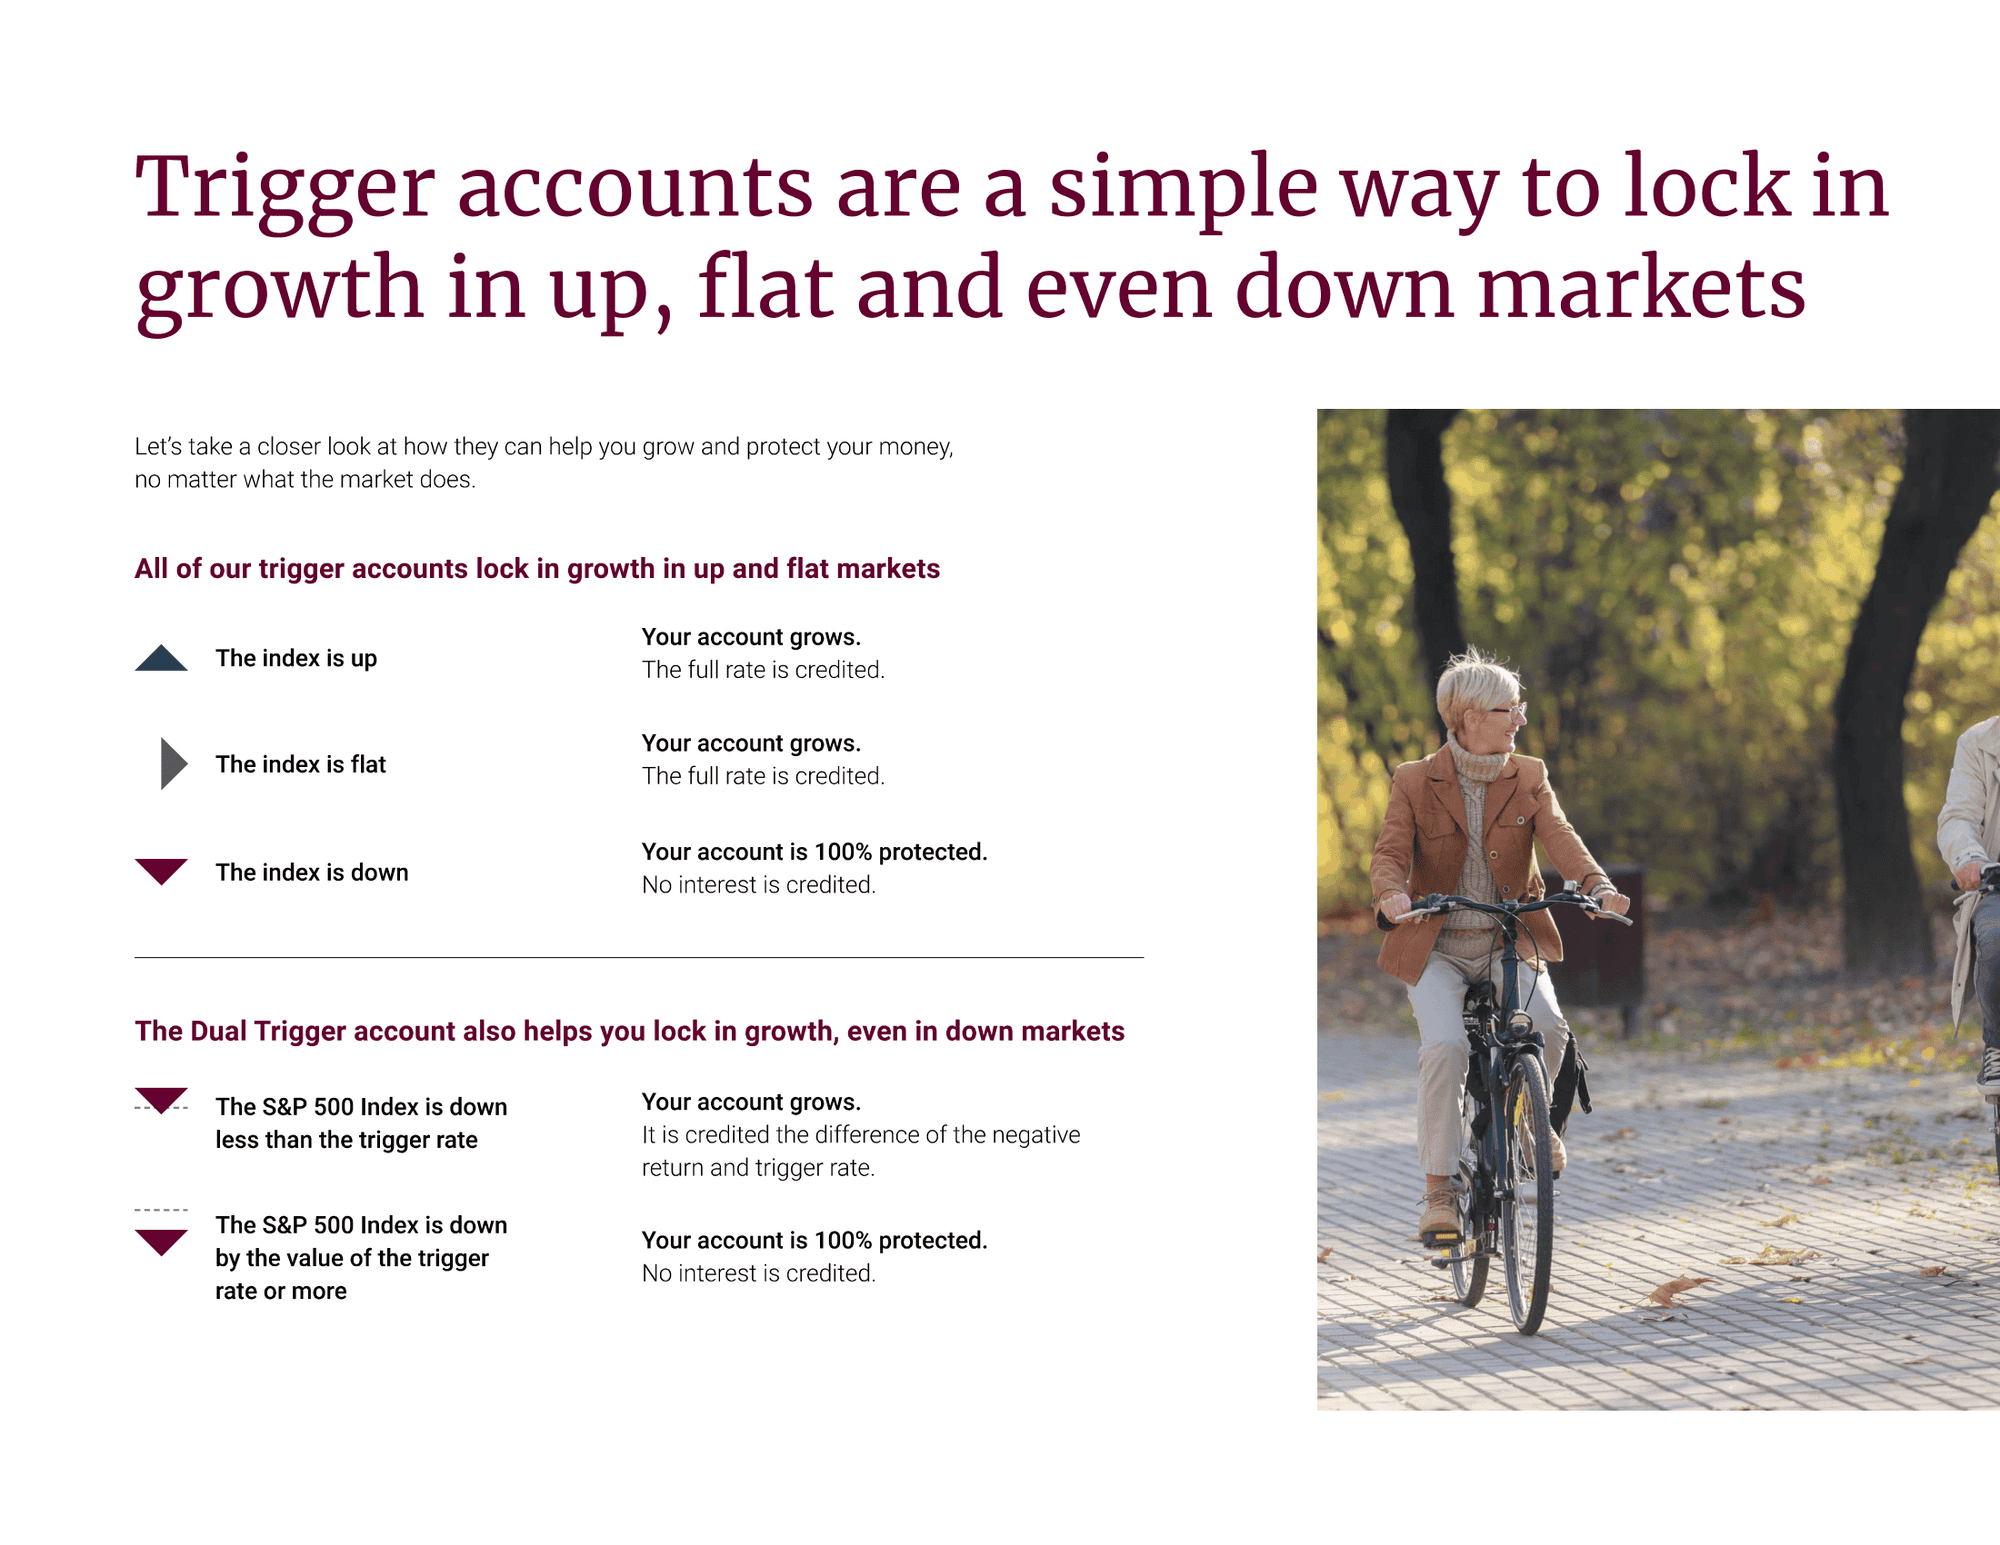
These contracts do not invest directly in the stock market. Instead, they credit interest based on the performance of market indexes while protecting your principal from losses.
Several FIAs stand out for investors seeking more aggressive growth, especially those with uncapped S&P 500 strategies, which can inspire confidence in higher growth potential.
These strategies allow investors to capture a large portion of market growth while still protecting their savings from market downturns.
Lincoln OptiBlend 7 Fixed Indexed Annuity
The Lincoln OptiBlend 7 is designed for investors who want stronger market participation than traditional fixed annuities while maintaining principal protection. This annuity provides several indexed crediting strategies that allow investors to capture stock market gains while protecting against losses.
How This Annuity Works
Your premium is placed into a deferred annuity contract. Interest is credited based on the performance of a market index rather than a direct market investment. The contract offers several crediting strategies, including:
- Fixed account: A declared interest rate that is guaranteed for one year and reset annually.
- Trigger strategies: Interest is credited if the index reaches a predetermined level.
- Cap strategies: Gains are credited up to a maximum cap.
- Participation strategies: Interest is credited based on a percentage of the index return.
These strategies allow investors to diversify how interest is credited to their accounts.
Aggressive Growth Strategy
Uncapped S&P 500-based crediting strategies in FIAs enable investors to capture approximately 70% to 80% of market gains, offering higher growth potential than traditional capped strategies, which can attract high-net-worth individuals seeking aggressive growth.
These strategies typically allow investors to capture roughly 70% to 80% of the market’s upside, which is significantly higher than traditional capped FIA strategies.
However, there is a trade-off.
These strategies usually use longer reset periods, often five to seven years, instead of the typical annual point-to-point strategy used in most fixed indexed annuities. That means interest is credited less frequently. Instead of seeing gains every year, interest may only be applied at the end of the longer reset period.
Lock-In Feature
Some of these longer reset strategies include a lock-in feature, giving investors a sense of control to secure gains during market peaks and feel more confident in their growth strategy. The lock-in feature allows investors to secure current index gains during reset periods, helping protect accumulated growth if the market peaks early in the cycle, which can be a key consideration for retirement planning.
- The credited gain becomes permanent
- The contract begins earning a fixed interest rate for the remainder of the reset term.
- When the reset period ends, the investor can choose a new index strategy.
This feature can help protect gains during long reset periods when the market experiences strong growth early in the cycle.
Pros and Cons
Pros
- Principal protection: Your account value will not decline due to market losses.
- Higher upside potential: Uncapped S&P 500 participation strategies offer stronger growth potential.
- Diversification of strategies: Multiple crediting options help spread risk.
- Tax-deferred growth: Interest compounds without taxation until withdrawals occur.
- Liquidity features: Many contracts allow 10% annual withdrawals after the first year.
Cons
- Longer reset periods: Interest may only be credited after five to seven years.
- Caps and participation limits: You will not receive the full market return.
- Surrender charges: Early withdrawals beyond allowed amounts trigger penalties.
- Strategy complexity: Understanding multiple crediting methods takes time.
Who Needs This Annuity
This annuity works well for investors who:
- Want stronger growth potential than traditional fixed annuities
- Want principal protection from market losses
- Are comfortable with longer crediting periods
- Are investing with a long-term time horizon
Who Does Not Need This Annuity
This annuity is not ideal for investors who:
- Want annual interest crediting
- Need frequent liquidity
- Want full stock market participation
Athene Aviator Fixed Indexed Annuity
The Athene Aviator is designed for investors seeking higher growth potential through diversified index strategies. The product emphasizes performance potential while still providing principal protection from market losses.
How This Annuity Works
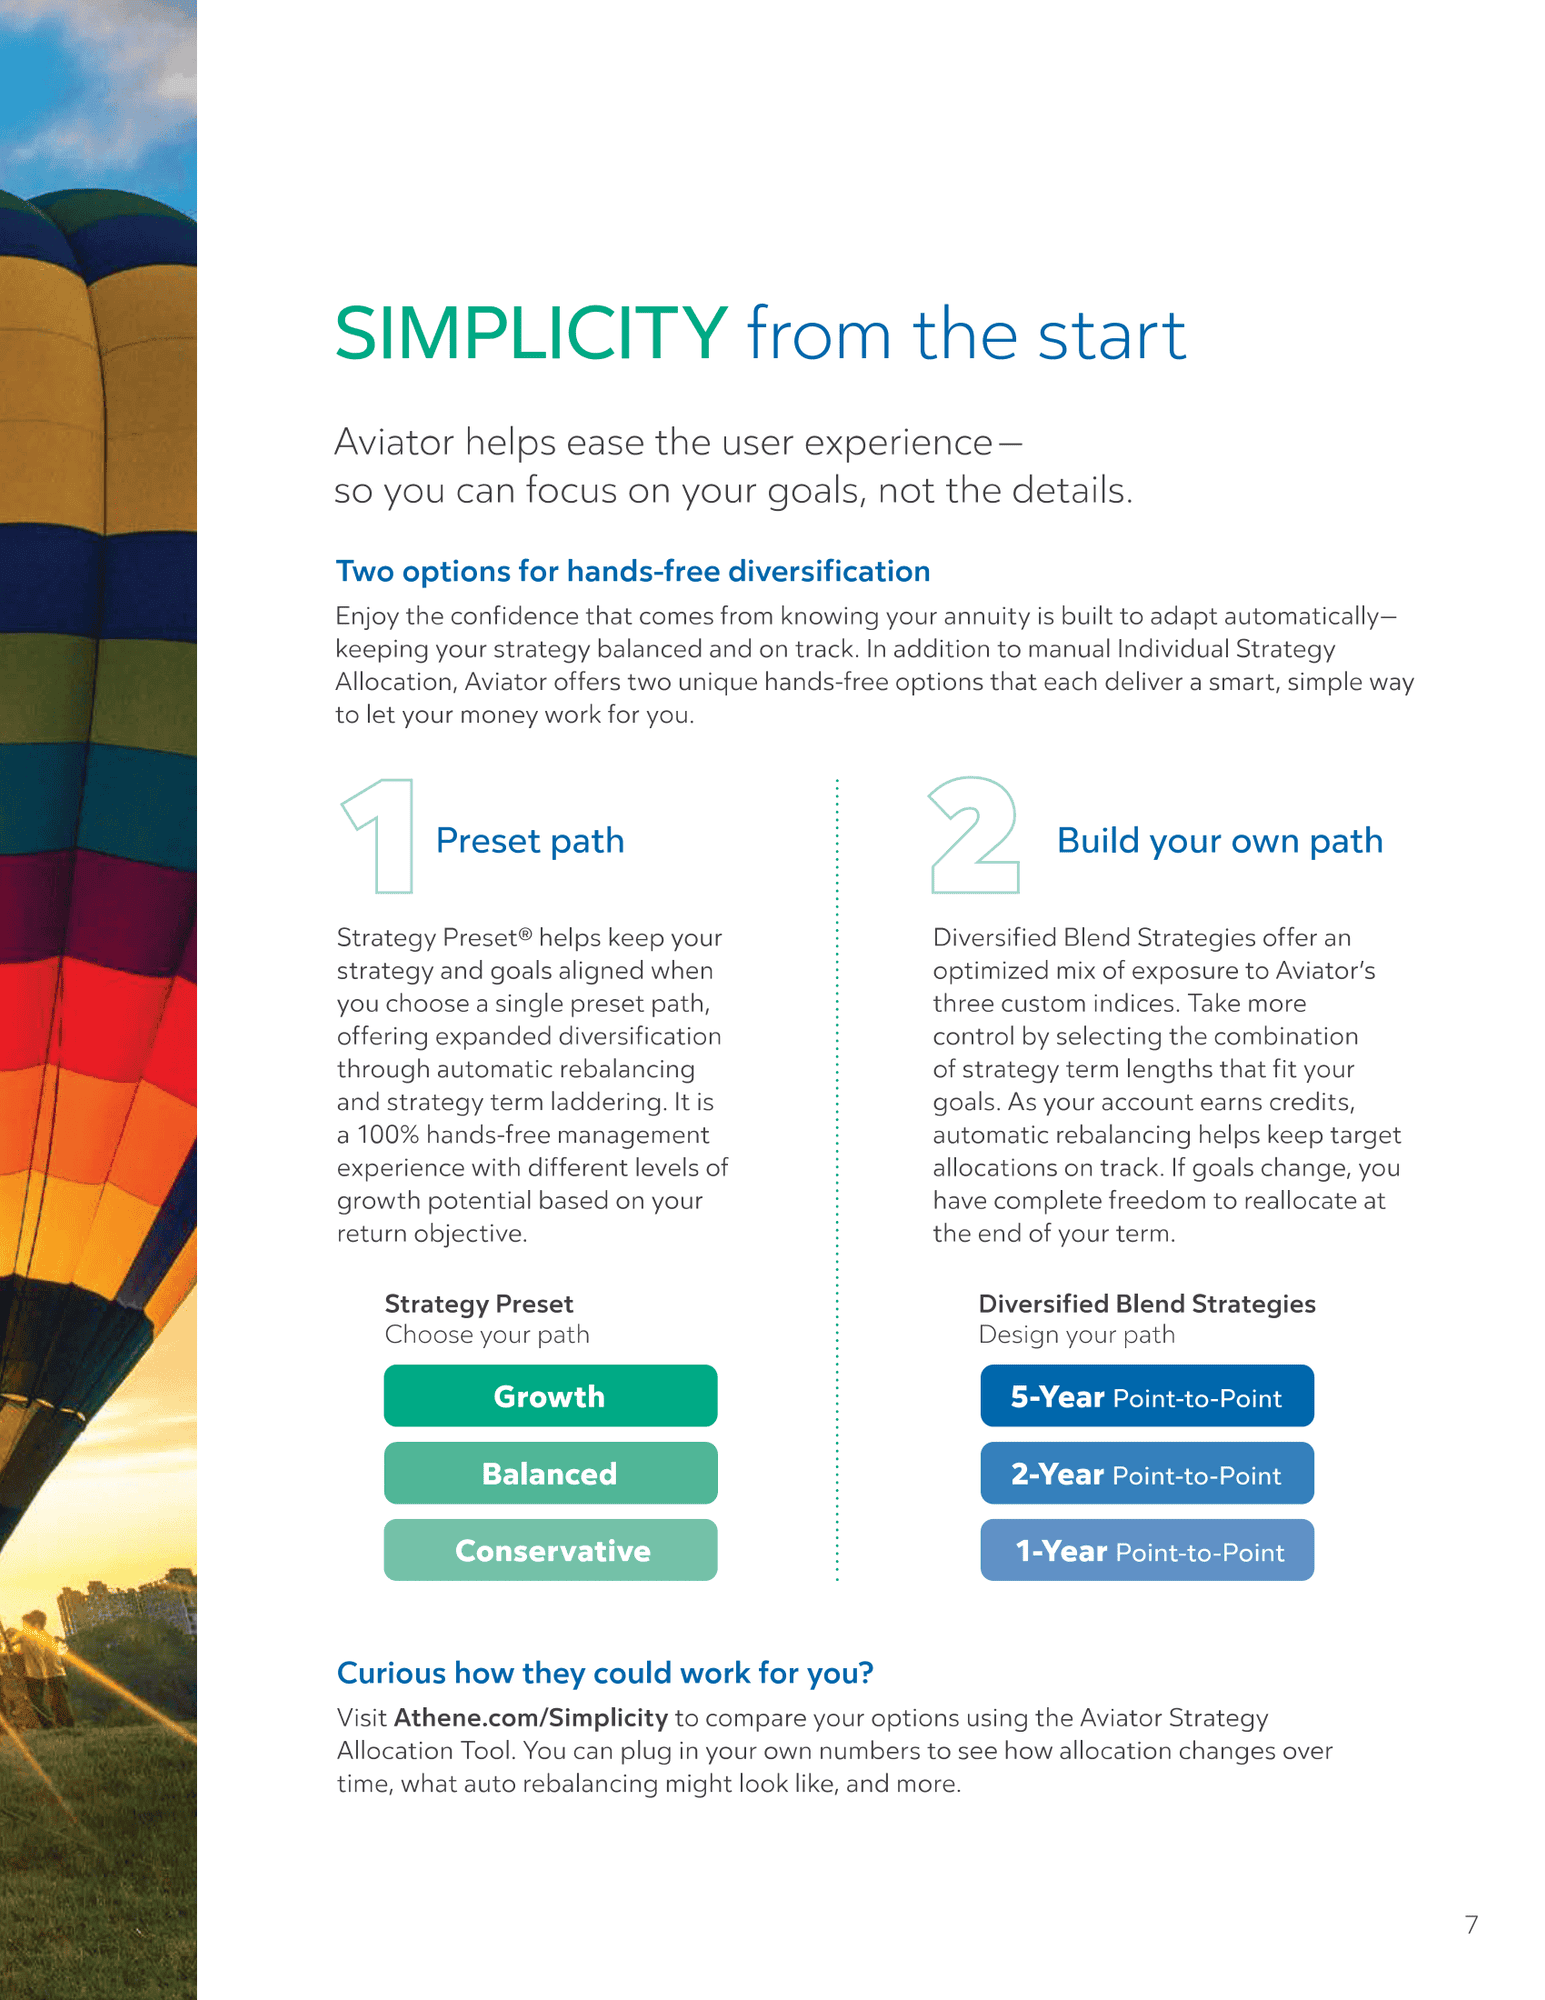
Interest is credited based on the performance of selected indexes rather than direct market investment. The annuity allows investors to allocate funds into multiple crediting strategies that may include participation-based and index-linked growth strategies. Some strategies are designed to automatically rebalance allocations, creating a diversified approach to indexed growth.
Aggressive Growth Strategy
Like some other FIAs designed for growth, Aviator can include strategies tied to uncapped S&P 500 participation structures with longer reset periods. These strategies aim to capture a significant portion of the stock market’s growth over longer cycles. By extending the reset period, insurers can often offer higher participation rates, allowing investors to capture a larger share of market performance.
Lock-In Feature
Some long reset strategies allow investors to lock in gains before the reset period ends. If the index reaches a strong level during the crediting period, the investor may choose to secure that gain.
- The gain becomes permanent
- The contract earns a fixed rate for the remaining reset term.
- A new strategy can be selected once the reset term completes
This feature can be helpful when markets rise quickly early in the reset period.
Pros and Cons
Pros
- Higher participation potential: Longer reset strategies allow stronger market participation.
- Principal protection: Market downturns do not reduce the contract value.
- Diversified strategies: Investors can spread funds across different index approaches.
- Tax-deferred growth: Interest compounds without annual taxation.
- Liquidity features: Annual free withdrawals are typically available after the first contract year.
Cons
- Longer reset periods: Investors may wait several years before interest is credited.
- Strategy complexity: Multiple strategies can make the product harder to understand.
- Engineered indexes: Some strategies rely on volatility-controlled indexes.
- Surrender charges: Liquidity is limited during early contract years.
Who Needs This Annuity
This annuity may work well for investors who:
- Want higher growth potential than conservative FIAs
- Are comfortable holding investments long term
- Want diversification across multiple index strategies
Who Does Not Need This Annuity
This product is not ideal for investors who:
- Want simple interest crediting
- Want annual crediting opportunities.
- Need frequent access to funds.
Athene Performance Elite Fixed Indexed Annuity
The Athene Performance Elite FIA is built for investors seeking stronger accumulation potential while maintaining principal protection. It includes both fixed interest and indexed crediting strategies.
How This Annuity Works
Interest can be credited through:
- Fixed interest account: Provides a declared annual interest rate.
- Indexed strategies: Interest is credited based on the performance of market indexes.
The contract guarantees that market losses will not reduce the contract value, meaning negative market years result in 0% crediting rather than losses.
Aggressive Growth Strategy
Like other growth-focused FIAs, some strategies allow participation in market indexes that may capture a large portion of stock market gains. These strategies often use longer crediting periods to support stronger upside potential. This structure allows investors to pursue growth while maintaining principal protection.
Pros and Cons
Pros
- Strong accumulation potential: Participation strategies may generate meaningful growth.
- Principal protection: Market downturns do not reduce account value.
- Tax-deferred compounding: Interest grows without annual taxation.
- Liquidity features: Annual penalty-free withdrawals are typically available.
Cons
- Strategy complexity: Indexed crediting methods can be difficult to understand.
- Renewal rate risk: Caps and participation rates may change after the initial term.
- Surrender periods: Early withdrawals may trigger charges.
- Engineered index exposure: Some strategies use proprietary indexes.
Who Needs This Annuity
This annuity may be appropriate for investors who:
- Want stronger accumulation potential than conservative annuities
- Want protection from market losses.
- Are investing with a long-term time horizon
Who Does Not Need This Annuity
This product is not ideal for investors who:
- Want short-term investments
- Need full liquidity
- Want full stock market participation.

Important Trade-Offs Aggressive Investors Should Understand
While high-participation indexed strategies can produce significantly stronger accumulation returns than basic fixed rate options or CDs, they still have limitations. Key trade-offs include:
- Caps and participation limits: You never receive the full stock market return.
- Longer reset periods: Interest may only be credited every five to seven years in aggressive strategies.
- Renewal rate risk: Future participation rates may change.
- Index complexity: Many FIAs rely on engineered indexes with limited performance history.
This is why we generally prefer strategies tied to traditional indexes like the S&P 500 that investors can easily track.
What Accounts Can Fund These Annuities
These annuities can be funded using:
- Cash (non-qualified money)
- Traditional IRA rollovers
- 401(k) rollovers
- 403(b) rollovers
- 457 plan rollovers
Tax-deferred retirement accounts remain tax-deferred when rolled into annuities.
Other Insurance That Can Protect Your Retirement Plan
Aggressive investors should also consider other insurance tools that protect their financial plan.
- Life insurance: Protects heirs and can replace wealth lost through annuitization.
- Long-term care insurance: Prevents healthcare costs from draining retirement savings.
- Disability insurance: Protects income before retirement.
These protections can help create a more resilient financial strategy.
Compare the Best Annuities With The Annuity Expert
Choosing the right annuity requires understanding the trade-offs between growth potential, income guarantees, and liquidity. The Annuity Expert helps investors:
- Compare annuities across multiple insurance companies
- Identify strategies with the strongest long-term potential
- Avoid gimmicks and misleading illustrations
- Build retirement income using GLWB riders if needed
Contact The Annuity Expert today to compare the best annuity options and find the best solution for your financial goals.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.