

What You’ll Learn In Minutes
This guide helps you diagnose whether inflation is quietly lowering your purchasing power and retirement security. You’ll get clear warning signs, simple tests you can run today, and a short list of proven fixes. At The Annuity Expert, we’re an independent annuity broker and insurance agency—when you’re ready, we can compare MYGA and FIA with a GLWB quotes and map a tax-smart income plan.
Fast Diagnosis: 9 Signs Inflation Is Draining Your Wealth
Use these as a checklist. If you see 3+ signs, it’s time to adjust.
1) Your cash yield < last year’s inflation
- What to check: Look up your savings/HYSA rate and compare it to last year’s inflation.
- Why it matters: If your after-tax yield is lower, your cash is losing buying power.
- First-time tip: Keep 6–12 months in cash; don’t let long-term dollars sit there.
2) Your portfolio’s long-run return ≈ inflation
- What to check: Your 5–10 year average return vs. average inflation.
- Why it matters: Real (after-inflation) returns near zero won’t fund rising expenses.
- First-time tip: Growth assets fight inflation; pair them with guardrails (see fixes).
3) Your spending plan is “flat”
- What to check: Do you inflate your retirement budget every year?
- Why it matters: A static $80,000 target buys less each year.
- First-time tip: Add an annual inflation bump to your plan and re-price big items.
4) Your withdrawal rule never changes
- What to check: Are you still using a fixed 4% rule in volatile markets?
- Why it matters: In down years, that may force selling low.
- First-time tip: Use a spending “ceiling and floor” so withdrawals adjust.
5) Healthcare is crowding out everything else
- What to check: Share of budget going to premiums, meds, and out-of-pocket costs.
- Why it matters: Healthcare often inflates faster than the headline rate.
- First-time tip: Review Medigap/MA plans and consider HSA funding (if eligible).
6) Taxes are rising faster than income
- What to check: Effective tax rate vs. last year, RMD projections, IRMAA exposure.
- Why it matters: Higher taxes during inflation further cut real income.
- First-time tip: Blend Roth conversions before RMD age and manage bracket creep.
7) Your “income floor” depends on markets
- What to check: Could a bear market cut the paycheck you draw from investments?
- Why it matters: Selling more shares at lower prices amplifies inflation damage.
- First-time tip: Add guaranteed income so your baseline spending stays intact.
8) Big future goals aren’t re-priced
- What to check: Have you updated travel, car, or remodel budgets for today’s prices?
- Why it matters: Under-budgeting forces larger withdrawals later.
- First-time tip: Re-quote major goals annually and phase them over several years.
9) Cash flow “feels tight” despite similar income
- What to check: Are you dipping into savings more often for the same lifestyle?
- Why it matters: That’s real-world proof that your money buys less.
- First-time tip: Track a rolling 90-day spend to see where inflation bites.
Quick Score: Are You At Risk?
- 0–2 signs: Low risk—tune up annually
- 3–5 signs: Moderate risk—implement 1–2 fixes now
- 6+ signs: High risk—rebuild your income, tax, and cash buffers promptly
Proven Moves To Fight Inflation (Short List)
MYGA ladder for 3–7 years of spending
- What it is: Multi-Year Guaranteed Annuities (MYGAs) pay a fixed, guaranteed rate for a set term; stagger terms so one matures each year to cover spending.
- Why it helps: Locks in guaranteed rates to fund near-term expenses so you don’t sell stocks in down markets.
- Pros: Predictable interest; tax-deferred growth; reduces sequence risk
- Cons: Surrender charges beyond free-withdrawal amounts
- Who benefits: Retirees within 7 years of spending needs
- Who doesn’t: Those needing full liquidity beyond free amounts
- Related solutions to compare: Short-term Treasuries, T-bill ladders, or investment-grade CDs for cash under 3 years.
Social Security delay strategy
- Why it helps: Larger, COLA-adjusted benefit offsets inflation.
- Pros: Higher lifetime base income
- Cons: Requires a bridge (cash/MYGA or FIA)
- Who benefits: Healthy retirees with longevity
- Who doesn’t: Shorter life expectancy or immediate cash need
Roth conversions and HSA coordination
- Why it helps: Lowers future tax drag and IRMAA risk as prices rise.
- Pros: Tax-free Roth withdrawals; HSAs’ triple tax advantage
- Cons: Current-year taxes on conversions; HDHP needed for HSA
- Who benefits: Pre-RMD households in moderate tax brackets
- Who doesn’t: Top-bracket filers this year
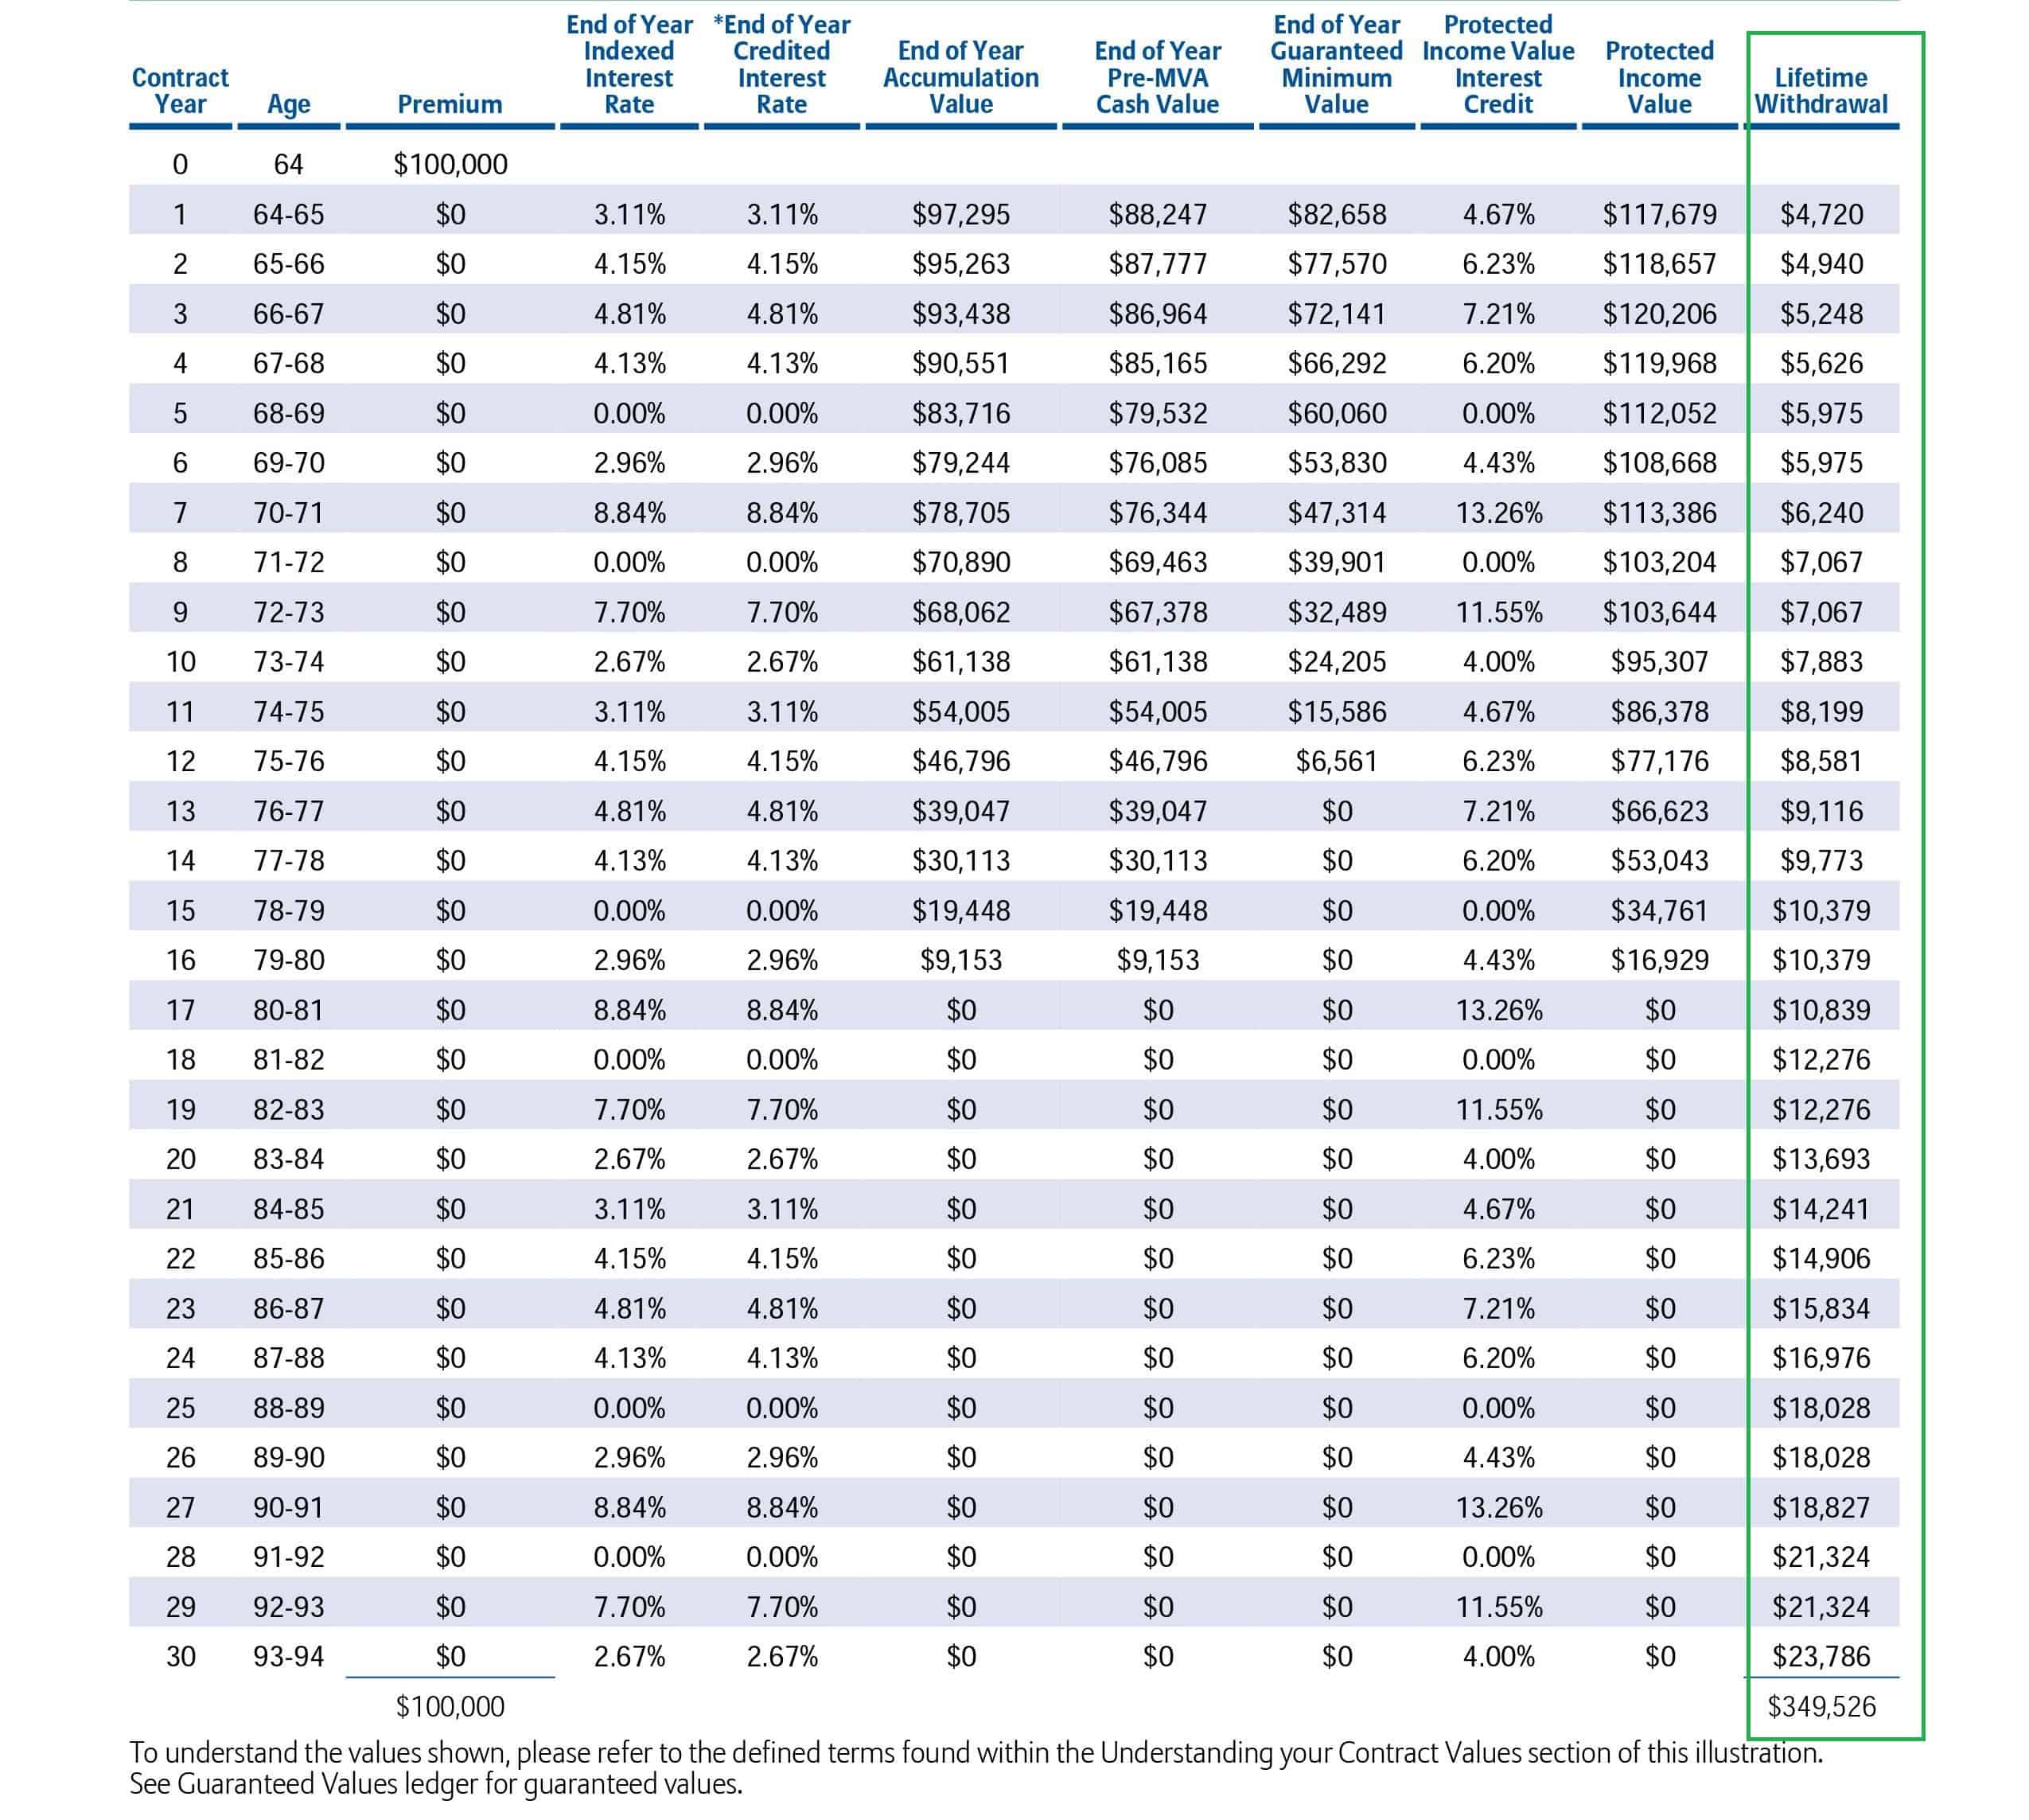
FIA with GLWB for a lifetime paycheck
- What it is: A Fixed Index Annuity with a Guaranteed Lifetime Withdrawal Benefit creates income for life—regardless of market performance.
- Why it helps: Builds a market-proof income floor; optional inflation riders available.
- Pros: Income for life; principal protection; steadier cash flow
- Cons: Rider fees; upside capped vs. equities
- Who benefits: Retirees wanting a durable baseline income
- Who doesn’t: Households already covered by strong pensions
- Loophole to consider: A 1035 exchange from an underperforming annuity into a modern FIA with a GLWB can upgrade features without current taxes.
Keep an equity engine with guardrails
- Why it helps: Long-term growth to outrun inflation without panic selling.
- Pros: Higher real return potential
- Cons: Volatility requires discipline
- Who benefits: Investors with cash/MYGA buffers and an income floor
- Who doesn’t: Those spending principal in the next 1–3 years
- Guardrails to compare: 10% free withdrawals from annuities; ceiling-and-floor spending rules; annual rebalancing to refill the cash/MYGA bucket.
What To Do Next (First-Time Reader Roadmap)
- Count your signs: Tally exposures from the checklist above.
- Build buffers: 6–12 months in cash + a 3–7 year MYGA ladder.
- Add a lifetime income floor: Size an FIA with GLWB to essential bills.
- Map taxes: Partial Roth conversions before RMD age; watch IRMAA brackets.
- Keep growth: Maintain equities, rebalance yearly, and use withdrawal guardrails.
How We Help You Compare Real Options
Share your age, balances, income target, and timelines. We’ll compare MYGA rates for your ladder, shop FIA with a GLWB income quotes, and outline a tax-smart withdrawal order you can follow—seeing pros, cons, costs, and fit before you move forward.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.