

Should you invest in the stock market or protect your money with an annuity?
Who We Are
The Annuity Expert is an independent annuity brokerage, insurance agency, and retirement planner. We help you compare annuities from A-rated (or better) insurers, explain trade-offs in plain English, and find the lowest-cost path to your goal.
The Big Picture: Annuities vs. Stocks
Before drilling down into MYGAs, FIAs, and Variable Annuities, here’s the overall comparison:
| Factor | Annuities | Stocks |
|---|---|---|
| Primary Role | Income, protection, tax deferral | Long-term growth, wealth building |
| Principal Risk | Protected in MYGAs/FIAs; exposed in VAs | Fully exposed to market risk |
| Lifetime Income | Yes (GLWB or annuitization) | No |
| Volatility | Low to moderate | High |
| Liquidity | Limited by surrender schedules | Fully liquid |
| Taxes | Tax-deferred; gains taxed as ordinary income | Capital gains/dividends annually (favorable rates possible) |
Quick takeaway: Annuities provide stability and income guarantees. Stocks provide higher long-term growth. Most retirees benefit from a mix of both.

MYGAs vs. Stocks
MYGAs (Multi-Year Guaranteed Annuities): Contractually guaranteed fixed interest for a term, with principal protection and tax deferral.
Stocks: Equity ownership with full volatility but unlimited upside.
| Factor | MYGAs | Stocks |
|---|---|---|
| Risk | Principal guaranteed | Full downside |
| Returns | Fixed rate for term | Unlimited upside |
| Liquidity | Limited; surrender penalties apply | Fully liquid |
| Taxes | Tax-deferred | Dividends/cap gains taxed annually |
| Best For | CD alternatives, retirement stability | Growth-oriented investors |
Who Needs MYGAs: Age 50+, conservative savers, and retirees wanting predictable growth.
Who Doesn’t: Younger investors seeking higher growth and full liquidity.
FIAs vs. Stocks
FIAs (Fixed Indexed Annuities): Earn interest based on an index (like the S&P 500) with no market losses to principal. Growth limited by caps or participation rates. Includes a declared fixed rate option each year.
Stocks: Unlimited growth potential but full exposure to downturns.
| Factor | FIAs | Stocks |
|---|---|---|
| Risk | Principal protected | Full downside |
| Returns | Index-linked, capped | Unlimited |
| Liquidity | Limited; partial penalty-free withdrawals | Fully liquid |
| Income | Optional GLWB riders for lifetime income | Must self-manage withdrawals |
| Taxes | Tax-deferred | Favorable capital gains/dividends rates |
| Best For | Pre-retirees/retirees seeking safe growth + income | Growth investors who can stomach volatility |
Who Needs FIAs: People 5–10 years from retirement worried about market downturns.
Who Doesn’t: Younger accumulators who want uncapped growth.

Variable Annuities vs. Stocks
Variable Annuities (VAs): Market-based annuities using sub-accounts. Values fluctuate with the market. Riders can add income guarantees but fees are high.
Stocks: Direct, low-cost ownership of funds or individual companies.
| Factor | Variable Annuities | Stocks |
|---|---|---|
| Risk | Market risk; value fluctuates | Market risk |
| Returns | Market-based, reduced by fees | Unlimited upside |
| Fees | High (M&E, admin, riders) | Low (fund expense ratios) |
| Income Options | GLWB riders for guaranteed lifetime income | None |
| Liquidity | Limited; surrender penalties apply | Fully liquid |
| Taxes | Tax-deferred; ordinary income on withdrawals | Favorable capital gains/dividends |
| Best For | Investors needing market exposure + income guarantees | Pure growth investors seeking efficiency |
Who Needs VAs: High-income households needing both tax deferral and guaranteed income.
Who Doesn’t: Cost-conscious investors who can achieve the same exposure with ETFs or mutual funds.
Where Annuities Win
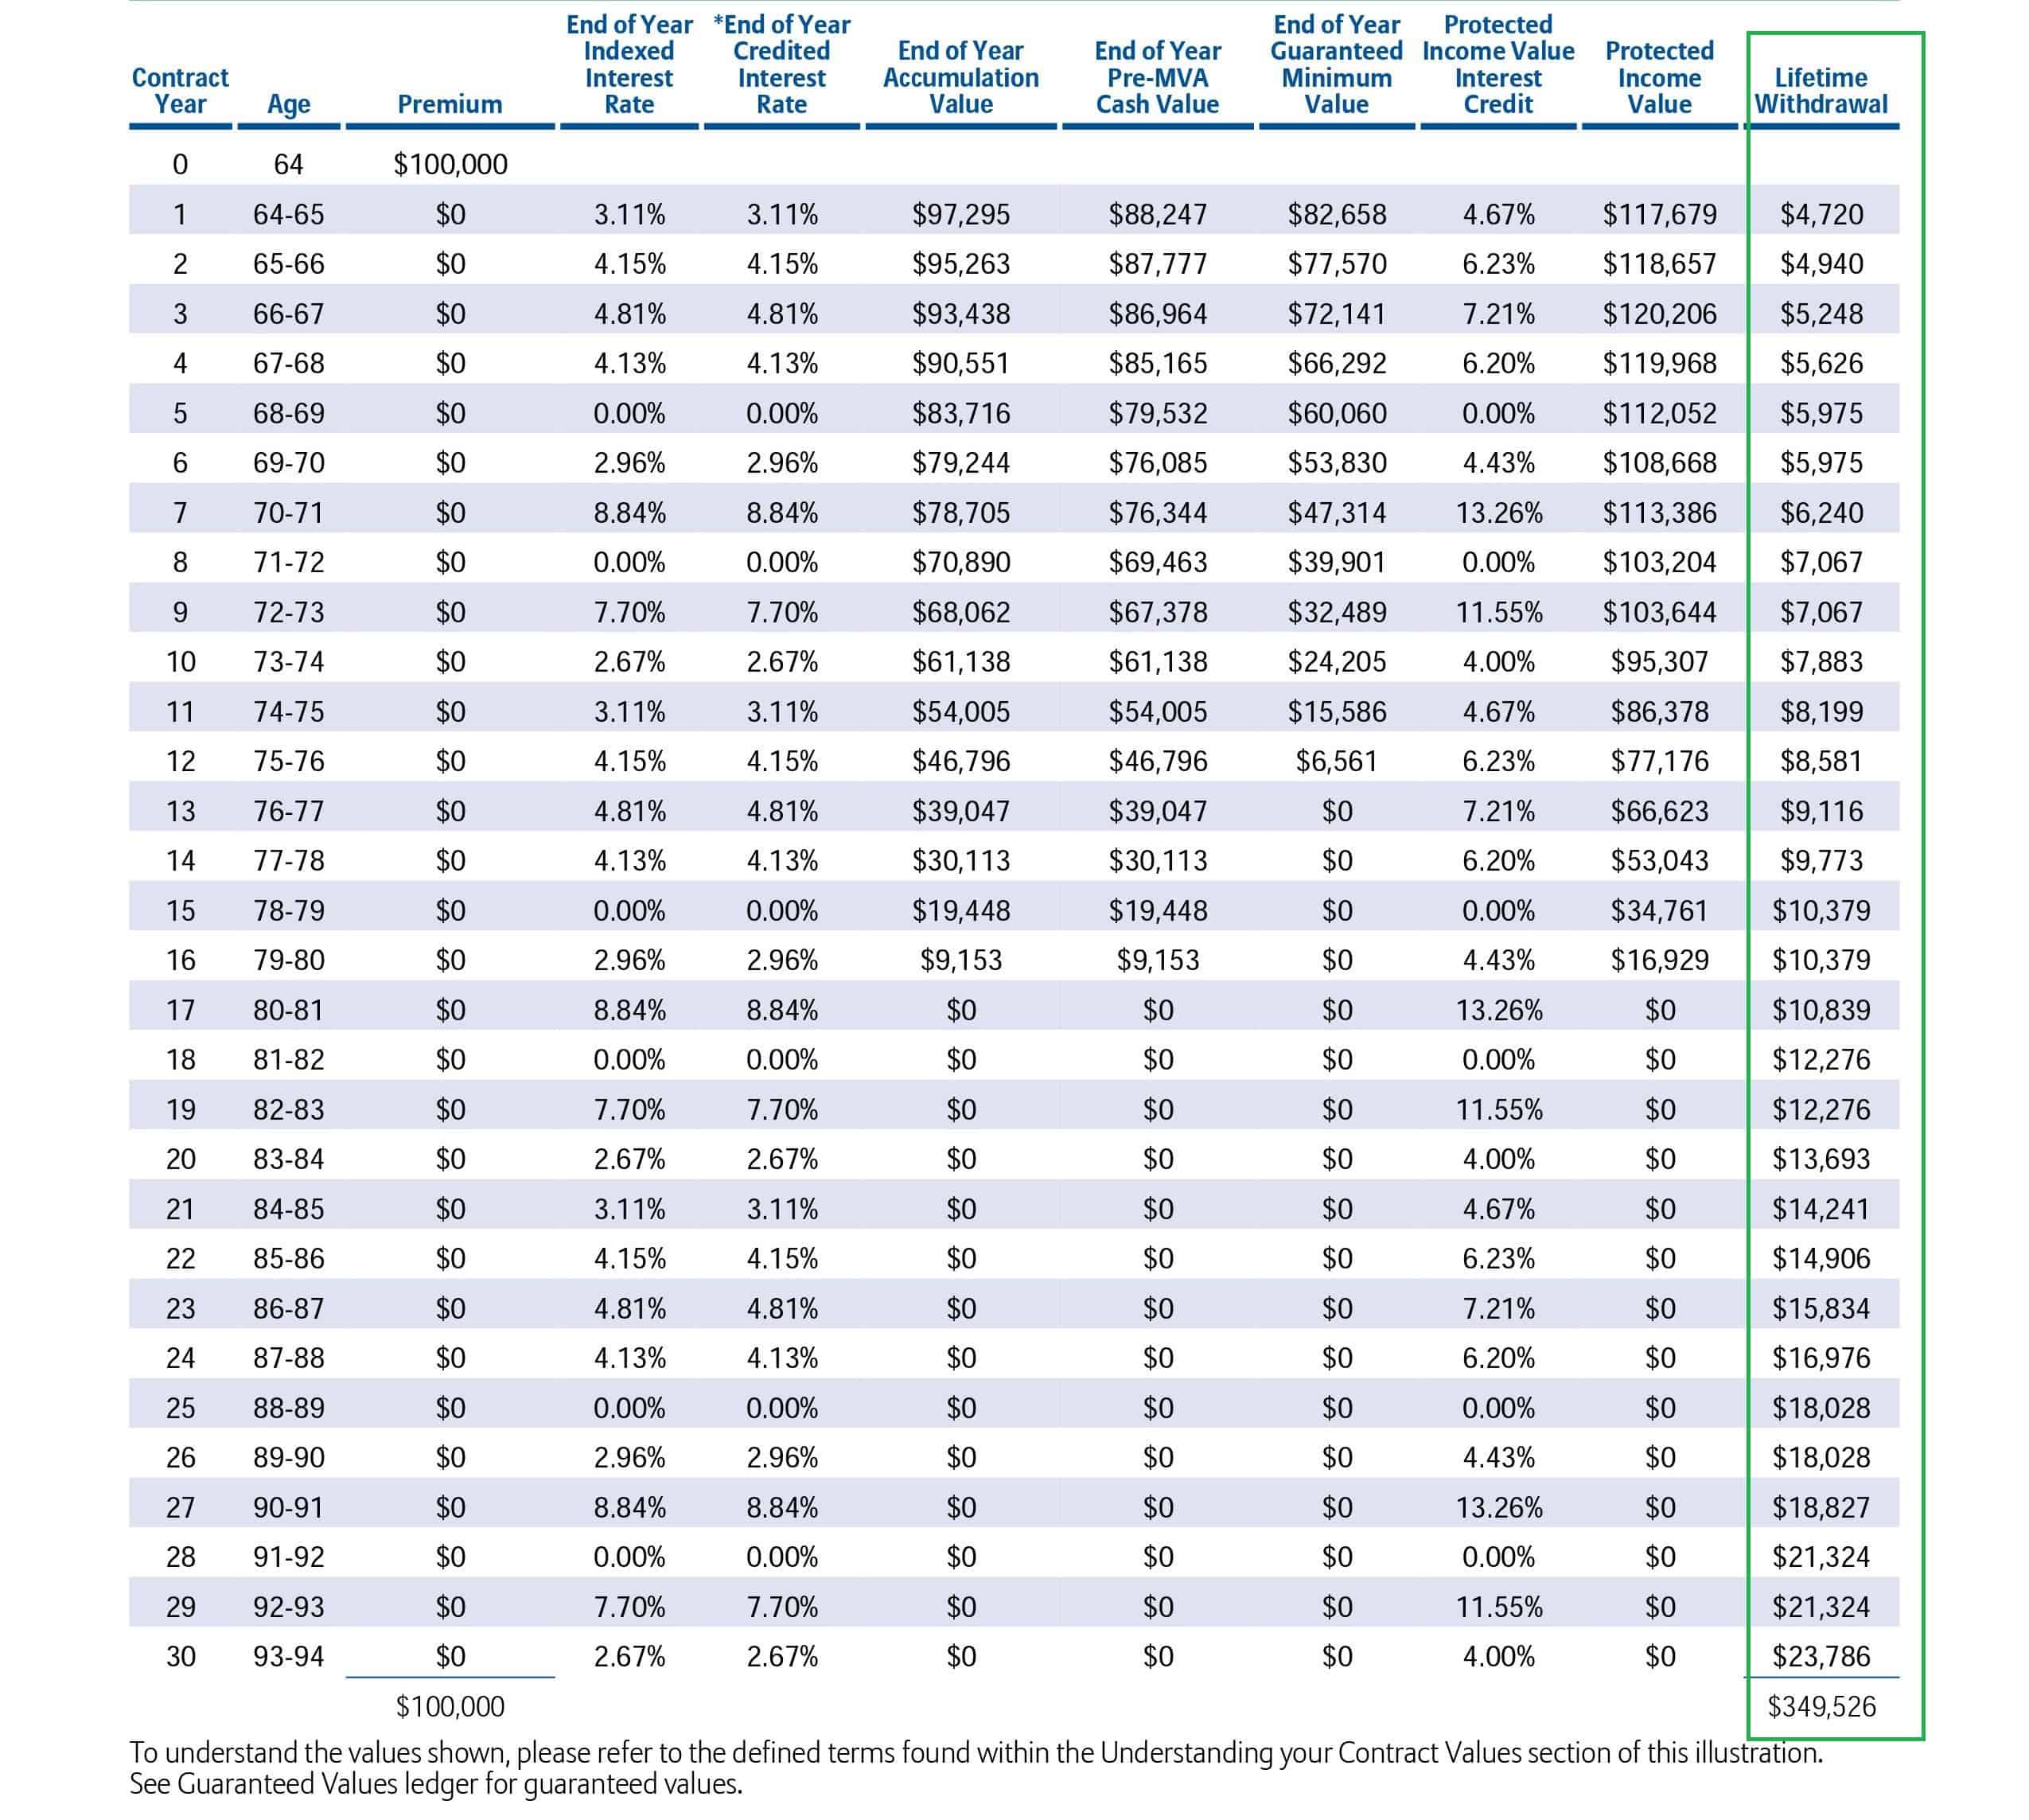
- Contractually guaranteed lifetime income with GLWBs or SPIAs.
- Principal protection in MYGAs and FIAs.
- Tax deferral in non-qualified accounts.
- Behavioral guardrails that prevent panic selling.
Where Stocks Win
- Unlimited upside over long horizons.
- Full liquidity and no surrender schedules.
- Preferential tax treatment on long-term gains and dividends.
- Low structural costs with ETFs and index funds.
Straight Talk: Our Recommendations
- For guaranteed income: Start with an FIA + GLWB; compare to a SPIA only if income must start now.
- For safe accumulation: Use MYGAs or the FIA fixed account as a CD or bond alternative.
- For growth: Use stocks as your main engine, but pair them with annuities for stability and retirement income.
- Avoid annuitization unless necessary: GLWBs keep income flexible and preserve beneficiary value, while annuitization is irreversible.
- Work with a broker, not direct with carriers: Brokers compare multiple insurers; direct buyers lose that leverage.

Other Insurance We Offer That Can Help
- Long-Term Care Insurance: Protects annuity/stock assets from care costs.
- Disability Insurance: Protects your income before retirement.
- Life Insurance: Provides tax-free legacy and pairs with annuities for early retirement strategies.
Call to Action
Contact The Annuity Expert for free quotes to buy, compare, or blend annuities with stocks. We’ll shop A-rated carriers, explain every trade-off, and help you choose the smartest way to balance growth, protection, and income.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
Are annuities considered securities?
The classification of annuities as securities depends on their structure. Variable annuities and guaranteed returns or earnings based on a specified index, without direct market investment, are primarily regulated by state insurance commissioners.
Is an annuity better than stocks for retirement?
Neither is better in every case. Annuities provide stability and income guarantees, while stocks provide growth. Many retirees need both.
How are annuities taxed compared to stocks?
Annuities grow tax-deferred, but withdrawals are taxed as ordinary income. Stocks can qualify for lower long-term capital gains rates.
Should I annuitize or use a GLWB?
We recommend GLWBs because income is revocable and you maintain control. Annuitization is permanent.
Can an annuity replace bonds?
Yes. MYGAs and FIAs often serve as bond alternatives, while GLWBs or SPIAs provide predictable income streams.
Will an annuity keep up with inflation?
Not fully. Some riders adjust income, and FIAs can benefit from index growth, but stocks and TIPS are better inflation hedges.
Can I move money from stocks into an annuity without paying taxes?
Yes, if done inside an IRA or via a 1035 exchange from another annuity. In taxable accounts, selling stocks may trigger capital gains.
Are annuities FDIC-insured like bank CDs or brokerage accounts?
No. Annuities are backed by insurance carriers and state guaranty associations, not FDIC.
Do I lose control of my money in an annuity?
Not with GLWBs—you can stop income and keep account control. Annuitization, however, is permanent.