

Solving Retirement Challenges: The Best Annuities for Baby Boomers
Baby Boomers are entering retirement with a different set of challenges than previous generations. Many no longer have traditional pensions, and Social Security alone often falls short of covering living expenses. Healthcare costs are rising, and market volatility can permanently damage retirement savings. Clarifying how each annuity can help mitigate these issues will guide Baby Boomers in selecting suitable options.
The solution for many retirees is building a personal pension system using multiple annuities designed for different financial goals. Each annuity solves a different retirement risk:
- Safe growth
- Lifetime income
- Inflation protection
- Required Minimum Distributions (RMDs)
- Long-term care costs
- Legacy planning
Below are several annuities that stand out for Baby Boomers, depending on what problem they are trying to solve.
Oceanview CapLock Fixed Indexed Annuity
Best annuity for safe growth without market losses
Many Baby Boomers nearing retirement want growth but cannot afford market losses. The Oceanview CapLock fixed indexed annuity is designed for conservative to moderate investors who want market-linked growth while protecting their principal. This annuity has become popular because of its simplicity and transparency.
How This Annuity Works
CapLock is a fixed indexed annuity (FIA) that offers:
- Principal protection: Your account cannot lose money due to market declines.
- Market-linked growth potential: Interest is based on index performance.
- A fixed cap for the entire surrender period: The cap rate remains stable instead of resetting every year.
This structure eliminates one of the biggest risks in FIAs—declining renewal caps.
Why We Like It
We like this annuity because it uses traditional and transparent market indexes rather than engineered indexes. That means investors can easily follow the performance of the indexes on financial news networks instead of trying to understand proprietary indexes that few people track. We also like the product’s simplicity. There are fewer gimmicks, fewer engineered indexes, and a straightforward growth structure.
- Pros
- Principal protection from market losses
- Predictable cap rates for the surrender period
- Tax-deferred growth
- Traditional index exposure
- Simple structure with minimal gimmicks
- Cons
- Growth is capped
- Surrender period limits liquidity
- Does not provide a guaranteed lifetime income unless paired with an income rider
Who Needs This Annuity
- Baby Boomers who:
- Want safe growth before retirement
- Want protection from stock market losses.
- Want a simple FIA without complex engineered indexes.
- Who Does Not Need It
- Investors who:
- Want aggressive market exposure
- Need immediate income
- Want full stock market returns.

Nationwide Peak 10 Fixed Indexed Annuity
Best annuity for guaranteed lifetime income
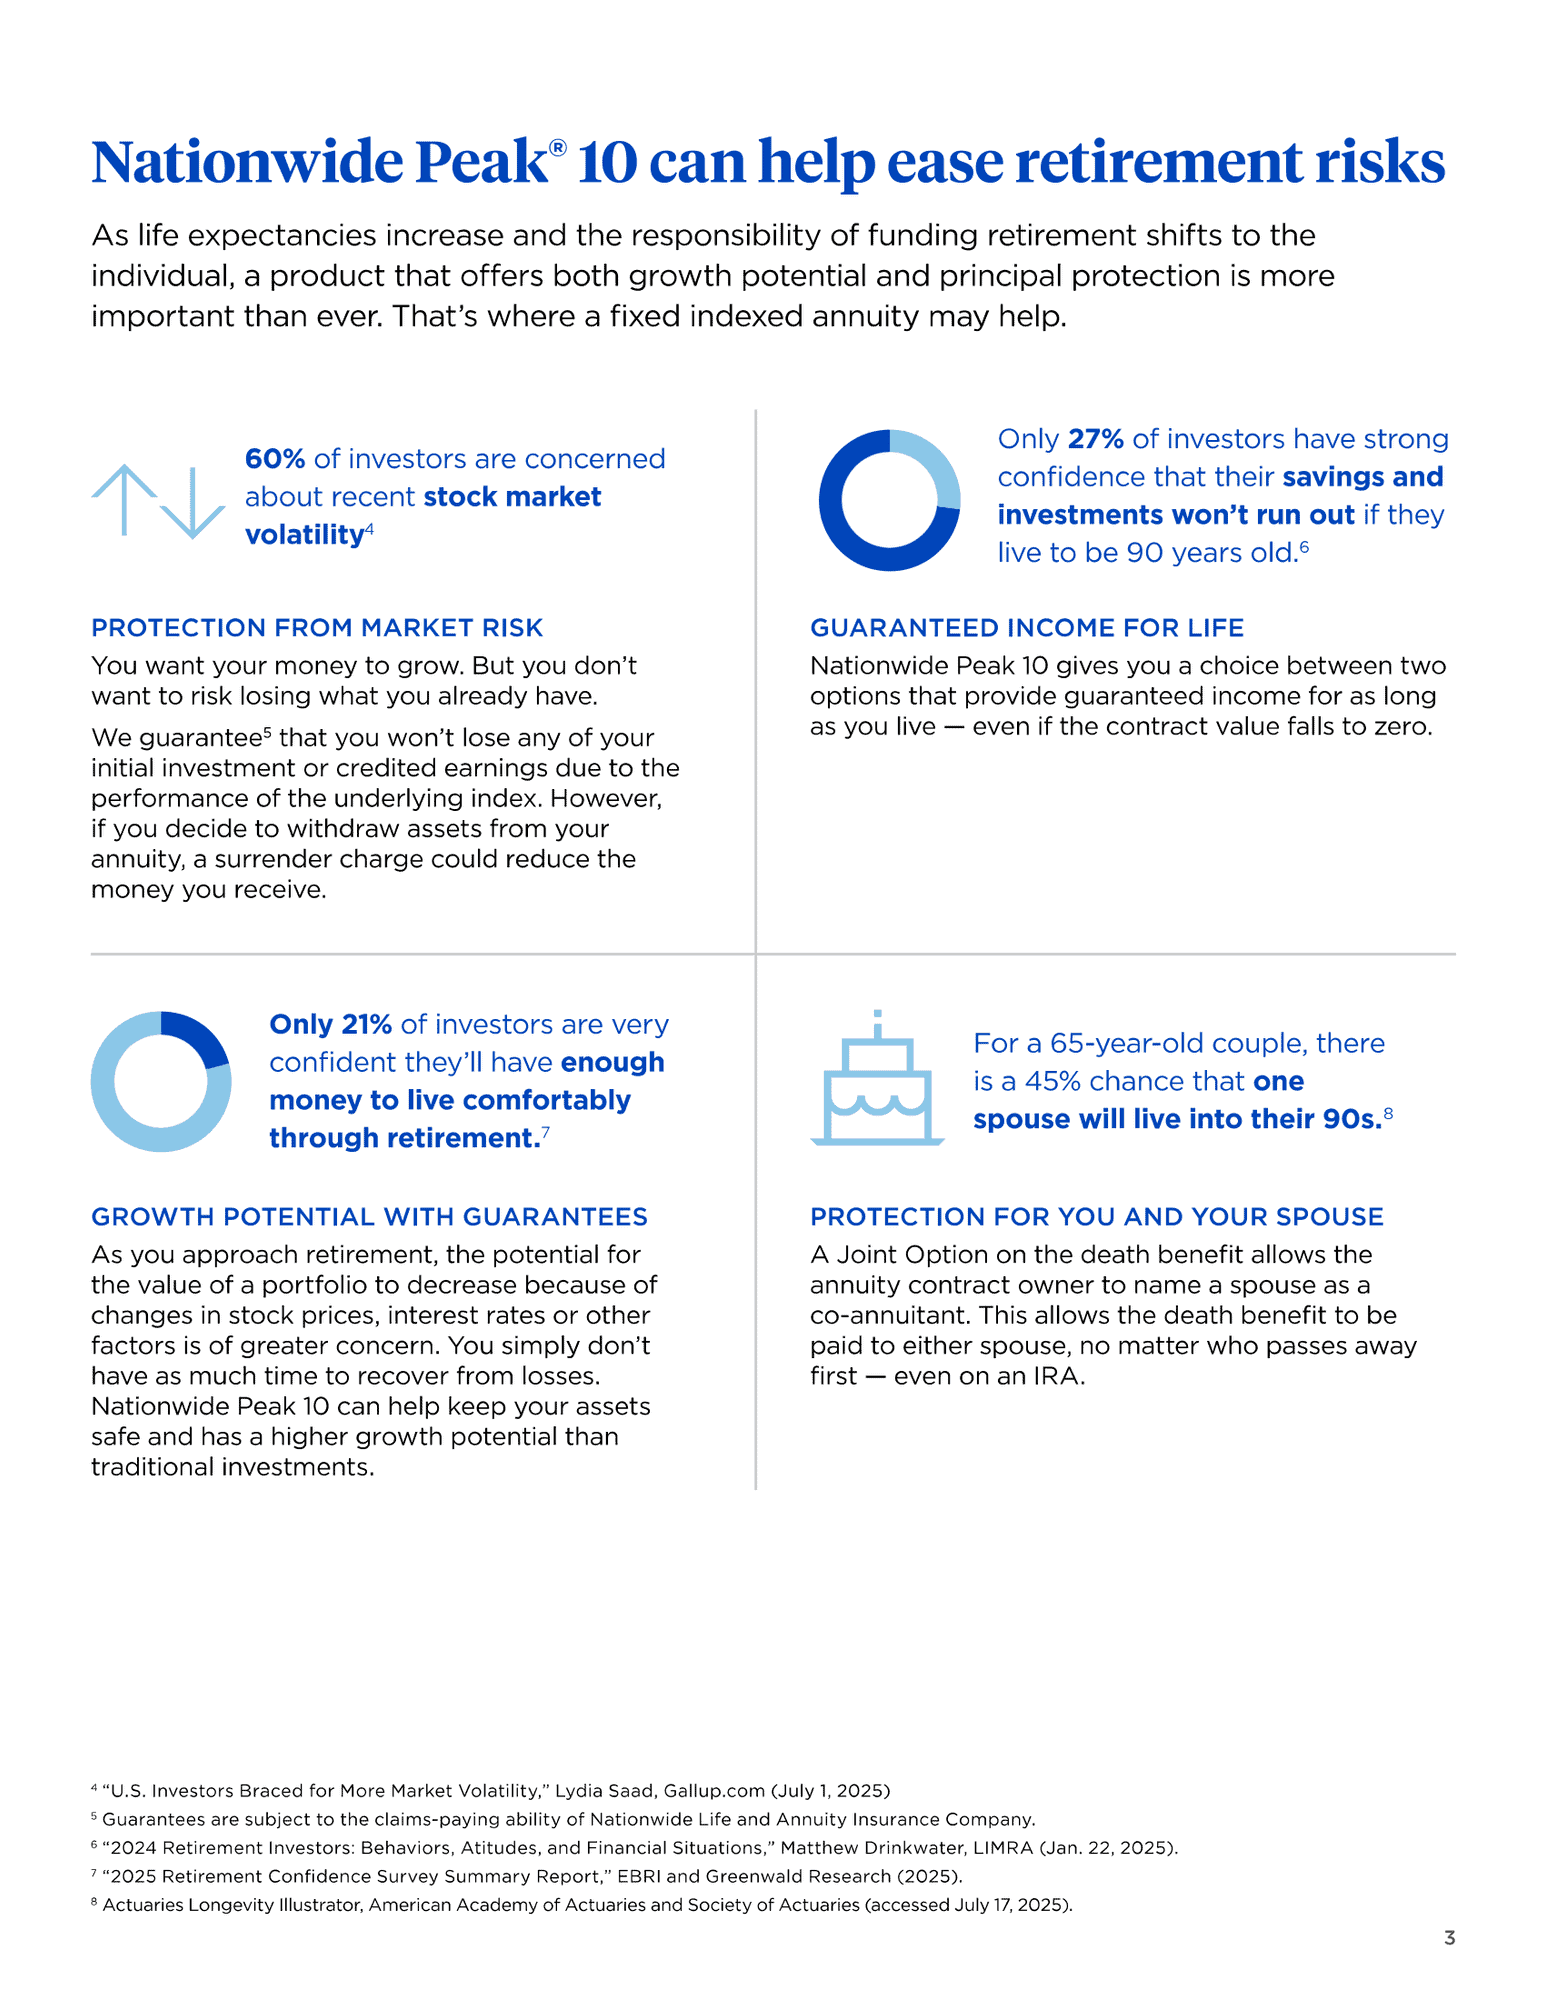
The Nationwide Peak 10 FIA is one of the strongest annuities for Baby Boomers whose primary goal is creating a personal pension that lasts for life. The sweet spot for this annuity is joint lifetime income for couples.
How This Annuity Works
This annuity includes a Guaranteed Lifetime Withdrawal Benefit (GLWB) rider. The GLWB allows you to withdraw income for life even after the account value reaches zero. The contract tracks a separate income benefit base, which grows over time to determine future income payments. If the index strategies perform well, the benefit base can grow faster, which increases future income.
Why We Like It
We like the joint life income power this annuity provides. For married couples, the payout can continue for as long as either spouse is alive. We also like that strong growth years can significantly increase the income base, which can raise future lifetime income.
- Pros
- Guaranteed lifetime income through the GLWB
- Strong joint life payouts
- Potential for increasing income after strong growth years
- Principal protection from market losses
- Tax-deferred growth
- Cons
- Income riders include fees
- Caps limit upside potential
- Surrender period limits liquidity
Who Needs This Annuity
- Baby Boomers who:
- Want pension-like income for life
- Want income protection for a surviving spouse.
- Want flexibility instead of irreversible annuitization
- Who Does Not Need It
- Investors who:
- Only want accumulation
- Need full liquidity
- Want maximum market exposure.
Athene Ascent Pro 10 Bonus
Best annuity for increasing lifetime income that helps keep up with inflation
One of the biggest fears for Baby Boomers is inflation eroding retirement income. The Athene Ascent Pro 10 Bonus FIA addresses this problem with increasing lifetime income options.
How This Annuity Works
This annuity includes a GLWB rider that offers several income structures. These typically include:
- Level income: Payments remain constant.
- Increasing income: Payments can rise over time based on account growth.
Increasing income riders are designed to help retirement income keep pace with inflation.
- Pros
- Increasing lifetime income potential
- Principal protection
- Tax-deferred growth
- Bonus options available
- Cons
- Rider fees reduce accumulation
- Growth caps limit upside potential
- Surrender period applies
Who Needs This Annuity
- Baby Boomers who:
- Want a lifetime income that can increase
- Are concerned about inflation
- Want income flexibility
- Who Does Not Need It
- Investors who:
- Want pure accumulation
- Want full market participation.

Athene Agility
Best annuity for managing Required Minimum Distributions (RMDs)
Many retirees face a unique problem when RMDs begin. They are forced to withdraw money from retirement accounts even when they do not need the income. The Athene Agility annuity is designed to help solve that problem.
How This Annuity Works
Athene Agility includes features designed to help retirees manage RMD withdrawals from qualified retirement accounts. This allows retirees to take required withdrawals while keeping the remainder of their assets invested in a tax-deferred annuity. The annuity can be used as a vehicle to spend RMDs gradually while preserving the remaining retirement savings.
- Pros
- Helps manage RMD withdrawals
- Tax-deferred growth
- Principal protection
- Liquidity options
- Cons
- Growth is limited compared to market investments
- Surrender charges apply
Who Needs This Annuity
- Baby Boomers who:
- Must take RMDs, but do not need the income
- Want to reposition retirement assets safely.
- Want tax-deferred growth on remaining funds.
- Who Does Not Need It
- Investors who:
- Do not yet face RMD requirements
- Need aggressive growth

Global Atlantic ForeCare
Best annuity for long-term care protection
Healthcare costs are one of the biggest financial risks in retirement. The Global Atlantic ForeCare annuity is designed specifically to address long-term care expenses.
How This Annuity Works
This product is a long-term care annuity that 2x or 3x your investment to pay for a nursing home, assisted living, or home health care. The contract provides a pool of funds that can be used for long-term care expenses, such as:
- Nursing homes
- Assisted living
- Home health care
Many LTC annuities can multiply the value of the contract for care costs, often doubling or tripling the available benefit.
- Pros
- Funds specifically dedicated to long-term care
- May multiply the value of the annuity for care costs
- Principal protection
- Tax advantages for qualified LTC benefits
- Cons
- Limited flexibility if care is never needed
- Lower growth potential
Who Needs This Annuity
- Baby Boomers who:
- Want protection from nursing home costs
- Want a dedicated LTC funding strategy.
- Want guaranteed LTC benefits.
- Who Does Not Need It
- Investors who:
- Already have comprehensive long-term care coverage
- Do not want funds restricted for healthcare use.

Athene Agility for Enhanced Death Benefits
Best annuity for enhanced death benefits
Many Baby Boomers want to leave money to their children or grandchildren. The Athene Agility annuity can be used to provide enhanced death benefit features.
How This Annuity Works
Some versions of the annuity include enhanced death benefit riders that can increase the value passed to beneficiaries, up to 55%, starting immediately. Annuities also avoid probate when beneficiaries are named.
- Pros
- Enhanced inheritance potential
- Probate avoidance
- Principal protection
- Tax-deferred growth
- Cons
- Enhanced death benefit has to be taken over a 5-year period and not a lump sum
- Growth caps limit upside potential
Who Needs This Annuity
- Baby Boomers who:
- Want to leave money to heirs
- Want predictable inheritance outcomes
- Who Does Not Need It
- Investors who:
- Do not prioritize legacy planning
Building a Retirement Income System
Many Baby Boomers combine multiple annuities to solve different retirement risks. A common structure may include:
- Growth annuity: Oceanview CapLock
- Income annuity: Nationwide Peak 10
- Inflation-adjusted income: Athene Ascent Pro
- RMD management: Athene Agility
- Healthcare protection: Global Atlantic ForeCare
- Legacy planning: Athene Agility
Once guaranteed income needs are covered, any remaining retirement funds can be invested or used for lifestyle spending.
Other Insurance Baby Boomers Should Consider
Annuities are only one part of retirement protection. Other insurance solutions can help protect retirement plans.
- Life insurance: Protects spouses and heirs.
- Long-term care insurance: Protects retirement savings from healthcare costs.
- Medigap coverage: Helps cover short-term medical expenses in retirement.
Combining these protections can create a stronger retirement strategy.
Compare the Best Annuities for Baby Boomers
Choosing the right annuity depends on your retirement goals, income needs, health concerns, and legacy plans. The Annuity Expert helps Baby Boomers:
- Compare annuities across top insurance companies
- Identify the strongest income riders
- Avoid engineered index strategies
- Build retirement income systems that last for life
Contact The Annuity Expert today to compare annuity quotes and find the best annuity for your retirement strategy.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.