

Why Women Need Stronger Longevity Planning
Women generally live longer than men, which means their retirement savings must last longer. According to longevity statistics, women frequently spend more years in retirement, which increases the risk of running out of money.
Because of this longevity gap, retirement planning for women often requires guaranteed lifetime income strategies that protect assets and generate dependable cash flow.
A Fixed Indexed Annuity with a Guaranteed Lifetime Withdrawal Benefit (GLWB) is often one of the strongest tools available to solve this problem.
- Generate lifetime income
- Protect their principal from stock market losses.
- Maintain control of their assets.
- Leave a death benefit to beneficiaries.
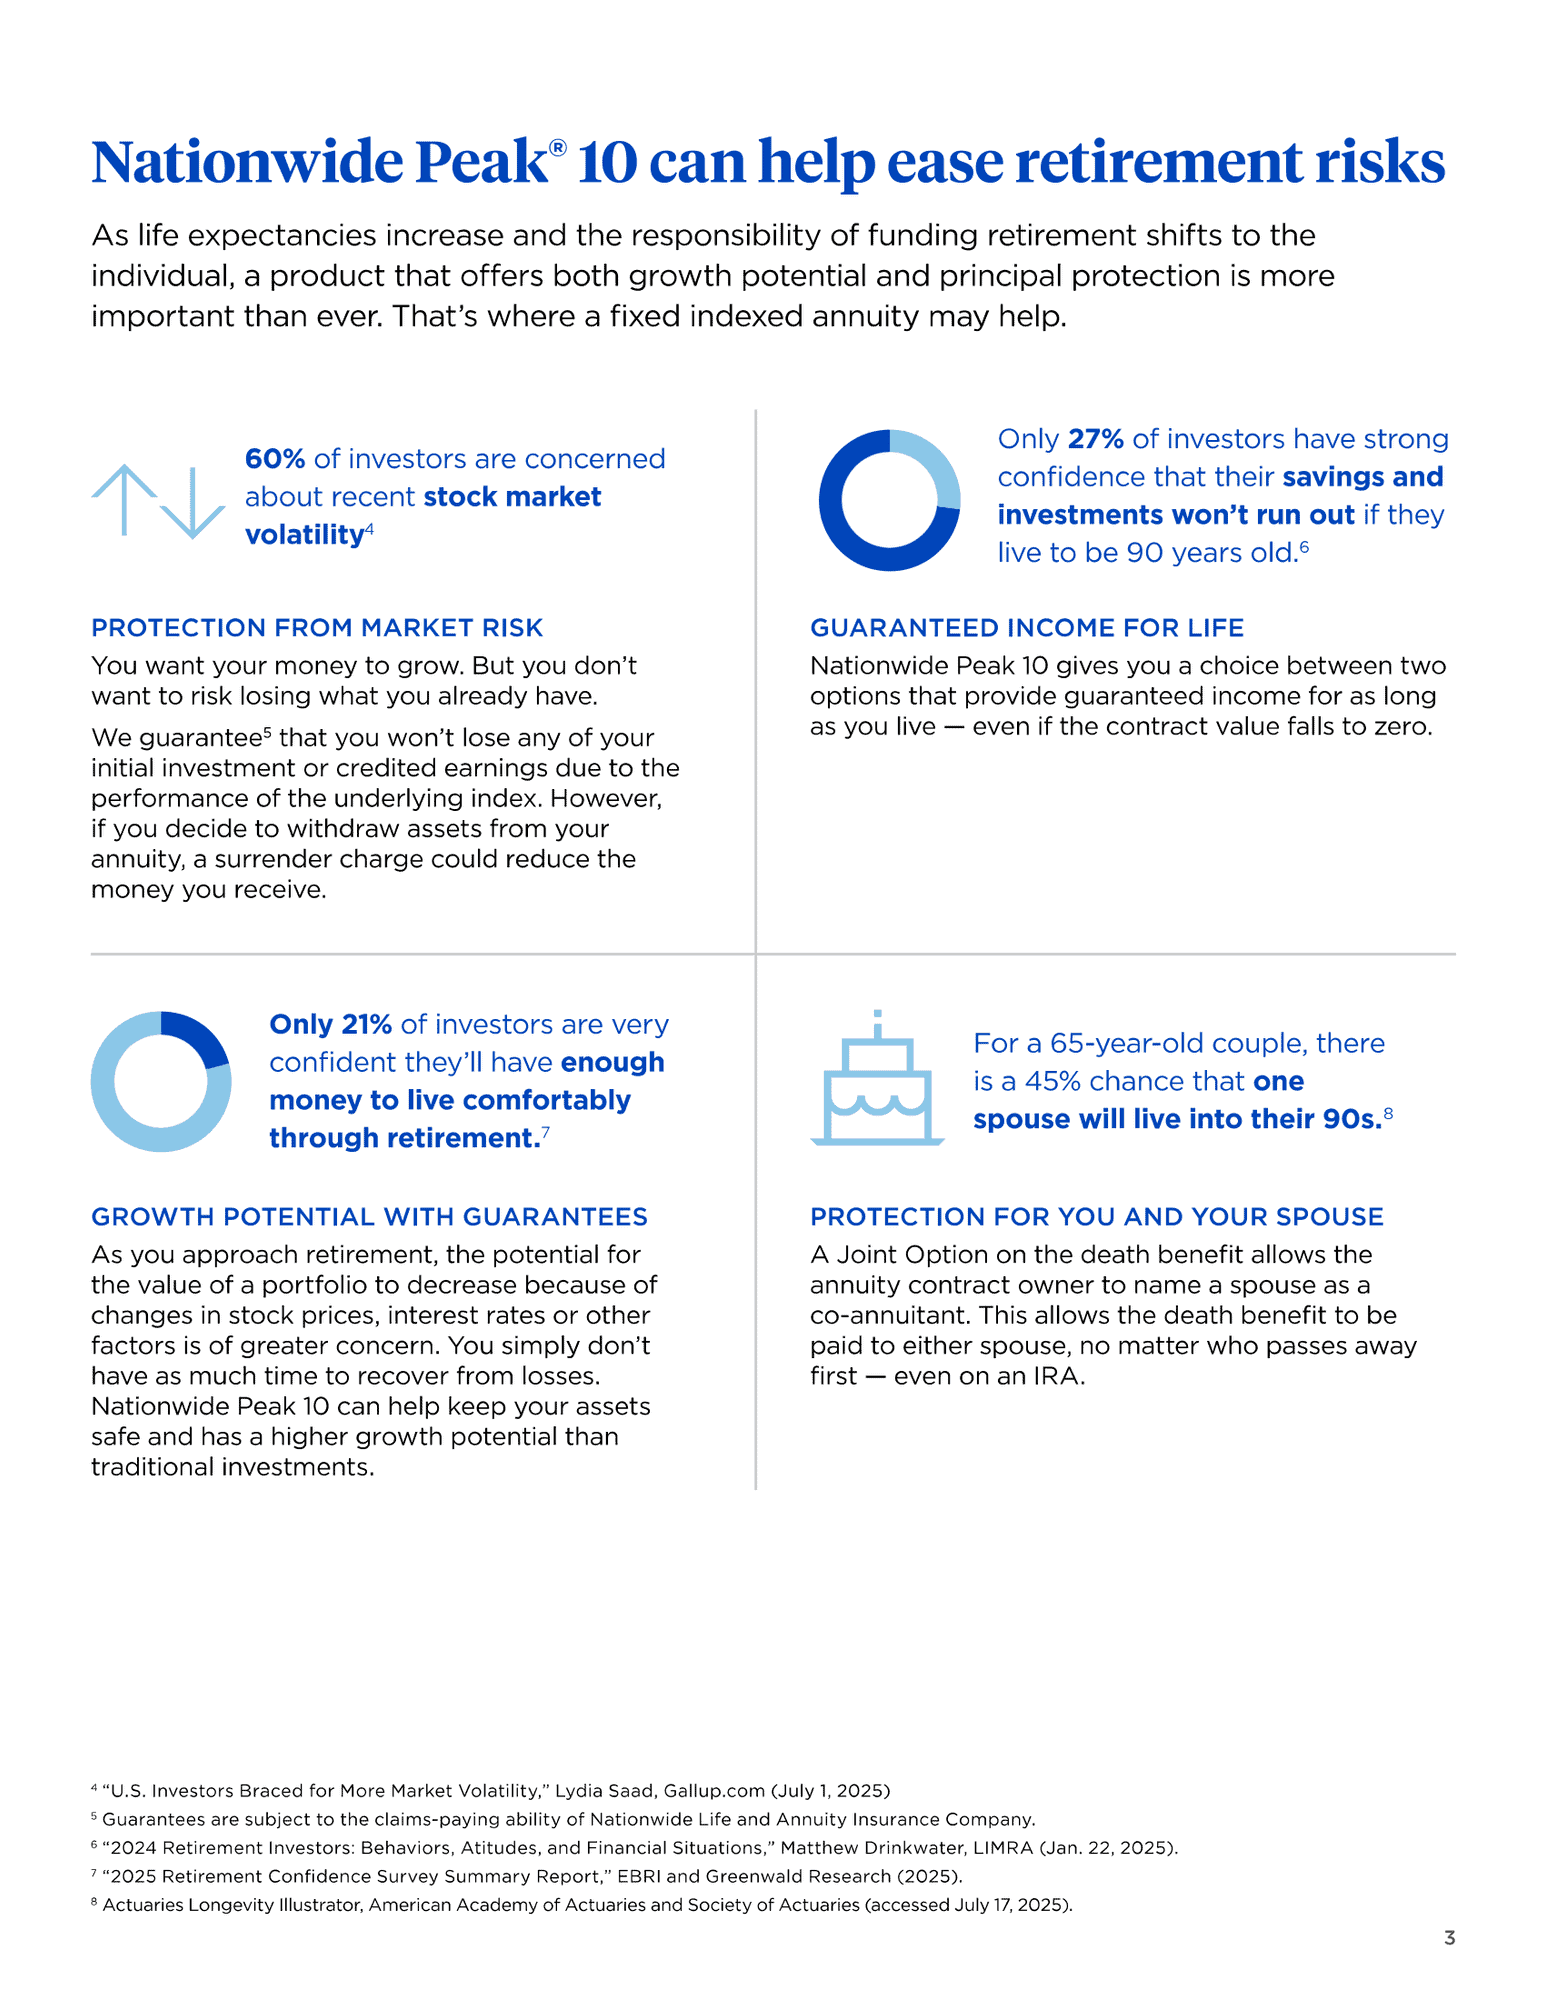
Two standout options for this strategy include the Nationwide Peak 10 Annuity for lifetime income and the Oceanview CapLock Fixed Indexed Annuity for conservative growth.
The Best Annuity for Women Who Need Lifetime Income
Recommended option: Nationwide Peak annuity with a GLWB rider.
Women must prepare for retirement income that may last 25–35 years or more. A GLWB annuity solves longevity risk by providing income that continues for life, even if the account balance reaches zero.
How GLWB Lifetime Income Works
A GLWB creates a separate income value used to calculate retirement payments.
Once withdrawals begin:
- Payments continue for life
- The retiree keeps control of the annuity.
- Any remaining balance can pass to beneficiaries.
GLWBs typically pay higher income amounts than traditional joint-and-survivor annuity payouts, while still preserving flexibility and a potential death benefit.
Pros
- Lifetime income protection against longevity risk
- Control over retirement assets
- Potential death benefit for heirs
- Principal protection from market losses
Cons
- Rider costs may apply.
- Income values differ from actual account values.
- Early withdrawals may trigger surrender charges.
Who Needs It
- Women planning for long retirement horizons
- Retirees seeking guaranteed income stability
- Individuals are worried about outliving their savings.
Who Does Not Need It
- Investors focused purely on aggressive stock market growth.
- Individuals who do not require a guaranteed income
The Best Annuity for Women Seeking Safe Retirement Growth
Recommended option: Oceanview CapLock Fixed Indexed Annuity.
Some women want to grow their retirement savings safely before activating lifetime income.
Fixed Indexed Annuities Provide:
- Principal protection from market downturns
- Tax-deferred growth
- Index-linked interest potential with the S&P 500, Nasdaq-100, and Russell 2000
- Cap rates can be locked in for the entirety of the contract
Unlike direct stock investments, these contracts never lose value due to market declines, which can help protect retirement savings during volatile markets.
Pros
- Market loss protection
- Tax-deferred accumulation
- Flexible income options later
Cons
- Growth is capped compared to direct equity investing.
- Early withdrawals can trigger surrender penalties.
Who Needs It
- Women approaching retirement who want safer accumulation
- Investors transitioning from market risk to stability.
Who Does Not Need It
- Individuals who are comfortable with full stock market volatility

The Three GLWB Income Payout Options Women Should Understand
GLWB annuities offer multiple income structures designed for different retirement goals.
Level Lifetime Income
This payout provides a fixed payment amount for life.
Benefits:
- Highest initial income
- Predictable cash flow
Drawback:
- Payments do not increase over time, which may reduce purchasing power due to inflation.
Increasing Lifetime Income
An increasing payout option increases the withdrawal percentage at later ages.
Benefits:
- Higher payments later in retirement
- Useful for long life expectancy
- Helps combat inflation
Drawback:
- Early payments may be smaller.
Because women statistically live longer, increasing or advanced GLWB structures are often worth considering.
Joint Lifetime Income for Married Women
Many women retire with a spouse or partner and need income protection for both individuals.
GLWB annuities often allow joint lifetime income, meaning payments continue as long as either spouse is alive.
Advantages of joint income:
- Protects surviving spouses
- Provides predictable retirement income
However, joint payouts are usually lower than single-life payouts because the insurance company expects to pay income for a longer period.
Using Life Insurance to Protect Children
Many women want to ensure their children receive financial support after their death.
One Strategy is Pairing Annuity Income with Life Insurance
This approach works well because:
- Annuity income supports retirement spending
- Life insurance creates a tax-free inheritance.
Even inexpensive term life policies can generate large death benefits for children.
Our term life solutions can extend up to 40 years, which can provide long-term protection for families.
Enhanced Death Benefits as an Alternative to Life Insurance
Some annuities offer enhanced death benefit riders.
These riders may increase the payout to beneficiaries based on:
- Account value growth
- Roll-up credits
- Bonus structures
Enhanced death benefits can act as a life insurance alternative, especially for individuals who cannot qualify for traditional coverage due to health concerns.
However, life insurance still generally provides larger death benefits for the premium paid.
The Best Annuity Strategy for Single Women
Single women often face the highest longevity risk because there is no second household income to rely on during retirement.
Without a spouse’s pension or Social Security survivor benefit, retirement income must be built from personal savings.
For this reason, many single women focus on creating a guaranteed lifetime income that cannot run out.
A Fixed Indexed Annuity with a Guaranteed Lifetime Withdrawal Benefit (GLWB) is often the most effective solution.
Why This Strategy Works
A GLWB allows single retirees to withdraw income for life while still maintaining ownership of the annuity contract.
Even if the account balance is depleted due to withdrawals, the insurance company continues making payments.
This structure is especially valuable for women because they are statistically more likely to live into their late 80s and 90s.
Pros
- Lifetime income protection against longevity risk
- Principal protection from market losses
- Access to remaining funds if needed
- Lump sum death benefit for heirs if money remains
Cons
- Income riders add costs to the annuity.
- Surrender charges apply during early contract years.
Who Needs It
- Single women planning retirement alone
- Widows without pension survivor income
- Retirees seeking a stable lifetime income
Who Does Not Need It
- Investors are comfortable managing market volatility independently.
- Individuals who prefer stock-based retirement withdrawals
The Best Annuity Strategy for Divorced or Widowed Women
Divorce and widowhood often create major retirement income gaps.
When a spouse passes away or a marriage ends, household income may drop significantly while living expenses remain largely unchanged.
This makes income stability a top priority.
One of the most effective strategies is converting retirement savings into lifetime income using a fixed indexed annuity with a GLWB.
This approach creates a pension-style income stream without giving up ownership of the assets.
Why This Matters for Widows
Many widows experience income reductions because:
- One Social Security benefit disappears
- Pension survivor benefits may be smaller than expected.
- Investment portfolios may decline during market downturns.
A GLWB annuity helps stabilize income regardless of market conditions.
Pros
- Lifetime income stability
- Principal protection from market losses
- Potential inheritance for children
Cons
- Income amounts depend on age and product structure.
- Some riders include annual fees.
Who Needs It
- Recently widowed retirees
- Divorced women rebuilding retirement income
- Individuals transitioning from dual-income households to single-income retirement.
Who Does Not Need It
- Retirees with large pension income already covering expenses.
The Best Annuity Strategy for Women Leaving an Inheritance
Many women want to ensure their children receive financial support after their death.
Two Strategies Can Accomplish This
Purchasing life insurance alongside an annuity allows retirees to spend retirement income while preserving an inheritance.
Life insurance provides a tax-free death benefit, which is often much larger than the premium paid.
This strategy works especially well when inexpensive term life coverage is available.
Enhanced Annuity Death Benefits
Some annuities offer enhanced death benefit riders that increase the amount passed to beneficiaries.
These riders may credit bonuses or guaranteed growth rates to the death benefit value.
While these riders can help create inheritance protection, traditional life insurance usually produces larger payouts for the same cost.
Other Insurance Women Should Consider
Long-Term Care Insurance
Women are significantly more likely to require long-term care services.
Long-term care insurance protects retirement assets from nursing home and assisted living costs.
Standalone LTC policies are usually more effective than annuity riders that simply return your own money.
Medigap Coverage
Medicare does not cover many out-of-pocket healthcare expenses.
A Medigap insurance policy can help cover deductibles and co-pays during retirement.
Disability Insurance
Women who are still working should consider disability insurance to protect their income before retirement.
Why Comparing Annuities Matters
Two annuities with the same premium can produce very different income payments.
Important factors that influence payouts include:
- Age at retirement
- Income rider structure
- Index strategies
- Insurance company pricing
Comparing multiple contracts helps ensure retirees receive the highest possible lifetime income at the lowest cost.
Bottom Line
Women face a unique retirement challenge because they typically live longer than men, which increases the risk of outliving their savings.
A fixed indexed annuity with a GLWB can help solve this problem by providing:
- Lifetime income protection
- Principal protection from market losses
- Control over retirement assets
- Potential death benefits for beneficiaries
For longevity income planning, the Nationwide Peak annuity is one of the strongest options available. For conservative growth before income begins, the Oceanview CapLock FIA provides strong principal protection with index-linked growth potential.
Contact The Annuity Expert to compare the best annuities for women and receive free quotes for lifetime income strategies designed to protect your retirement and your family.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
Why do women need different retirement planning strategies?
Women statistically live longer than men, which means their retirement savings must last longer. This increases the risk of running out of money, making lifetime income strategies like GLWB annuities especially valuable.
What is the best annuity for women seeking lifetime income?
Fixed indexed annuities with GLWB riders are often the best option because they provide principal protection and lifetime income while maintaining asset control.
Can women leave money to their children with an annuity?
Yes. If funds remain in the annuity at death, the remaining balance typically passes to beneficiaries as a lump sum death benefit.
Should women use life insurance along with annuities?
We would pair them when you need both retirement income and a specific inheritance or financial cushion for family. Use the annuity for the paycheck and life insurance for the death benefit. If existing assets already cover those family needs, extra life insurance may not earn its premium.