

Benefits of Starting an Annuity at 55
Scenario
Entering your mid-50s often signals a shift towards serious retirement planning. Annuities can play a crucial role in this phase, providing a stable and reliable income stream. Here’s why getting an annuity at age 55 is beneficial:
- Enhanced Retirement Security: Annuities provide guaranteed income, ensuring you won’t outlive your savings. This financial security can be a cornerstone of your retirement plan.
- Tax Advantages: The tax-deferred growth of annuities means you won’t pay taxes on your earnings until you withdraw them, allowing your investment to grow more efficiently.
- Investment Diversity: By incorporating annuities into your portfolio, you diversify your investments, balancing risk and ensuring a steady income.
Types of Annuities to Consider
Choosing the right annuity depends on your financial goals and risk tolerance. Here are the main types of annuities available:
- Fixed Annuities: These offer a guaranteed interest rate, making them ideal for those seeking stability and predictability.
- Variable Annuities: These depend on the performance of underlying investments. They offer the potential for higher returns, suitable for those willing to accept more risk.
- Indexed Annuities: These are linked to a market index. They offer a middle ground, providing some growth potential with protection against market downturns.
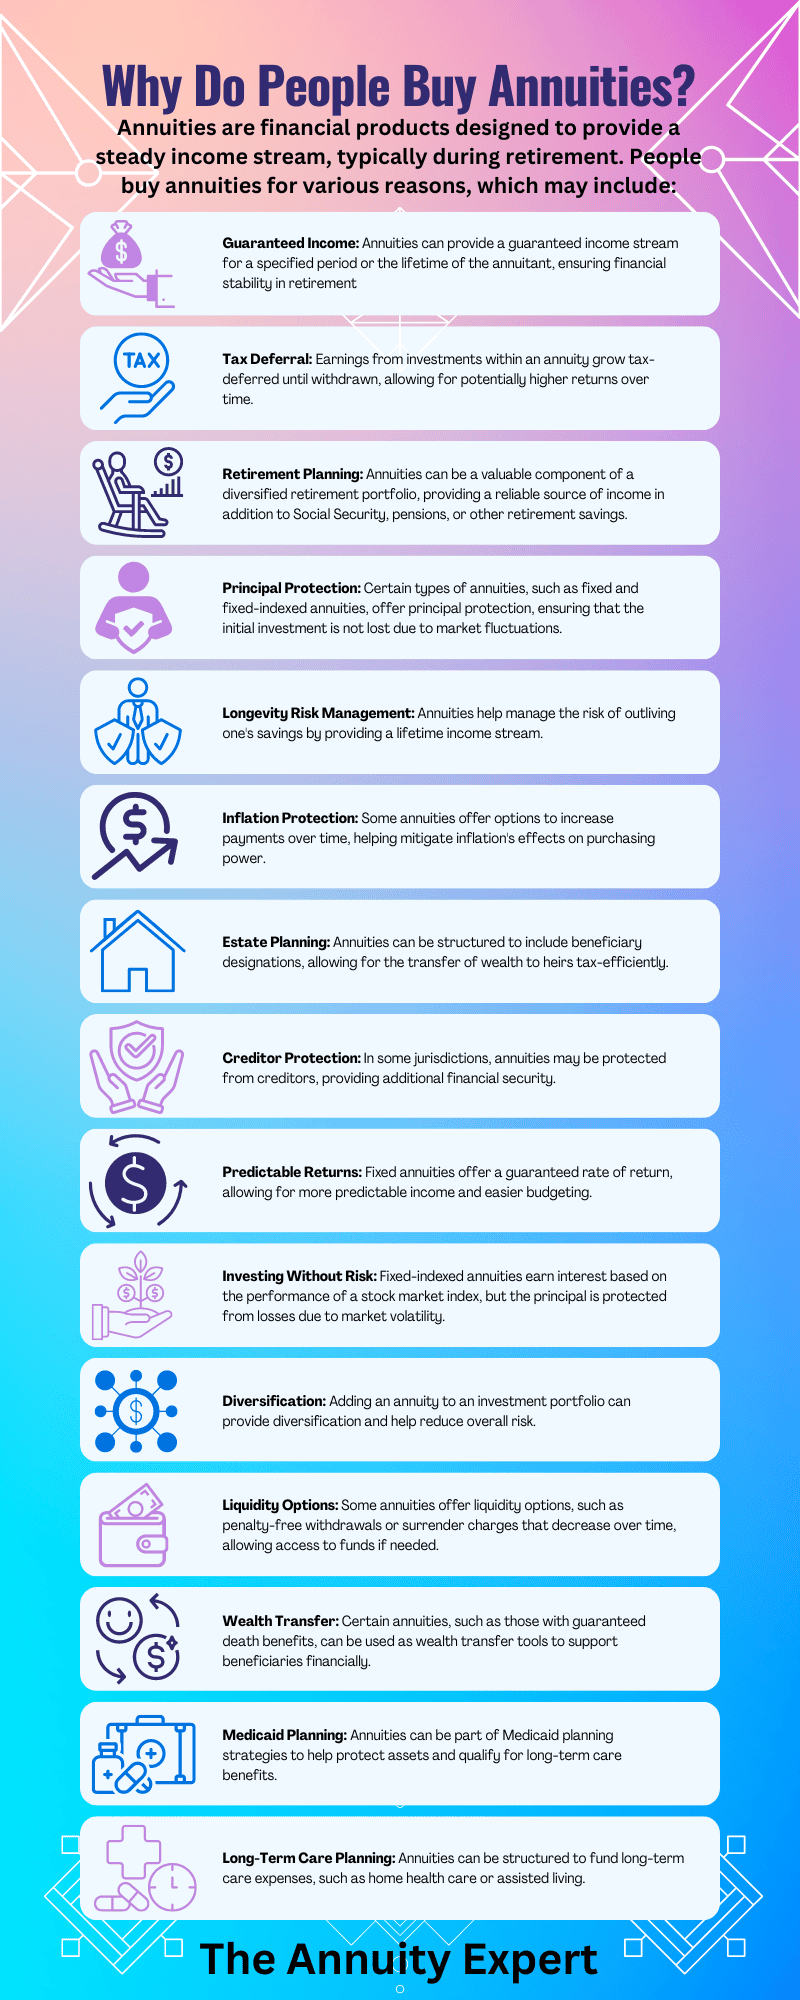
5 Reasons Getting an Annuity at Age 55 Is a Smart Move
1. Guaranteed Income for Life with a GLWB Rider
Key Stat: Payouts often start at 5% to 8% annually for life starting at age 60+
✔ A Guaranteed Lifetime Withdrawal Benefit (GLWB) rider grows your income base while deferring withdrawals
✔ The key to getting the highest GLWB income is the time between the purchase date and the income start date
✔ The longer you wait to take income, the higher your lifetime payout will be
✔ Pays more than the 4% withdrawal rule and never runs out
✘ Income is capped after withdrawals start (no market upside)
✘ Annual rider fees of 0.75% to 1.5%
Who Needs It: Pre-retirees who want a hands-off lifetime income stream that’s guaranteed
Who Doesn’t: DIY investors comfortable managing their own withdrawals and market risk
Also Consider: Fixed index annuities with GLWB riders to capture index gains before income begins
2. Lock in Higher Future Income by Buying Early
Key Stat: Deferring just 5 years can boost payouts by 25% or more
✔ Riders often credit 5% to 10% growth annually during deferral
✔ Buying at 55 locks in a longer growth window before income begins
✔ Helps bridge the gap to Social Security or pension income
✘ Funds are committed until income starts
✘ Less effective if you need cash access or pass away early
Who Needs It: Those with income needs starting in 5 to 10 years
Who Doesn’t: Retirees already needing income or who prefer liquid assets
Helpful Add-on: Use a MYGA (multi-year guaranteed annuity) for a safe yield while delaying income
3. Inflation Protection Through Income Growth Riders
Key Stat: Some income riders grow payouts 3% to 5% annually
✔ Optional GLWB riders adjust income upward based on index growth
✔ Protects long-term buying power
✔ Works automatically—no rebalancing or guesswork
✘ Riders with inflation protection cost more
✘ Income may not match real inflation rates during high-cost years
Who Needs It: Risk-averse individuals concerned about inflation’s long-term impact
Who Doesn’t: Those with low expected expenses or fixed pensions already indexed
4. Reduce Retirement Risk Before It’s Too Late
Key Stat: A 20% market loss before retirement can slash income for life
✔ Fixed and fixed index annuities offer downside protection
✔ Removes market timing and sequence-of-return risk
✔ Keeps your retirement income plan stable
✘ Limited gains in bull markets
✘ Typically requires a 5–10 year commitment
Who Needs It: Anyone approaching retirement with investments tied to the market
Who Doesn’t: Younger workers or those with time to recover from losses
5. Fill the Retirement Income Gap Early
Key Stat: Social Security replaces only about 40% of pre-retirement income
✔ Immediate annuities (SPIAs) can pay income now if you retire before full retirement age
✔ Guaranteed, consistent monthly income
✔ Complements Social Security and other income sources
✘ Once annuitized, you lose control of the lump sum
✘ No access to the original principal
Who Needs It: Early retirees needing immediate income with no market risk
Who Doesn’t: Those delaying retirement or requiring asset flexibility
Final Thoughts
The longer you wait to draw income from your annuity, the higher your guaranteed lifetime payout. Buying at 55 gives your income base more time to grow, locking in stronger financial security.
Contact The Annuity Expert’s financial advisors and insurance agents for free quotes and comparisons to find the best annuity with lifetime income benefits.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.