

What It Really Means for Your Lifestyle, Social Security, and Retirement Income
Retirement isn’t just about how much you have—it’s about how you manage it. A $300,000 nest egg can be enough for some retirees, but whether it lasts depends on your expenses, income sources, and withdrawal strategy.
How Long $300,000 Can Last
How long will $300,000 last depends on your withdrawal method.
- 4% Rule: Withdrawing 4% annually means $12,000 per year, not counting Social Security. This may last 25–30 years if invested conservatively.
- With Social Security: Adding the average $1,900/month benefit (~$22,800/year), a retiree could have ~$35,000 annually. Couples may receive closer to $45,000–$55,000.
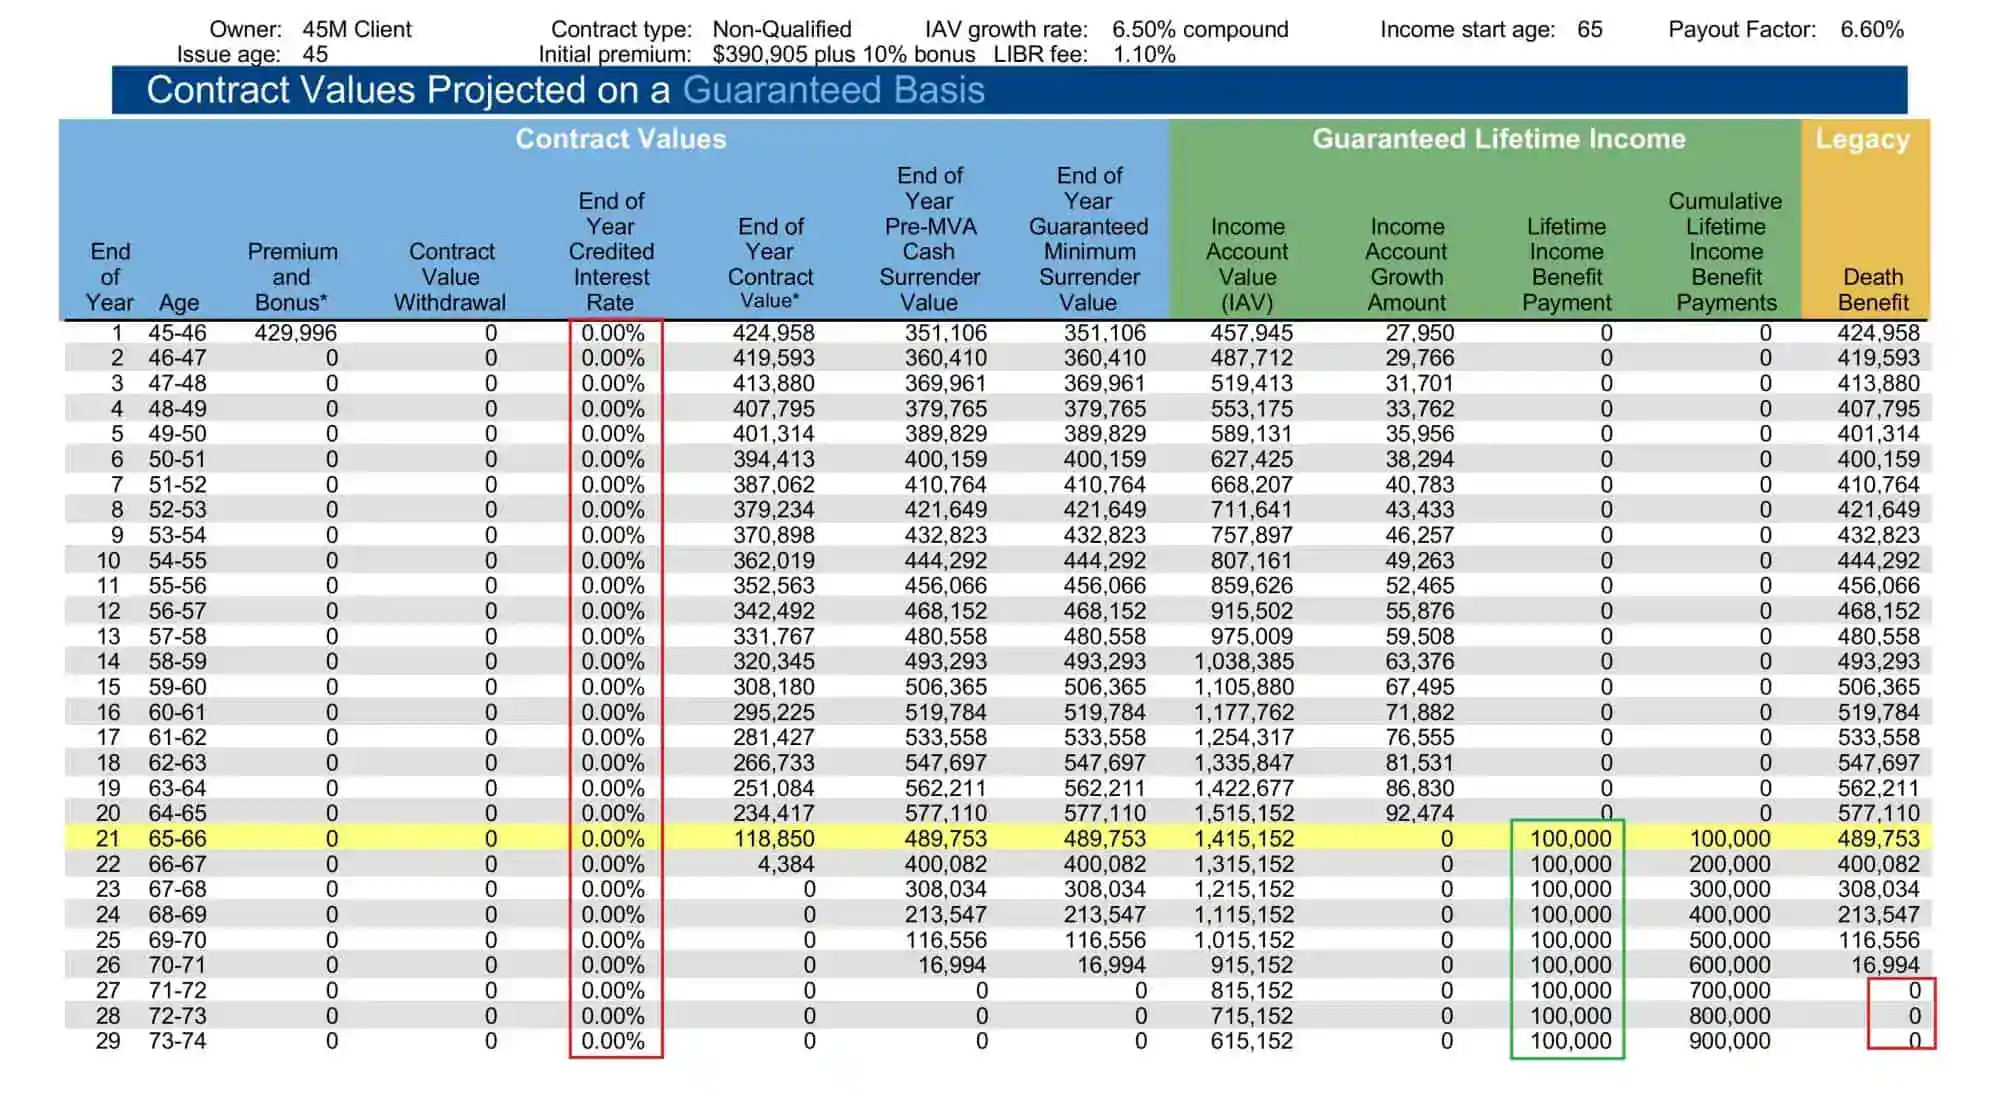
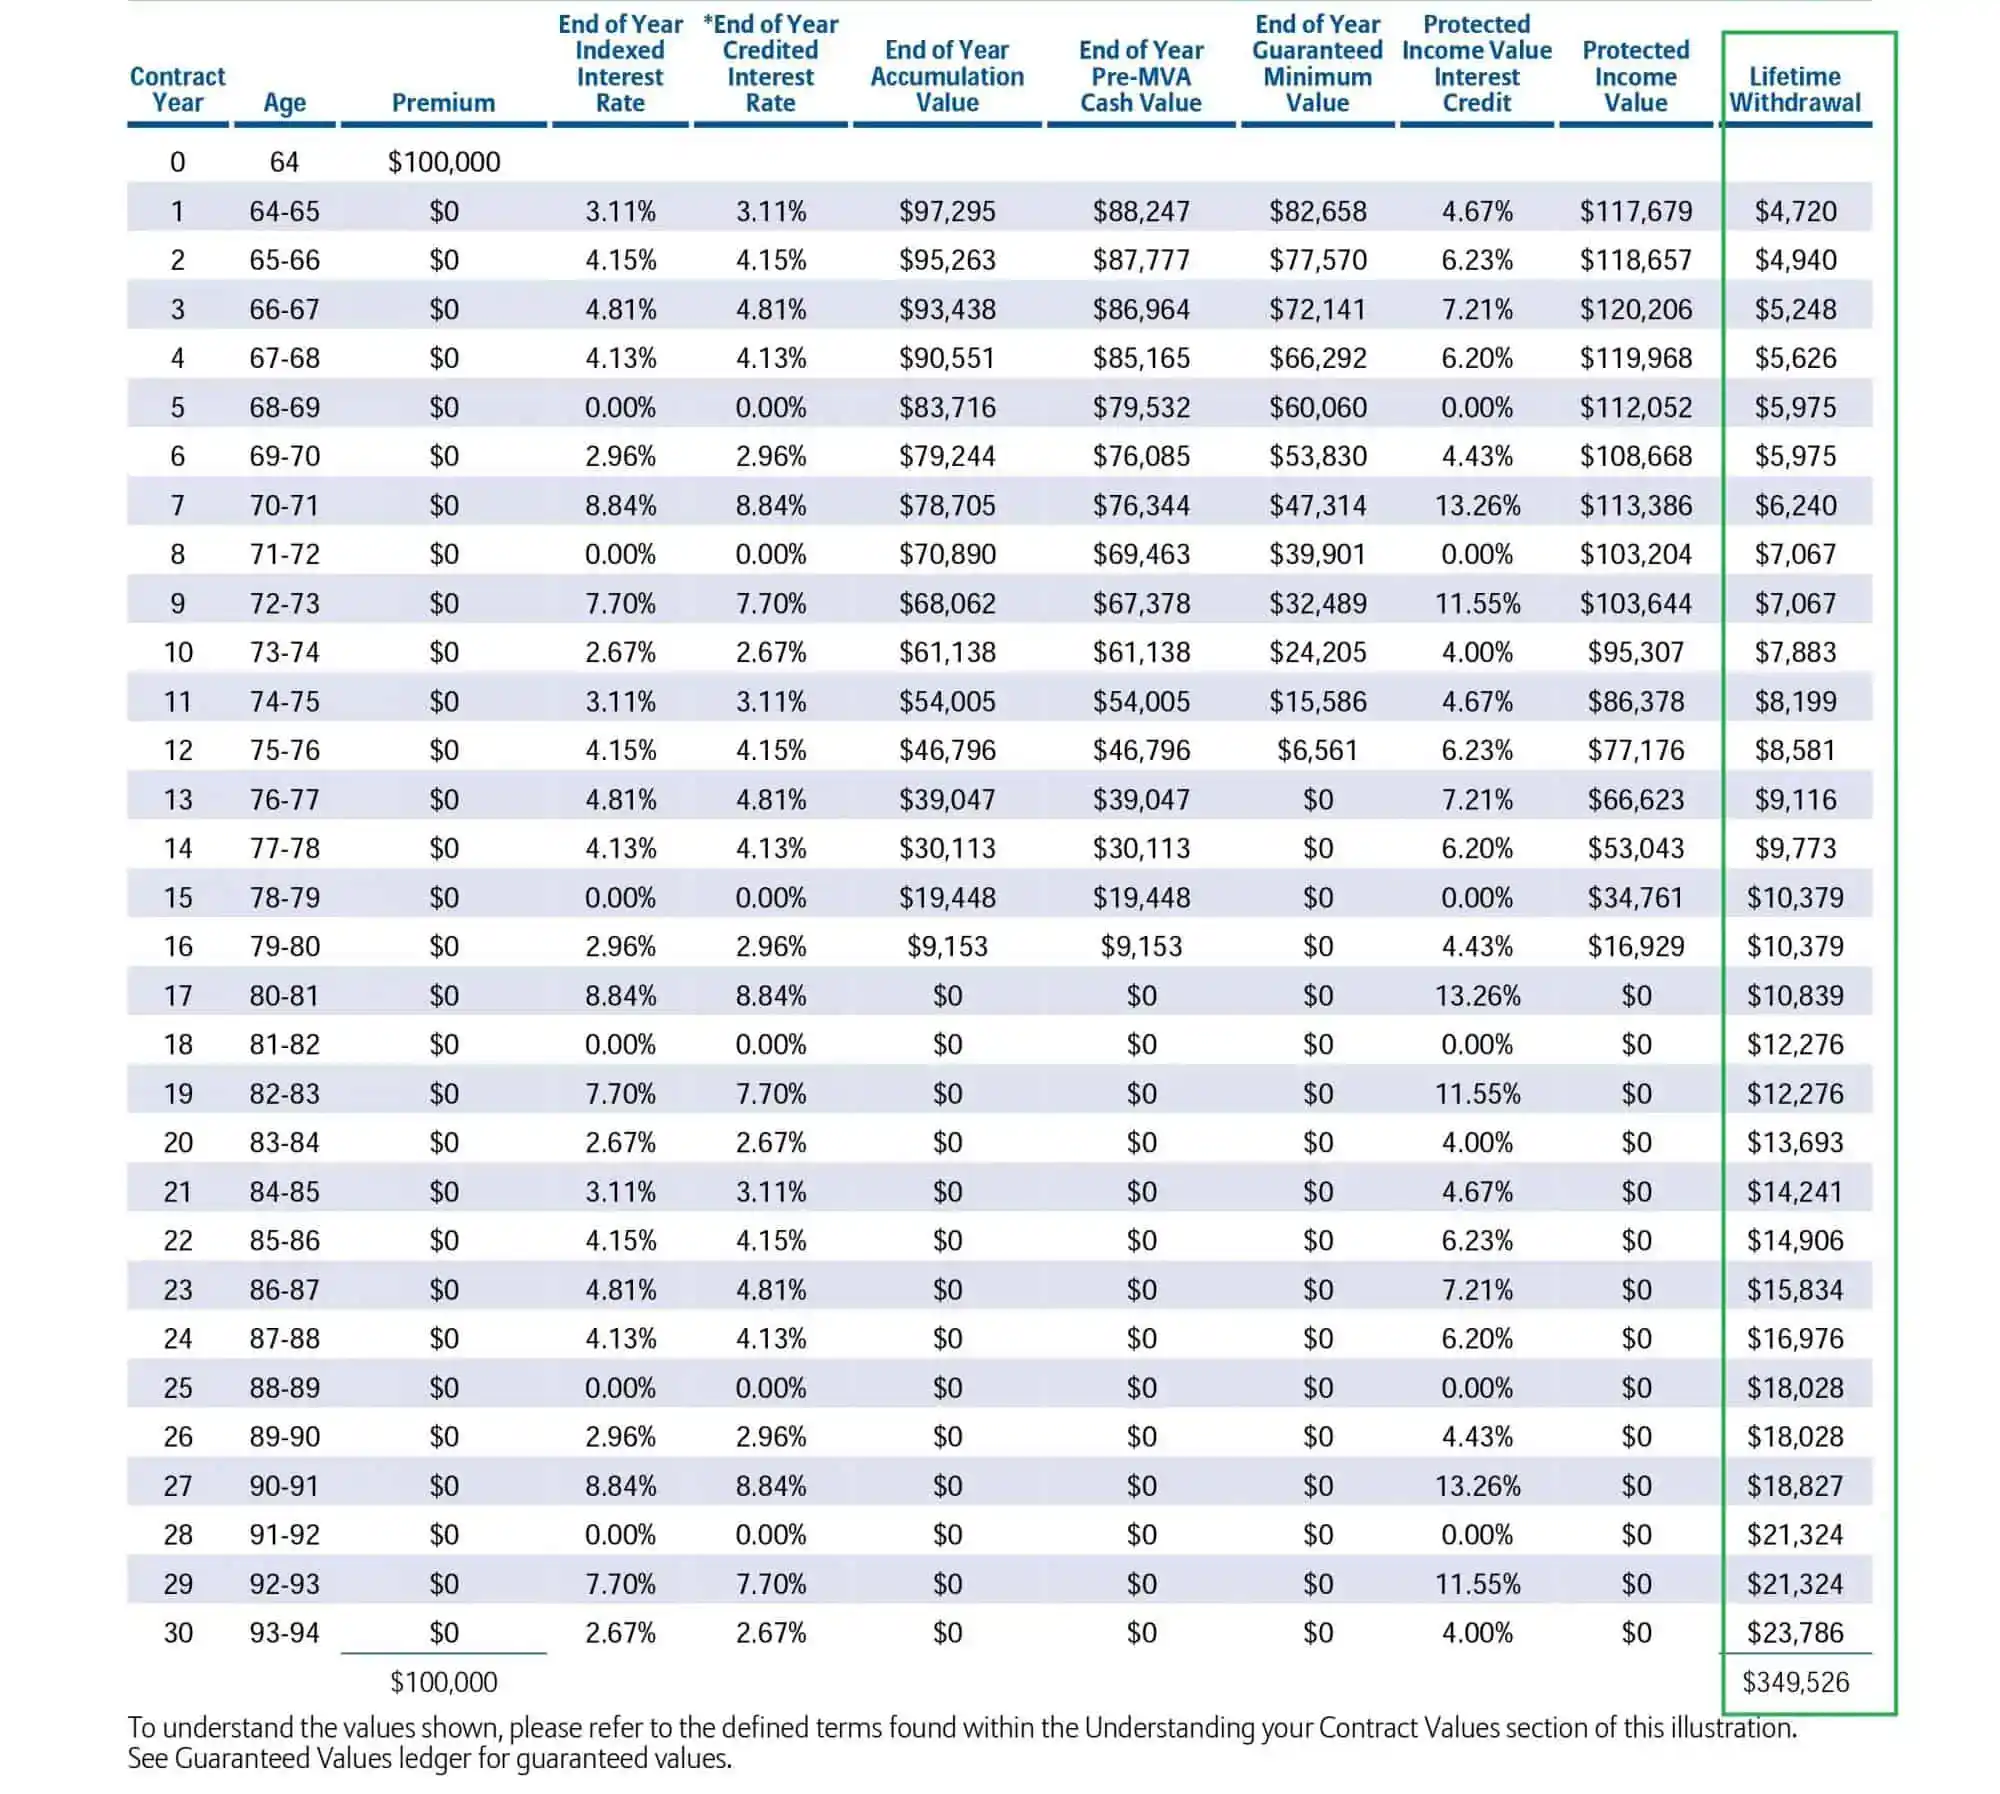
- With Annuities (GLWB): A Guaranteed Lifetime Withdrawal Benefit can turn $300k into lifelong income, with payouts increasing if you wait to start withdrawals.
Comparing Annuity Options
- Single Premium Immediate Annuity (SPIA): Provides higher immediate income but no flexibility.
- Fixed Indexed Annuity (FIA) with GLWB: Provides income for life, market-linked growth, and legacy protection.
- Multi-Year Guaranteed Annuity (MYGA): Good for tax-deferred growth if you’re not ready to start income yet.
Annuity Calculator
Our annuity calculator helps you find the best annuity rates for retirement. It provides personalized quotes from top-rated insurance companies and compares rates to give you accurate annuity payouts. This tool estimates guaranteed lifetime annuity payments, either immediately or deferred.
Note: With a Guaranteed Lifetime Withdrawal Benefit (GLWB), you maintain control of your money, earn interest to grow your savings, and stay protected from stock market downturns. Plus, any unused balance will pass directly to your beneficiaries in a lump sum.
Comparing the 4% Rule vs. Annuities With GLWB
Both the 4% Rule and a GLWB annuity can turn your $300,000 into retirement income, but they approach the problem differently. Seeing them side by side makes it easier to decide which one — or what combination — fits your goals best.
| Factor | 4% Rule | Annuity With GLWB |
|---|---|---|
| Income Security | No guarantees. Savings may run out if markets underperform. | Guaranteed lifetime income, even if your account balance goes to zero. |
| Ownership of Savings | You keep full control of all assets. | You keep ownership and access to your balance — unlike annuitization, you don’t give up control. |
| Inflation Protection | Withdrawals can be increased each year for inflation. | Payments are typically flat unless you add an inflation rider. |
| Market Exposure | Full exposure to growth and downturns. | Income is guaranteed regardless of markets; some growth potential depending on contract type. |
| Flexibility | High — spend more or less as you wish. | Moderate — you can access funds, but exceeding the rider’s withdrawal amount can reduce or void the guarantee. |
| Legacy for Heirs | Remaining assets go to beneficiaries. | Any unused balance passes directly to heirs in a lump sum. |
| Ease of Use | Requires ongoing management and discipline. | Hands-off: insurer guarantees your income stream. |
Bottom Line
- The 4% Rule works best if you want maximum flexibility, growth potential, and don’t mind managing risk yourself.
- An annuity with a GLWB rider works best if you want guaranteed income, protection from market downturns, and peace of mind that you won’t outlive your savings.
- For many retirees, the most practical approach is a hybrid: use an annuity for a baseline paycheck you can’t outlive, and keep the rest invested for growth and inflation protection.

Retirement Scenarios With GLWB + Social Security
Individuals
| Age | GLWB Annual Income | Monthly GLWB | Avg. Social Security | Total Annual Income | Total Monthly Income |
|---|---|---|---|---|---|
| 62 | $21,600 | $1,800 | $22,800 | $44,400 | ~$3,700 |
| 67 | $23,580 | $1,965 | $30,000 | $53,580 | ~$4,465 |
| 70 | $24,870 | $2,072 | $36,000 | $60,870 | ~$5,073 |
Couples
(One $300k annuity + double Social Security)
| Age | GLWB Annual Income | Combined Social Security | Total Annual Income | Total Monthly Income |
|---|---|---|---|---|
| 62 | $21,600 | $45,600 | $67,200 | ~$5,600 |
| 67 | $23,580 | $60,000 | $83,580 | ~$6,965 |
| 70 | $24,870 | $72,000 | $96,870 | ~$8,073 |
Note: Social Security payouts are just estimates. The actual Social Security amount depends on lifetime earnings and claiming strategy.
Alternatives to Annuities
Not everyone wants an annuity. Alternatives include:
- Bond Ladders: Provide a predictable cash flow by staggering bond maturities, but no lifetime guarantee.
- TIPS (Treasury Inflation-Protected Securities): Protect against inflation by adjusting principal with CPI, but also lack a lifetime guarantee.
- Dividend stocks: Growth potential, but income isn’t guaranteed.
- CDs: Safe but limited growth.
Important: These don’t protect against outliving savings like annuities do.
The Impact of Inflation
Let’s look at a couple retiring at 67 with $83,580 of combined annual income (from one annuity + Social Security).
| Year | Nominal Income | Equivalent Buying Power (3% Inflation) |
|---|---|---|
| Today | $83,580 | $83,580 |
| 10 Years | $83,580 | ~$61,900 |
| 20 Years | $83,580 | ~$45,800 |
| 30 Years | $83,580 | ~$33,800 |
Takeaway: At a steady 3% inflation, today’s $83,580 will feel like only ~$33,800 in 30 years. Fixed incomes lose buying power over time. This is why some retirees choose annuities with increasing payout riders or blend guaranteed income with growth-oriented investments like fixed indexed annuities.
Insurance That Protects a $300k Nest Egg
- Long-Term Care Insurance: Shields your savings from being wiped out by nursing home or assisted living costs, which can drain $300k in just a few years.
- Bridge Health Insurance (if under 65): Covers healthcare costs if you retire before Medicare eligibility, preventing high out-of-pocket medical expenses during the “bridge years.”
- Medicare + Supplements (if 65 or older): Reduces surprise medical bills by filling in the gaps Medicare doesn’t cover, ensuring predictable healthcare costs in retirement.
- Disability Insurance (for early retirees): Provides income protection before Social Security eligibility if you leave work due to health issues.
- Life Insurance: Provides financial protection for surviving spouses and helps create a legacy for your family.
Best Life Insurance Options for Retirement:
✅ Term Life Insurance – Covers temporary needs but expires.
✅ Guaranteed Universal Life (GUL) – Permanent coverage with lower premiums.
✅ Whole Life Insurance – Builds cash value and provides lifelong protection.
✅ Survivorship Life Insurance – Covers both spouses and pays out after both pass.
Making $300,000 Last Longer
- Delay Social Security until 67–70.
- Use annuities for guaranteed lifetime income.
- Downsize housing or relocate to a lower-cost state.
- Supplement with part-time income.
- Balance annuity guarantees with growth assets to hedge inflation.
Final Thoughts
If you rely on the 4% rule, $300,000 may last 25–30 years—but that’s not a guarantee. A fixed index annuity with a GLWB gives you 5–8% annual income for life, beating the 4% rule and removing market risk. Adding long-term care protection ensures medical bills won’t wipe out your money. Pairing that with life insurance helps protect your spouse and leave a legacy for your loved ones.
👉 Contact The Annuity Expert today to compare annuity rates, life insurance quotes, and long-term care options — and build a plan that turns your $300,000 into income you can count on for life.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.