

Atlantic Coast Life Accumulation Protector Plus Annuity Review
The Atlantic Coast Life Accumulation Protector Plus is a fixed indexed annuity designed for protected accumulation. The contract combines principal protection, a first-year premium bonus, fixed and indexed crediting strategies, a 10-year surrender period, and an optional Rate Enhancement Rider.
On product features alone, there are parts of the Accumulation Protector Plus that could look attractive. However, we do not recommend purchasing this annuity or any other Atlantic Coast Life product at this time. The current financial-strength and regulatory concerns involving the insurance company outweigh every bonus, crediting strategy, rate guarantee, and liquidity feature in the contract.
Our Professional Opinion on the Atlantic Coast Life Accumulation Protector Plus Annuity
We do not recommend the Atlantic Coast Life Accumulation Protector Plus annuity, and we do not recommend placing new money into any Atlantic Coast Life product at this time.
This is no longer a normal annuity comparison where an attractive bonus, guaranteed participation rate, return-of-premium feature, or higher illustrated yield could make the product worth considering. Atlantic Coast Life currently falls far below our A- minimum financial-strength standard, and regulators in multiple states have taken or announced actions affecting the company’s ability to accept new business.
Atlantic Coast Life’s AM Best Financial Strength Rating was downgraded into the marginal category and remains under review with negative implications. South Carolina’s insurance regulator has filed a petition seeking to place Atlantic Coast Life and its affiliated reinsurer into rehabilitation. Virginia has suspended Atlantic Coast Life’s authority to solicit or accept new and renewal business while requiring the company to continue servicing policies already in force.
That is enough for us to remove the company from consideration for every new annuity purchase.
We would not make an exception because the premium is below a state’s guaranty-association limit. A state guaranty association is a backstop used after an insurer fails. It is not a reason to knowingly select a financially troubled insurance company when stronger alternatives are available.
Even when some or all of a contract ultimately falls within applicable guaranty-association limits, an insurer failure or regulatory takeover can create delays, uncertainty, restricted transactions, and years of administrative complications. The purpose of purchasing a fixed indexed annuity is safety. Taking avoidable carrier risk defeats that purpose.
The Accumulation Protector Plus does contain features that would be worth analyzing if the contract were issued by a financially stronger insurer. The product offers a premium bonus, principal protection from negative index performance, multiple crediting periods, select participation-rate guarantees, an optional rate-enhancement feature, and additional liquidity for qualifying health events.
None of those features change our recommendation because every contractual guarantee is ultimately backed by Atlantic Coast Life’s financial strength and claims-paying ability.
We also would not purchase this annuity for guaranteed lifetime income. It does not include a flexible guaranteed lifetime withdrawal benefit. The available lifetime-payment choices require traditional annuitization, which is generally irreversible and gives up control of the lump sum in exchange for the payment stream.
The contract’s 10-year participation-rate guarantees apply only to select engineered indexes. They do not lock the traditional S&P 500 cap or participation rate for the entire surrender period, and the fixed-account rate is declared one year at a time.
In other words, the product does not provide the type of transparent traditional-index cap lock we generally prefer for safe accumulation. The locked rates are connected to proprietary indexes whose future performance depends on their methodology, volatility controls, internal construction, and continued index availability.
The optional Rate Enhancement Rider is another feature we would approach carefully even if the insurer were financially stronger. The rider charges an annual fee to improve fixed, cap, and participation rates and to increase the free-withdrawal allowance. The fee can reduce the contract value, and the enhanced S&P 500 and fixed-account terms are not guaranteed for the full surrender period.
We do like that the rider can add a return-of-premium guarantee after the required holding period, adjusted for withdrawals. However, a return-of-premium provision is still only as dependable as the company backing it.
Our bottom line: Do not purchase the Atlantic Coast Life Accumulation Protector Plus annuity. Choose an A- or better-rated insurance company instead, even if Atlantic Coast Life advertises a larger bonus, a higher rate, or a more attractive illustration.
Compare Accumulation Protector Plus With Today’s Best Fixed Indexed Annuities
The strongest accumulation annuity changes as insurance companies adjust crediting terms, bonuses, liquidity, surrender periods, and product features. Carrier financial strength should be the first filter, not an afterthought.
What We Like
- Nothing Outweighs the Current Carrier Risk: The contract has several features that look good on paper, but none of them is enough for us to recommend placing new money with Atlantic Coast Life.
- Principal Protection From Index Losses: Negative index performance does not directly reduce the account value, although rider fees, withdrawals, surrender charges, and an MVA can reduce the amount received.
- Select 10-Year Participation-Rate Guarantees: Certain one- and two-year strategies tied to the Momentum Index and Diversified Macro 5 Index lock the participation rate for the initial surrender period, subject to continued index availability.
- Traditional S&P 500 Choices: The contract includes S&P 500 cap and participation-rate strategies for buyers who do not want to rely entirely on proprietary indexes.
- Multiple Crediting Periods: One-, two-, and three-year strategies provide several ways to structure the interest-crediting period.
- Optional Return of Premium: The Rate Enhancement Rider can add a contractual return-of-premium feature after the required holding period, adjusted for withdrawals.
- Health-Related Access: Qualifying terminal illness or nursing-home confinement can provide access without the normal surrender charge, MVA, or loss of applicable unvested bonus value.
- Existing Policies Continue to Be Serviced: Current owners should review their contracts carefully rather than panic-surrendering and creating avoidable charges, taxes, or benefit losses.
What We Don’t Like
- Marginal AM Best Rating: Atlantic Coast Life falls far below our A- minimum financial-strength standard.
- Negative Rating Review: The company’s rating remains under review with negative implications.
- Regulatory Restrictions: State regulators have suspended or are stopping new business in certain jurisdictions.
- Pending Rehabilitation Petition: South Carolina’s insurance regulator has asked a court to place Atlantic Coast Life and its affiliated reinsurer into rehabilitation.
- Weak Balance-Sheet Assessment: AM Best has cited weak capital, deteriorating regulatory-capital ratios, illiquid assets, affiliated investments, concentrated reinsurance leverage, and marginal operating performance.
- Product Guarantees Do Not Fix Company Risk: Every bonus, rate lock, and return-of-premium promise is backed by Atlantic Coast Life.
- Guaranteed Rates Are Concentrated in Engineered Indexes: The full-term participation-rate guarantees do not apply to the true S&P 500 strategies.
- S&P 500 Rates Can Change: The cap and participation rate on the traditional S&P 500 strategies can be reset after the applicable crediting period.
- Fixed Rate Can Change Annually: The fixed account does not provide the multi-year certainty of a MYGA.
- Rider Fee: The Rate Enhancement Rider charges an annual fee against the applicable crediting-account values.
- Bonus Vesting: The premium bonus vests gradually over the surrender period and can be forfeited after an early surrender or excess withdrawal.
- Limited Standard Liquidity: Standard penalty-free access is relatively low unless the owner pays for the Rate Enhancement Rider.
- No Flexible Lifetime-Income Rider: Lifetime payments require annuitization rather than a modern GLWB.
- Long Surrender Period: The contract requires a 10-year commitment and includes a Market Value Adjustment.
- Guaranty-Association Coverage Is Not a Reason to Buy: It should be treated as a last-resort safety net, not a substitute for selecting a financially strong insurer.
Accumulation Protector Plus Product Details
| Product Type | Single Premium Fixed Indexed Annuity |
| Primary Purpose | Protected Long-Term Accumulation |
| Surrender Period | 10 Years |
| Issue Ages | Generally ages 0 through 85, subject to state and funding rules |
| Minimum Premium | $5,000 |
| Maximum Premium | $1,000,000 without prior company approval |
| Premium Bonus | One-time first-year bonus subject to a 10-year vesting schedule |
| Standard Free Withdrawal | Beginning in year two, the greater of 5% of account value or the applicable RMD, subject to contract rules |
| Rate Enhancement Rider | Optional annual-fee rider that improves selected crediting terms, increases the free-withdrawal allowance, and adds a return-of-premium feature |
| Index Choices | Momentum Index, Diversified Macro 5 Index, and S&P 500 |
| Crediting Periods | One, two, or three years depending on the selected strategy |
| Fixed Account | One-year declared interest rate |
| Market Value Adjustment | Yes |
| Return of Premium | Available only through the Rate Enhancement Rider and subject to the contract requirements |
| Guaranteed Lifetime Withdrawal Benefit | Not Available |
| Death Benefit | Generally the greater of vested value or minimum guaranteed surrender value before annuity payments begin |
| Current Company Rating | AM Best C+ (Marginal), under review with negative implications as of September 2026 |
| New-Sale Availability | Changing by state; new business has been suspended or restricted in certain jurisdictions |
Atlantic Coast Life is not an annuity company we recommend at this time. The insurer currently falls far below our A- minimum, its AM Best rating is in the marginal category and under review with negative implications, a rehabilitation petition is pending in South Carolina, and state regulators have restricted new business in certain jurisdictions. Our non-recommendation applies to the company as a whole—not merely to the Accumulation Protector Plus product.
Product availability and contract provisions vary by state and issue date. The product brochure used for this review was prepared before the most recent regulatory actions. New-sale availability should be confirmed before relying on any product material.
In the News: Atlantic Coast Life Rating and Regulatory Developments
Atlantic Coast Life’s financial and regulatory position changed materially during 2026.
- AM Best Downgrade: Atlantic Coast Life was downgraded to C+ (Marginal) and remains under review with negative implications.
- Weak Balance Sheet: AM Best cited deteriorating capital levels and regulatory-capital ratios, illiquid assets, affiliated investments, concentrated securities, reinsurance leverage, and marginal operating performance.
- South Carolina Rehabilitation Petition: The South Carolina Department of Insurance filed a petition asking a court to place Atlantic Coast Life and Southern Atlantic Re into rehabilitation. A petition is not the same as a final rehabilitation order, but it is a serious regulatory development.
- Virginia Suspension: Virginia suspended Atlantic Coast Life’s certificate of authority and ordered the company to stop soliciting or accepting new and renewal business while continuing to service existing policies.
- Changing State Availability: Other states have announced or implemented restrictions on new Atlantic Coast Life business.
We will not recommend an Atlantic Coast Life product unless the company’s financial strength and regulatory position improve materially.
How the Accumulation Protector Plus Annuity Works
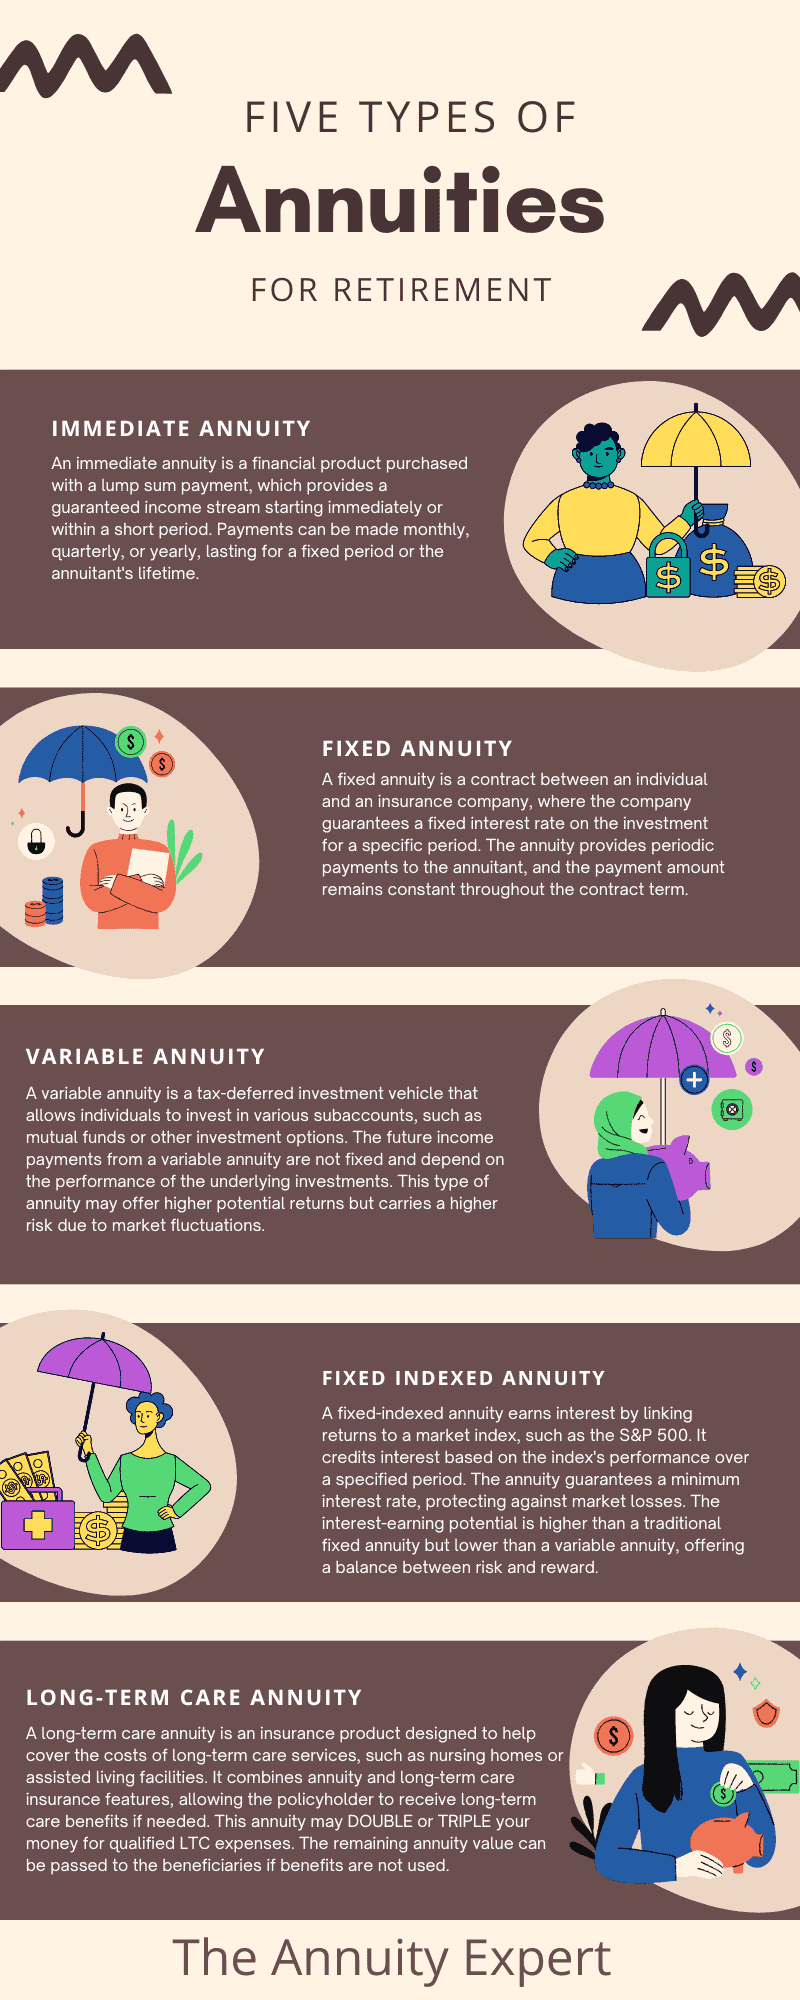
The Accumulation Protector Plus is designed to protect the account from direct losses caused by negative index performance while allowing interest to be credited through fixed and index-linked strategies.
The contract does not invest directly in the S&P 500, Momentum Index, Diversified Macro 5 Index, or any underlying securities. The indexes are used only to calculate interest under the contract formula.
If the selected index strategy produces a negative result, the indexed credit is generally zero rather than negative. Previously credited interest is not lost because the index declines. However, withdrawals, rider fees, surrender charges, and an MVA can reduce the amount available from the contract.
Because the product is a single-premium annuity, the buyer generally funds it with one lump sum. The premium can then be divided among the available fixed and indexed strategies.
Premium Bonus and Vesting
The product credits a one-time premium bonus when the annuity is purchased. The bonus is added to the account value, but it vests gradually over the 10-year surrender period.
The bonus is not unrestricted cash. If the contract is surrendered early or the owner takes a withdrawal above the penalty-free amount, some or all of the unvested bonus can be forfeited.
The death benefit is also based on the vested value rather than automatically including all unvested bonus value. Buyers should not assume the entire bonus is immediately available to them or their beneficiaries.
A bonus can help offset an existing surrender charge or increase the starting contract value, but it should never be the primary reason to accept a financially weaker insurance company.
Ten-Year Participation-Rate Guarantees
The most interesting accumulation feature is the guarantee on select participation rates tied to the Momentum Index and Diversified Macro 5 Index.
The one- and two-year participation rates for those qualifying strategies are designed to remain in place during the initial surrender period, provided Atlantic Coast Life continues to have access to the applicable index.
Those guarantees do not apply to the traditional S&P 500 strategies. The S&P 500 cap and participation rate can change after the applicable crediting period.
We generally like annuities that reduce renewal-rate risk. However, locking a participation rate on an engineered index is not the same thing as locking a competitive cap on the true S&P 500, Nasdaq-100, or Russell 2000.
A guaranteed participation rate does not guarantee that the underlying engineered index will perform well. The buyer is exchanging some renewal-rate uncertainty for index-design and index-performance uncertainty.
Buyers seeking transparent multi-year guarantees should compare annuities designed to reduce future renewal-rate drops from A- or better-rated insurance companies.
Crediting Strategies
The Accumulation Protector Plus includes a fixed account and several indexed strategies with one-, two-, or three-year crediting periods.
Momentum Index Strategies
The Momentum Index options include participation-rate strategies and a trigger-rate strategy. A trigger strategy credits the declared amount when the index meets the contract’s required result, subject to the strategy rules.
The qualifying one- and two-year participation-rate strategies receive the longer guarantee described above. The three-year strategy and trigger rate do not receive the same stated full-term guarantee.
Diversified Macro 5 Index Strategies
The Diversified Macro 5 options use participation-rate crediting over one-, two-, or three-year terms. The qualifying one- and two-year strategies receive the longer participation-rate guarantee, subject to continued access to the index.
This is a proprietary index rather than a traditional broad-market benchmark. Before selecting it, review its launch date, live performance, methodology, volatility controls, internal index deductions, and the amount of historical performance that is hypothetical or backtested.
S&P 500 Strategies
The product includes one- and two-year S&P 500 choices using caps and participation rates.
We prefer transparent traditional indexes when the economics are competitive. However, the S&P 500 crediting terms can be changed after the applicable strategy period, so they do not provide the same renewal-rate certainty as the qualifying engineered-index strategies.
Fixed Account
The fixed account credits a declared rate for one contract year. The rate can change at the next contract anniversary.
If the plan is to keep most of the money in the fixed account, a MYGA may provide stronger contractual certainty because the rate is guaranteed for the selected multi-year term.
Rate Enhancement Rider
The optional Rate Enhancement Rider charges an annual fee based on the value in the applicable crediting accounts.
The rider is designed to:
- Increase selected fixed, cap, and participation rates
- Increase the annual penalty-free withdrawal allowance
- Add a return-of-premium guarantee after the required holding period, adjusted for withdrawals
The rider fee can reduce the account value even though negative index performance itself does not.
We also would not assume that every enhanced rate is locked for 10 years. The rider improves the current crediting terms, but the traditional S&P 500 and fixed-account terms remain subject to renewal changes.
For a buyer who needs additional liquidity and values the return-of-premium provision, the rider may look useful on paper. That still does not justify purchasing the contract from Atlantic Coast Life under the company’s current financial and regulatory circumstances.
Liquidity, Surrender Charges, and MVA
The Accumulation Protector Plus has a 10-year surrender-charge period.
Beginning in the second contract year, the standard contract generally permits a penalty-free withdrawal equal to the greater of a portion of the account value or the applicable required minimum distribution.
The Rate Enhancement Rider increases the annual free-withdrawal allowance. Unused free withdrawals do not necessarily accumulate for future years.
Withdrawals above the penalty-free amount can be subject to:
- Surrender charges
- Loss of unvested bonus value
- A Market Value Adjustment
The MVA can increase or decrease the surrender value based on changes in interest rates and the contract formula.
Buyers who place a high priority on access should compare the best annuities for liquidity from financially stronger insurers.
Terminal Illness and Nursing Home Waivers
The contract can waive normal surrender restrictions for qualifying terminal illness or nursing-home confinement after the applicable waiting period.
The nursing-home benefit generally requires confinement for a minimum number of consecutive days. The terminal-illness benefit requires physician certification that the owner’s life expectancy meets the contract definition.
These penalty-free crisis waivers are useful liquidity features, but they are not comprehensive long-term care insurance.
Death Benefit
Before annuity payments begin, the death benefit is generally the greater of the vested value or the minimum guaranteed surrender value.
Because the death benefit uses the vested value, beneficiaries should not assume that all unvested premium-bonus value will be paid immediately after death.
This is a standard annuity death benefit rather than a dedicated enhanced legacy multiplier. Buyers whose primary objective is maximizing an inheritance should compare the best annuities for enhanced death benefits and traditional life insurance.
Settlement and Income Options
After the applicable contract period, the owner can elect traditional settlement options such as:
These options require annuitization. They are not the same as a GLWB that permits lifetime withdrawals while retaining an account value and death benefit as long as money remains.
If guaranteed retirement income is the goal, compare the amount available through the contract’s settlement option with current GLWB annuities from A- or better-rated insurers before making an irreversible decision.
Retirement Accounts Accepted
- Non-Qualified Funds
- Traditional IRA
- 401(k) Rollovers
- IRA Transfers and Rollovers
- SEP IRA
- Roth IRA
- TSP Rollovers
- 1035 Exchanges
- Inherited IRAs
- SIMPLE IRAs
Who Should Buy the Accumulation Protector Plus?
We do not believe anyone should place new money into the Accumulation Protector Plus while Atlantic Coast Life remains below our A- minimum and faces its current financial and regulatory issues.
On product features alone, the annuity was designed for someone who:
- Wants principal protection from negative index performance
- Can commit money for approximately 10 years
- Values a premium bonus and accepts its vesting schedule
- Is comfortable using proprietary index strategies
- Does not need a flexible guaranteed lifetime withdrawal benefit
Those buyers can accomplish the same general goals through A- or better-rated insurance companies without accepting the same carrier risk.
What Existing Atlantic Coast Life Owners Should Do
Existing owners should not automatically surrender an Atlantic Coast Life annuity. The correct decision for an existing owner is different from the decision to make a new purchase.
A rushed surrender could trigger surrender charges, a negative MVA, ordinary income taxes, loss of unvested bonus value, or the loss of a contractual benefit that cannot be restored.
Request the following information before making a decision:
- Current account value
- Current cash surrender value
- Remaining surrender charge
- Current Market Value Adjustment
- Vested and unvested bonus amounts
- Current renewal rates for every allocation
- Current death benefit
- Tax basis and taxable gain
- Any available settlement or annuitization quote
Then compare the amount that can actually be transferred with annuities from A- or better-rated insurers. A properly structured exchange may preserve tax deferral, but it should not be completed until the existing and replacement contracts have been compared side by side.
What We Recommend Instead
For safe accumulation, use an A- or better-rated insurance company.
Depending on the goal, compare:
- A fixed indexed annuity with competitive traditional-index crediting terms
- A cap-lock or participation-rate guarantee from a financially stronger carrier
- A MYGA when a fixed contractual return is the priority
- A GLWB annuity when guaranteed lifetime income is the primary goal
- An enhanced-death-benefit annuity or life insurance when legacy planning is the primary objective
Our broader best annuity comparison explains which structure fits different retirement goals.
What We Recommend
Do not purchase the Atlantic Coast Life Accumulation Protector Plus annuity under the company’s current financial and regulatory circumstances.
The product has several interesting accumulation features, but no bonus, rate guarantee, rider, or return-of-premium provision is worth accepting unnecessary carrier risk when stronger alternatives are available.
Existing owners should not panic. Review the surrender value, MVA, bonus vesting, tax basis, death benefit, and available replacement options before making a change.
Contact The Annuity Expert for free annuity quotes and a no-obligation comparison. We can review an existing Atlantic Coast Life contract or show new buyers alternatives from A- or better-rated insurance companies.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.