

Calculate Your Guaranteed Payouts and Compare Modern Income Alternatives
Popular two-tiered annuities included Allianz MasterDex Plus, PremierDex, and PowerDex Elite. These eventually evolved into the Endurance series. My career at Allianz started with most of these contracts leaving, and the GLWBs replacing the annuitization aspect.
Today’s retirees demand flexibility. Before you lock yourself into a restrictive two-tier contract, you need to look at modern alternatives like Fixed Index Annuities with Income Riders. By comparing quotes from top-rated carriers, you can buy an income strategy that guarantees a lifetime paycheck without forfeiting access to your principal in an emergency.
How Two-Tier Annuities Work
When shopping for retirement income, a Two-Tier Annuity can look incredibly tempting. Insurance companies often market these contracts with massive upfront premium bonuses and higher-than-average interest rates. But there is a massive catch: your money is divided into two different values. If you agree to turn the contract into a permanent, lifetime income stream (annuitize), you get the high value. But if you ever want to walk away with a lump sum of your own cash, you are penalized and forced to take a significantly lower value.
In the accumulation phase, your investment grows over time. This period can last several years, during which your funds benefit from interest rates typically higher than those offered by traditional savings accounts. Often, these annuities come with an initial bonus, boosting your investment from the start. This can be particularly attractive if you’re looking to maximize growth during the early years.
When you transition to the payout phase, the annuity converts into a steady stream of income. This phase is crucial for ensuring a reliable source of funds during retirement. You can choose to receive payments over a specified period or for the rest of your life, depending on the terms of your contract.
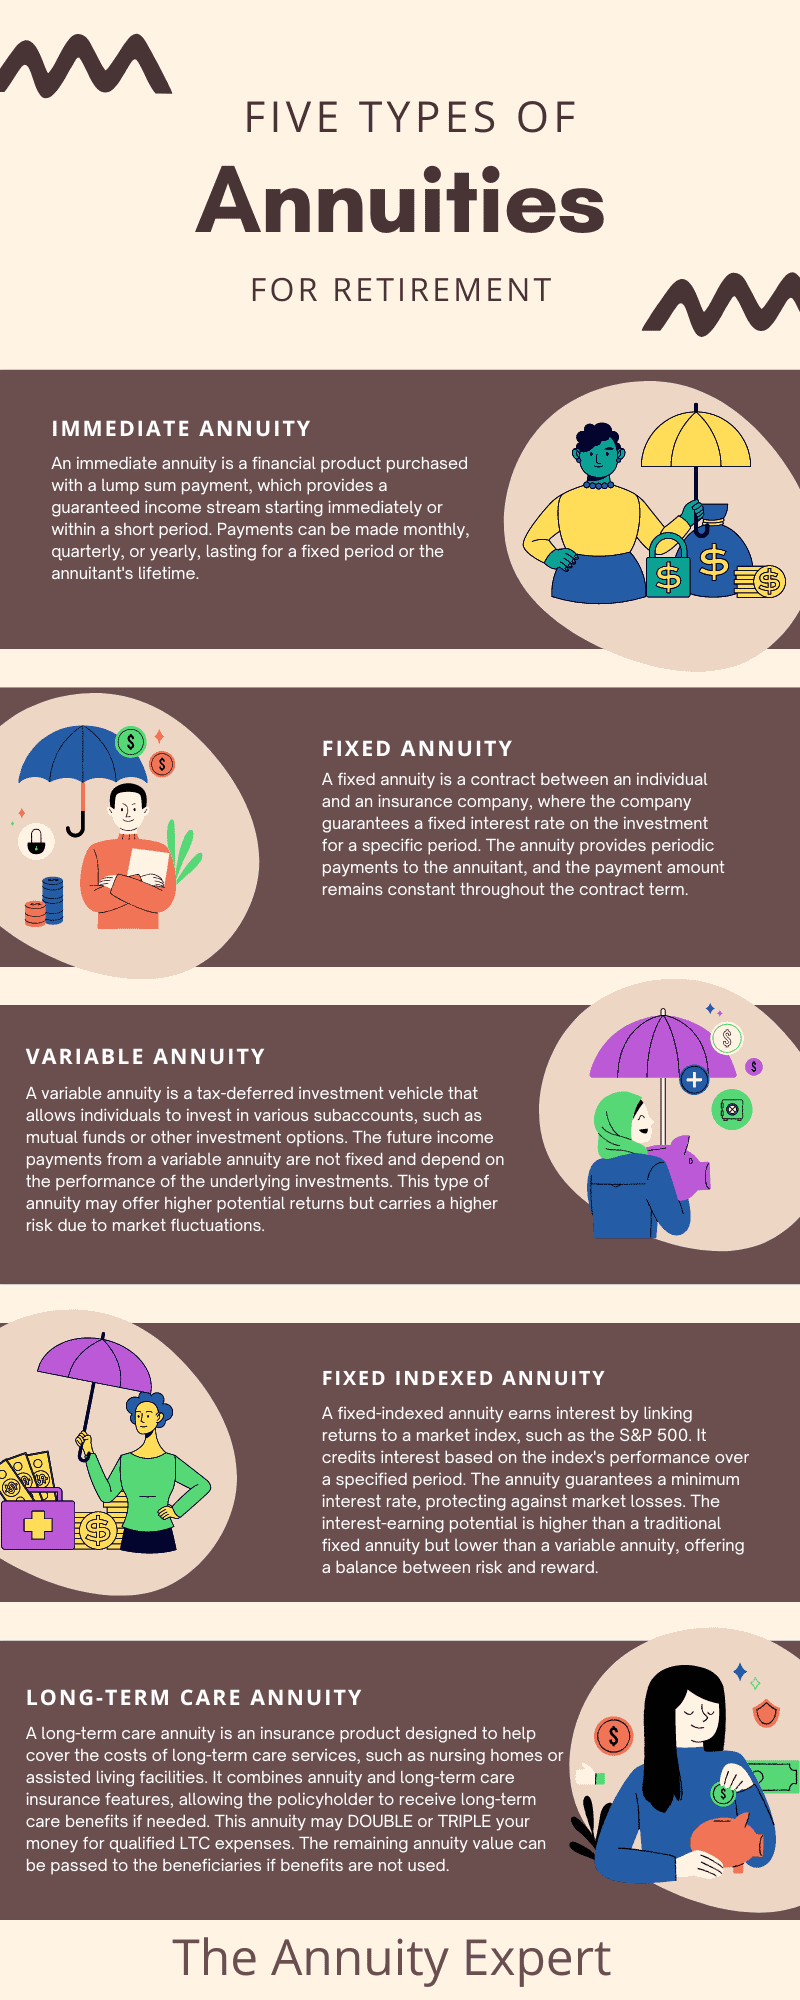
Types of Two-Tiered Annuities
Two-tiered annuities come in various forms, including fixed indexed annuities, variable annuities, and fixed annuities. Each type offers different benefits and is suited to different investment strategies:
Fixed Annuity: Offers a guaranteed interest rate, providing stability and predictable growth.
Fixed Indexed Annuity: Provides interest earnings linked to a stock market index, offering growth potential while protecting against market downturns.
Variable Annuity: Allows you to invest in multiple sub-accounts, similar to mutual funds, with the potential for higher returns but greater risk.

The “Two-Tier” Trap: How the Math Actually Works
A two-tier annuity creates two entirely separate ledgers for your money. You do not get to choose which one you want until the end of your contract term:
- Tier 1: The Annuitization Value (The High Number): This is the ledger that gets the big upfront bonus and the high interest rates. However, the only way to access this money is to “annuitize”—meaning you permanently surrender your lump sum to the insurance company in exchange for a fixed monthly check over a set period (e.g., 10 years or your lifetime).
- Tier 2: The Cash Surrender Value (The Low Number): If you decide you don’t want a monthly check and just want your lump sum back, the insurance company uses this second ledger. It strips away the bonuses, applies a much lower historical interest rate, and often hits you with surrender charges.
The Result: You are financially handcuffed. If you have a medical emergency and need $100,000 in cash, a two-tier annuity will brutally penalize you for taking it.
Two-Tier Annuity vs. Modern Fixed Index Annuity (FIA)
The wealth management industry has largely moved away from two-tier annuities because modern products do the exact same job much better. Here is how an older Two-Tier contract compares to a modern FIA with a Guaranteed Lifetime Withdrawal Benefit (GLWB) rider:
| Feature | Two-Tier Annuity | Modern FIA with Income Rider (GLWB) |
| Lifetime Income Guarantee | Yes (Must Annuitize) | Yes (Through a flexible rider) |
| Access to Lump Sum Cash | Heavily Penalized (Forced into Tier 2) | Full Access (You keep control of your account value) |
| Death Benefit for Heirs | Often lost if you die early in payout | Yes (Heirs get whatever cash value is left) |
| Upfront Bonuses | Very High (But highly restricted) | Moderate (But actual real money) |
Benefits of a Two-Tiered Annuity
The natural charm of a two-tiered annuity is in its practical design. Let’s get into it:
- Bonus Annuity Features: Often, a two-tiered annuity comes with an initial ‘bonus’ credited to your account, hence earning the name ‘bonus annuity.‘ This can be anywhere from 5-10% of your initial investment, immediately boosting your nest egg.
- Earnings Growth Potential: Another upside is the potential for growth in the accumulation phase. During this period, the money you invest earns interest, typically at a rate higher than what traditional savings accounts might offer.
- Guaranteed Income Stream: Once you reach the payout phase, you’ll receive a guaranteed income for a specified period or life, depending on the terms of your annuity contract.
- Higher Payouts: The two-tiered annuity contracts generally have higher annuity payout amounts for retirement income planning than an immediate or deferred annuity.
- Better Interest Rate: Typically, these retirement annuities offered better growth or a higher guaranteed interest rate simply because you would be stuck in the contract for a long time.
Disadvantages
The drawbacks of a two-tier annuity include the following:
- Loss of Liquidity: A reduction in liquidity compared to other deferred annuities. Contracts have limited liquidity (penalty-free withdrawals) during the accumulation phase if any at all. Therefore, there would be no liquidity in the income phase.
- Locked In: The contract owner is locked into a two-tier annuity, and they are only able to get out of it by taking a reduction in cash value or electing the annuity settlement option.
- Hard to Predict Income: You usually don’t know your retirement income payment amounts because these retirement annuities were mostly performance-based (indexed products) that earned gains versus the guaranteed income riders of modern annuities.
- Forced Annuitization: Annuity owners are forced to convert their accumulated value into periodic payments for a fixed period if they want to receive full access to all the benefits (including the bonus and the higher rate of return).
- High Surrender Charges: If you could surrender your contract, the surrender charges would be extremely high, and you’d lose a significant amount in your accumulation value.
- No Death Benefit: Finally, beneficiaries could have had zero death benefits if they chose a contingent life payout (single life or joint and survivor).
What if You Already Own a Two-Tier Annuity?
If you bought one of these contracts years ago, do not panic. You have options. If your surrender period has expired, you can use a 1035 Exchange to transfer your cash value tax-free into a modern, single-tier annuity. This allows you to reset your strategy, regain liquidity, and add a flexible income rider that doesn’t force you to forfeit your principal.

Who Should (and Shouldn’t) Buy a Two-Tier Annuity?
You should only consider this strategy if:
- You are 100% certain you will turn the contract into a lifetime income stream and will never need access to the lump sum.
- You are using it specifically to recreate a rigid, traditional pension.
You should avoid this strategy if:
- You want to leave a large cash inheritance to your children.
- You might need a large lump sum to pay for long-term care or nursing home expenses in the future.
- You value flexibility and control over your life savings.
Stop Guessing with Your Liquidity. Let Us Find a Better Contract.
Do not get blinded by a flashy 10% premium bonus if it means losing control of your retirement savings. The highest-paying annuity is only valuable if it actually fits your life.
As independent brokers, we expose the fine print. Let us help you compare quotes across 50+ A-rated carriers, avoid the two-tier liquidity trap, and buy a modern annuity that delivers high income and peace of mind.
Speak with The Annuity Expert or schedule a free consultation below.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Questions From Our Readers
What are the advantages of a two-tiered annuity?
A two-tier deferred annuity typically offers higher interest rates than other annuities with a similar structure, making it their main benefit.