

What Are Multi-Year Guaranteed Annuities (MYGAs)?
Multi-Year Guaranteed Annuities (MYGAs) are fixed annuities that offer a guaranteed interest rate for a specified number of years. These enhanced annuity rates provide a secure and predictable income stream, making them an excellent choice for retirement savings. MYGAs are designed to grow your retirement funds over time with the assurance of a fixed return.
How MYGAs Work
MYGAs work by locking in an interest rate for a set period, typically ranging from 3 to 10 years. During this time, your investment grows at the guaranteed rate, unaffected by market fluctuations. This stability makes MYGAs a low-risk option for conservative investors seeking reliable growth.
Comparing MYGAs To Savings Accounts
Purpose And Usage
- MYGAs: Specifically for retirement savings. They offer higher interest rates and tax-deferred growth, making them ideal for long-term financial planning. They are unsuitable for everyday spending and may incur penalties for early withdrawals if you are under 59 1/2.
- Savings Accounts: Used for short-term savings and daily expenses. They provide easy access to your money without withdrawal penalties but generally offer lower interest rates.
Interest Rates
- MYGAs: Offer higher, fixed interest rates, providing stable and predictable returns over the annuity term.
- Savings Accounts: Interest rates are lower and can fluctuate, offering less growth potential compared to MYGAs.
Tax Treatment
- MYGAs: Earnings grow tax-deferred until withdrawal, maximizing growth potential for retirement savings.
- Savings Accounts: Interest earned is taxable in the year it is received, reducing the net growth of your savings.
Accessibility
- MYGAs: Often have surrender charges for early withdrawals, especially if under age 59 1/2. Suitable for long-term savings and less for immediate access.
- Savings Accounts: Offer immediate access to funds without penalties, making them ideal for emergency funds and regular use.
Risk And Security
- MYGAs: Low-risk investments with guaranteed returns backed by the issuing insurance company and State Guaranty Association.
- Savings Accounts: Low-risk, FDIC-insured up to certain limits, providing high security for deposited funds.
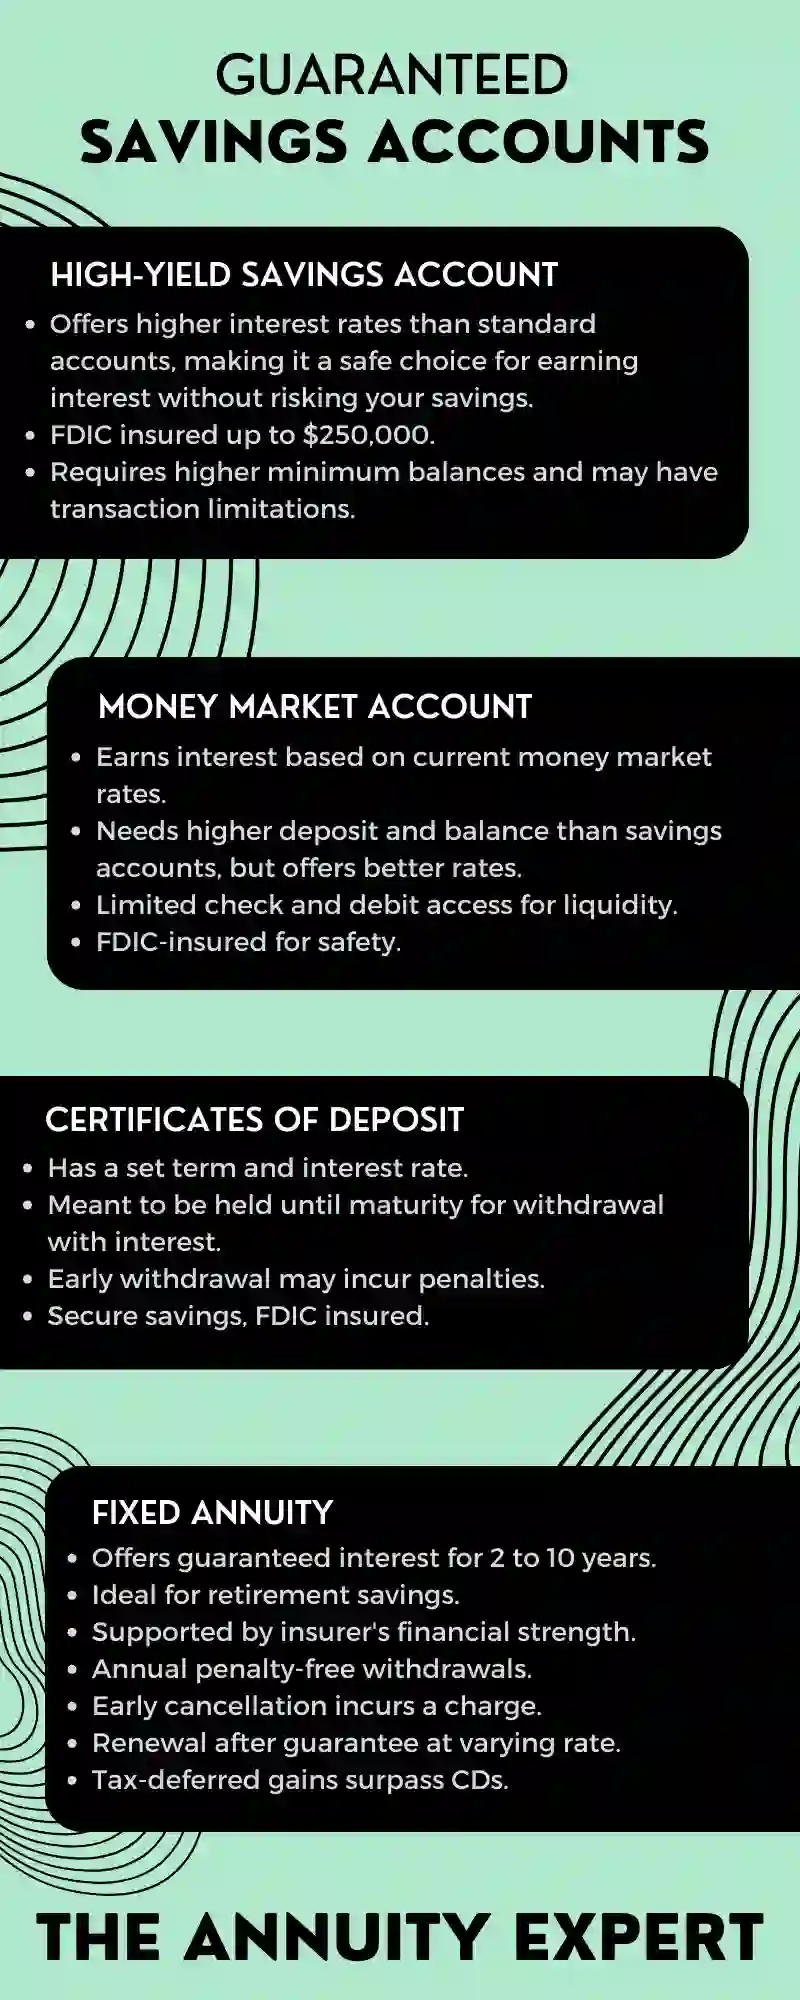
Who Each Option Is Best For
MYGAs (Multi-Year Guaranteed Annuities)
- Who benefits
- Savers who won’t need the money for a set term and want a predictable fixed rate
- Tax-aware investors who prefer deferring taxes on interest until later
- Near-retirees using safe yields to bridge to retirement or ladder guaranteed terms
- Who might not
- Anyone needing frequent access to cash (emergency fund, irregular expenses)
- People uncomfortable with surrender charges or age-based IRS rules on withdrawals
Savings Accounts
- Who benefits
- Households building or maintaining an emergency fund
- People who value same-day access and no withdrawal restrictions
- Short-term savers planning to spend the money within months, not years
- Who might not
- Long-term savers seeking higher, locked-in yields and tax deferral
- Those frustrated by fluctuating rates and annual taxation on interest
Pros & Cons
MYGAs
- Pros
- Fixed, contractually guaranteed rate for the entire term
- Tax-deferred growth can compound more efficiently for long-term goals
- Works well in a ladder for predictable future cash needs
- Cons
- Limited liquidity; withdrawals can trigger surrender charges and tax rules
- Not designed for everyday spending
- Early-access rules may apply if under the IRS’s age threshold
Savings Accounts
- Pros
- Instant access; no surrender schedule
- Simple to manage; ideal for emergency funds
- FDIC insurance up to program limits
- Cons
- Typically lower, variable rates
- Interest taxed each year, which reduces net growth
- Easy access can tempt overspending on long-term savings
Practical Tips To Decide (And Save Money)
- Match money to its job
Keep 3–6 months of expenses in a savings account for emergencies. Use MYGAs for money you won’t need during the annuity term. - Consider a ladder, not a lump
Split funds across multiple MYGA terms so portions mature each year—better liquidity without giving up guaranteed rates. - Mind the fine print
Check free-withdrawal allowances, market value adjustment (MVA) clauses, and surrender schedules before you buy. - Think taxes before you move cash
Weigh annual taxation in savings versus tax-deferred compounding in a MYGA. - Keep flexibility
If you’re unsure about timing, start with a shorter MYGA term or put part in savings and part in a MYGA.

Next Steps: Pick The Right Tool For Your Cash
Decide what the money is for, when you’ll need it, and how much access you want. Keep true emergency funds in savings for instant availability. Use a MYGA to lock in a fixed rate and defer taxes on dollars earmarked for future goals. If you’re on the fence, start with a smaller MYGA or a ladder so you keep flexibility while improving your yield.
Ready to match your cash to the right place? Schedule a quick call with The Annuity Expert to compare current MYGA options against your savings plan and get a clear, low-friction path forward.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.