

How to Avoid Paying Tax on Your Pension
If you’re facing a taxable pension payout, you don’t have to accept a big tax bill as inevitable. There are legal strategies to reduce or defer taxes on pension money — rollovers, annuities, Roth conversions, life insurance, and even long-term care insurance funding. Below, you’ll learn every method that can help you reduce taxes while protecting your retirement income. Each option is explained with how it works, its pros and cons, who it’s best for, and what to avoid.
Method 1: Roll Your Pension into a Qualified Annuity (Rollover)
How it works and why it’s unique:
A pension lump sum can be rolled into a qualified annuity or IRA to defer taxes. You avoid immediate taxation by keeping the funds inside a qualified account, and an annuity can add contractually guaranteed lifetime income or death benefits.
Pros:
• Defers taxes until withdrawals.
• Adds lifetime income via a GLWB (without annuitizing).
• Avoids immediate lump-sum tax bill.
Cons:
• Surrender charges and fees are possible.
• Withdrawals taxed as ordinary income.
• Some riders add cost and complexity.
Who needs it:
Retirees who want to preserve tax deferral and add income guarantees.
Who doesn’t:
Those who need short-term access or prefer self-directed investing.
Funding options:
Qualified rollovers from a pension, 401(k), or 403(b) into a Traditional IRA or qualified annuity.
Method 2: Use a Fixed Indexed Annuity (FIA) with a GLWB
How it works and why it’s unique:
An FIA protects the principal while earning indexed interest. A GLWB rider provides guaranteed lifetime income — an alternative to pension annuitization. It can be funded by a pension rollover or non-qualified funds.
Pros:
• Market-linked growth potential with downside protection.
• Contractually guaranteed lifetime income.
• Tax deferral.
Cons:
• Surrender periods limit liquidity.
• Rider fees can reduce growth.
• Renewal rates may adjust.
Who needs it:
Those wanting a predictable lifetime income without full annuitization.
Who doesn’t:
Short-term investors or those uncomfortable with fees.
Funding options:
Qualified rollovers or non-qualified savings.
Method 3: Convert to a Roth IRA (Roth Conversion)
How it works and why it’s unique:
Pay taxes now on converted funds so future withdrawals are tax-free. This can reduce Required Minimum Distributions (RMDs) later.
Pros:
• Tax-free future withdrawals.
• Reduces RMDs.
• Great estate transfer tool.
Cons:
• Immediate tax bill.
• May raise your current-year tax bracket.
Who needs it:
People expecting higher tax rates later or wanting tax-free legacy money.
Who doesn’t:
Those unable to cover conversion taxes.
Method 4: Buy a QLAC (Qualified Longevity Annuity Contract)
How it works and why it’s unique:
A QLAC delays income payments and reduces RMDs. You can buy one inside a Traditional IRA or 401(k). It’s ideal for those worried about outliving their assets.
Pros:
• Reduces RMD tax base.
• Defers income until later years.
• Contractually guaranteed lifetime income.
Cons:
• Funds are locked up until income starts.
• Rigid contract terms.
Who needs it:
Those with large IRAs want to lower current RMDs and secure future income.
Who doesn’t:
People who need flexibility or smaller account holders.

Method 5: Fund Permanent Life Insurance
How it works and why it’s unique:
Use your pension proceeds to fund a cash-value life insurance policy. Growth is tax-deferred, and loans are generally tax-free. The death benefit is typically income-tax-free to beneficiaries.
Pros:
• Tax-free death benefit.
• Tax-deferred growth.
• Cash-value access via policy loans.
Cons:
• Premiums can be high.
• Mismanagement may cause lapses and taxes.
Who needs it:
People who want tax-efficient legacy planning.
Who doesn’t:
Those seeking pure investment growth or full liquidity.
Method 6: Fund Long-Term Care Insurance
How it works and why it’s unique:
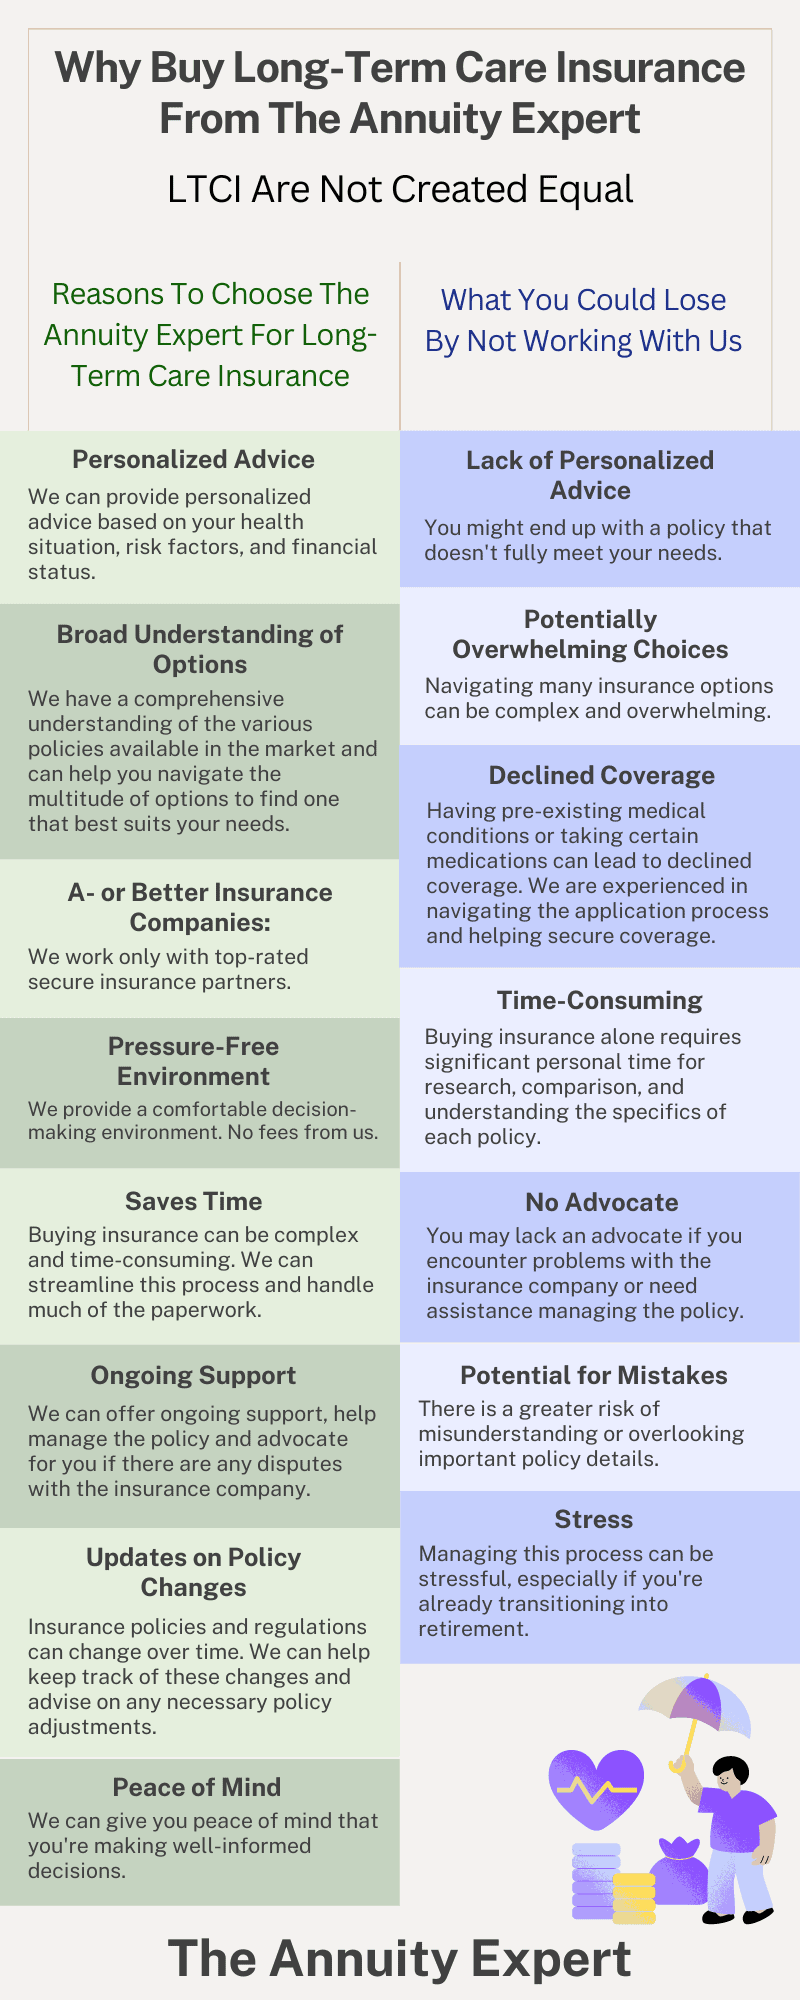
You can use your pension or IRA distributions to buy long-term care insurance (LTCI). Premiums protect your assets from nursing home, assisted living, or in-home care costs — expenses Medicare doesn’t cover. For some taxpayers, premiums are tax-deductible up to IRS limits depending on age and income.
Pros:
• Protects retirement savings from future care costs.
• Potential tax deduction on premiums (varies by age and policy type).
• Hybrid life and long-term care policies can offer death benefits if care isn’t needed.
Cons:
• Premiums increase with age.
• Health underwriting required.
• Standalone LTC policies may lapse unused if care isn’t needed.
Who needs it:
Retirees worried about future long-term care costs or asset depletion.
Who doesn’t:
Those with very low assets (Medicaid eligible) or high net worth who can self-insure.
Funding options:
• Use partial pension distributions, annuity withdrawals, or non-qualified funds.
• Hybrid LTC annuities or life policies allow 1035 exchanges or IRA rollovers with tax advantages.
Tip: If premiums are tax-deductible, you can offset some or all of the tax cost from a pension withdrawal.
Method 7: Take Systematic Withdrawals
How it works and why it’s unique:
Take smaller distributions over time to spread taxes out and stay in a lower bracket. You can pair this with partial Roth conversions or LTC premium payments.
Pros:
• Manages tax brackets.
• Reduces Medicare premium surcharges.
• Offers flexibility.
Cons:
• Requires discipline.
• Market downturns may reduce balances.
Action Steps
- Avoid cashing out your pension without a plan.
- Talk to both a CPA and an insurance agent. Coordinate tax planning with annuity, LTC, and life insurance product selection.
- Compare quotes. Not all annuities or LTC policies are equal — use a broker to shop A-rated carriers.
- Mix methods. Combine a Roth conversion, annuity with GLWB, and LTC insurance to balance taxes, income, and protection.
Why Work With An Agent
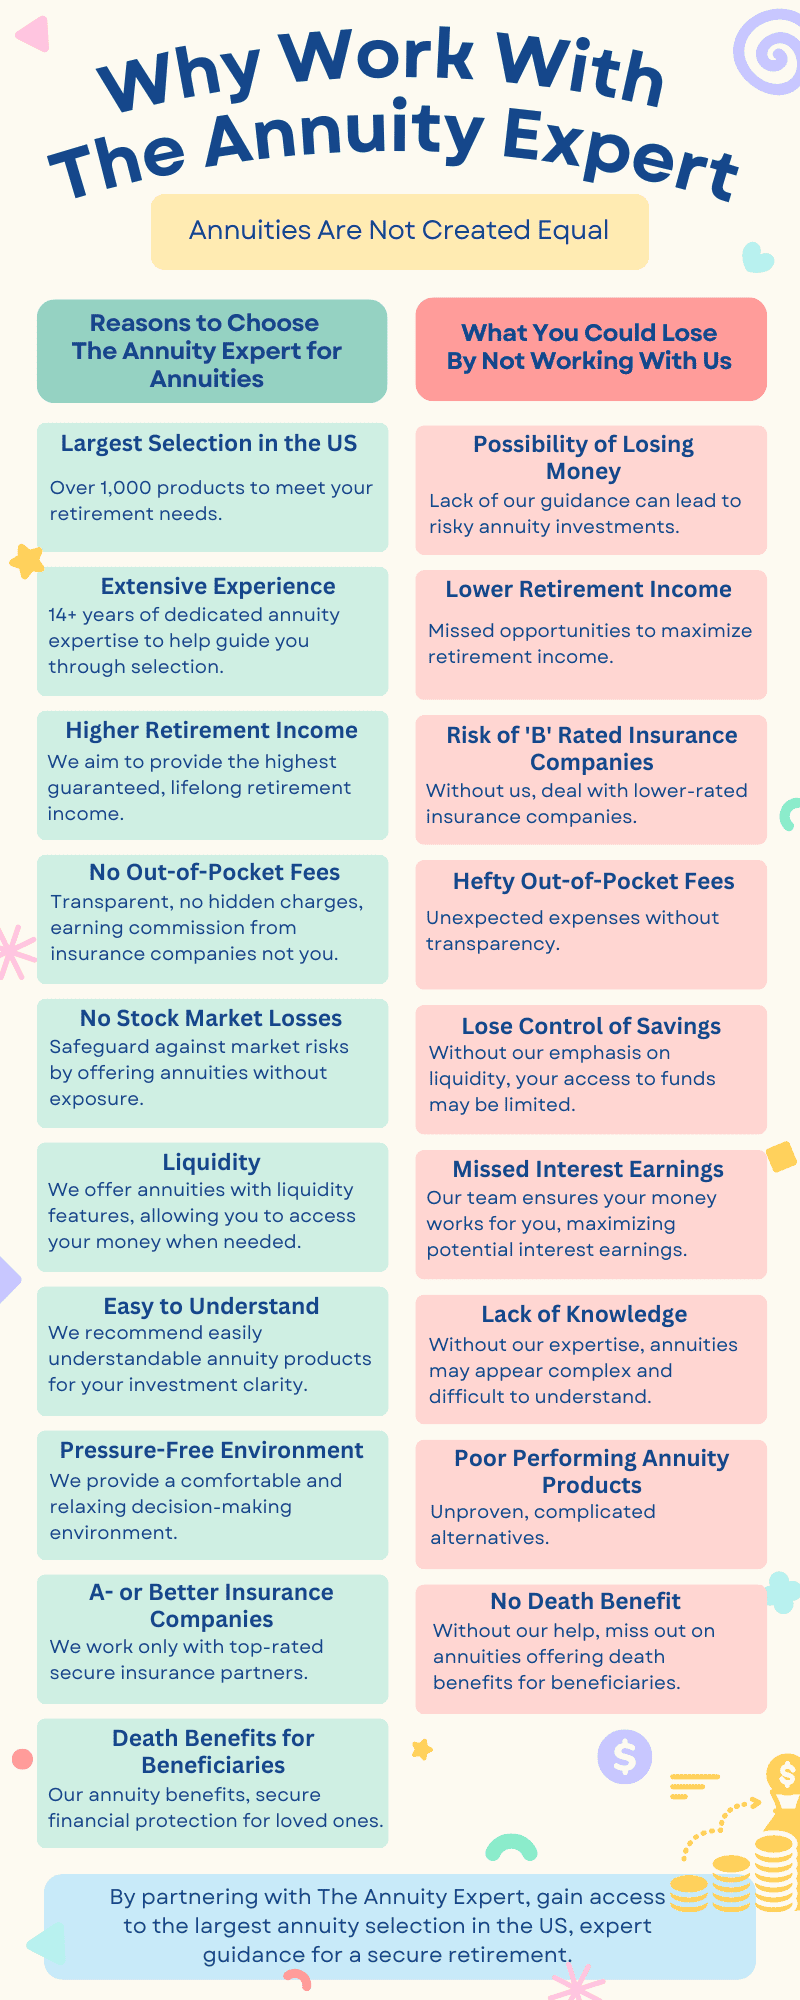
Agents help you compare carriers, tax implications, and policy designs. The Annuity Expert is an independent agency that represents you, not the insurer. We’ll show you the tradeoffs between annuities, life insurance, and long-term care options — so you don’t overpay.
Contact The Annuity Expert for free quotes:
Get a free, no-pressure consultation to compare tax-saving pension rollover options, annuities, Roth conversions, life insurance, and long-term care coverage. Learn how to structure your income and protect your assets for life.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.