

American Equity IncomeShield 10 Annuity Review
The American Equity IncomeShield 10 is a fixed indexed annuity designed primarily for guaranteed lifetime income. It combines principal protection, contractually guaranteed growth of a separate Income Account Value, payout factors that increase while income is deferred, and a Wellbeing Benefit for qualifying health events.
The current product is an income annuity first. Its index-linked growth potential is secondary and should be evaluated in the context of the lifetime-income guarantee.
Our Professional Opinion on the American Equity IncomeShield 10 Annuity
We recommend the American Equity IncomeShield 10 when its actual guaranteed lifetime-income payout is competitive with the other A- or better-rated income annuities available for the buyer’s age, state, premium, and desired income start date.
We like the basic income-rider design. IncomeShield 10 uses a separate Income Account Value, or IAV, that receives contractually guaranteed growth while income is deferred. The applicable payout factor also increases as the buyer waits to begin lifetime withdrawals.
That is the type of income design we generally prefer. We would rather know how the income calculation value grows than depend entirely on future index performance to determine whether the projected retirement paycheck develops.
The IAV is not cash. It is a measuring value used to calculate lifetime income. You cannot surrender the annuity and receive the IAV as a lump sum.
We therefore do not judge IncomeShield 10 by the size of the IAV or the payout factor shown in isolation. The only number that ultimately matters is the guaranteed annual income the contract will pay.
If American Equity is producing one of the strongest guaranteed payouts available, we think IncomeShield 10 is a good product. If another financially strong insurer pays materially more for the same premium and start date, we would choose the higher-paying annuity.
The current accumulation rates are not the best in the FIA market, but they are on the higher end for an income-focused annuity. That is an important distinction.
We would not buy IncomeShield 10 when maximum account-value growth is the primary objective. An accumulation-focused FIA can offer stronger crediting terms because it is not dedicating as much of the product economics to a guaranteed income rider.
However, IncomeShield 10 does not completely stink on growth the way some income annuities do. The current product provides true S&P 500, Nasdaq-100, and Dow Jones Industrial Average strategies, and its traditional-index terms are reasonably competitive for a contract built primarily around lifetime income.
That makes the product a better balance than an income FIA where nearly all of the upside is concentrated in engineered indexes with awful traditional-index options.
There are still important limitations. American Equity can change future caps, participation rates, performance-trigger rates, and the declared fixed rate at renewal. IncomeShield 10 is not a cap-lock annuity, and the fixed account is not a MYGA.
The product also offers several proprietary and volatility-controlled indexes. We would not chase a larger participation rate on an engineered index merely because the number looks impressive. The index methodology, live date, volatility controls, excess-return deductions, and actual live history all matter.
The annual rider charge deserves attention because it is based on the IAV and deducted from the contract value. The IAV can grow faster than the account value, so the dollar amount of the charge can become meaningful over time.
That fee is acceptable when the product is delivering a competitive lifetime-income guarantee. It is not acceptable when another carrier will pay more income with a lower fee or a better overall contract.
We also like that lifetime income can begin after the first contract year once the applicable age requirement is met. The buyer is not forced to wait a full decade before accessing the rider.
The Wellbeing Benefit can provide enhanced income for up to five years when the owner meets the activities-of-daily-living requirements. It does not require confinement, which is a meaningful positive.
However, it can only be activated once, requires ongoing certification, and is not a replacement for actual long-term care insurance.
Our bottom line is straightforward: IncomeShield 10 is a good income annuity when the payout is comparable or better than the market. Its cash-value rates are not the best, but they are respectable for an income-focused FIA. Buy it for the guaranteed paycheck, not because you expect it to be the highest-growth accumulation annuity.
Compare IncomeShield 10 With Today’s Best Fixed Indexed Annuities
The strongest income annuity changes as carriers adjust payout factors, rider terms, fees, and crediting rates.
What We Like
- Guaranteed IAV Growth: The Income Account Value grows at a contractually defined rate while income is deferred.
- Increasing Payout Factors: The lifetime-income payout factor increases as the buyer waits to begin income.
- Income Can Begin After One Year: Eligible owners can start lifetime withdrawals relatively soon instead of waiting through the full surrender period.
- Competitive Income Potential: The product can produce strong guaranteed payouts for certain ages and income start dates.
- Above-Average Growth for an Income FIA: The current crediting terms are not top-tier for accumulation but are on the higher end among income-focused annuities.
- Traditional Index Choices: The product includes the true S&P 500, Nasdaq-100, and Dow Jones Industrial Average.
- Wellbeing Benefit: Qualifying ADL limitations can provide enhanced income for a defined period without requiring confinement.
- Joint Lifetime Income: The contract can continue payments through the life of the surviving spouse when properly structured.
- Principal Protection: Negative index performance does not directly reduce the contract value.
- Annual Liquidity After Year One: The contract provides penalty-free access to a portion of contract value after the first year.
- RMD Friendly: Applicable required minimum distributions receive favorable treatment under the rider provisions.
- Nursing Home and Terminal Illness Access: The no-fee Enhanced Benefit Rider can waive normal surrender restrictions for qualifying events.
- Strong Insurance Company: American Equity meets our A- or better financial-strength requirement.
What We Don’t Like
- The Payout Still Has to Be Competitive: A good rider design does not justify accepting less lifetime income than another strong carrier will pay.
- IAV Is Not Cash: The Income Account Value cannot be surrendered or withdrawn as a lump sum.
- Rider Fee Is Based on the IAV: The charge is deducted from contract value and can grow in dollar terms as the IAV grows.
- Not the Best Accumulation Rates: The growth potential is respectable for an income FIA but weaker than the strongest accumulation-focused products.
- Renewal Rate Risk: American Equity can change caps, participation rates, triggers, and the fixed rate at renewal.
- Engineered Index Complexity: Several strategies use proprietary, volatility-controlled, or excess-return indexes.
- Wellbeing Benefit Is Temporary: The enhanced payment is limited to a defined period and can only be activated once.
- Standard Death Benefit: Beneficiaries generally receive the contract value rather than an enhanced income-base death benefit.
- No Standard First-Year Free Withdrawal: Normal penalty-free access to contract value begins after the first year.
- Long Surrender Period: The product has a ten-year surrender schedule and an MVA.
- No Cap Lock: The product does not guarantee the current traditional-index cap for the entire surrender period.
Our bottom line: IncomeShield 10 is a good guaranteed-income annuity when its actual payout is competitive. We like the contractual IAV growth and rising payout factors. The rates are not the best for pure accumulation, but they are on the higher end for an income-focused FIA. Buy it for income—not maximum growth.
American Equity IncomeShield 10 Product Details
| Product Type | Fixed Indexed Annuity With Lifetime Income Benefit Rider |
| Primary Purpose | Guaranteed Lifetime Income |
| Surrender Period | 10 Years |
| Issue Ages | Generally ages 40 through 80 |
| Income Account Value | Separate value used solely to calculate lifetime income |
| IAV Growth | Contractually guaranteed daily growth for up to the stated accumulation period |
| Income Start | Generally after one contract year and once the owner reaches the applicable minimum age |
| Income Structure | Single or joint lifetime income using the applicable IAV and payout factor |
| Rider Charge | Annual charge based on the IAV and deducted from contract value |
| Wellbeing Benefit | One-time enhanced income period for qualifying ADL limitations |
| Free Withdrawals | Annual penalty-free access beginning after the first contract year |
| Market Value Adjustment | Yes |
| Death Benefit | Generally the applicable contract value without surrender charges |
| Index Choices | Traditional S&P 500, Nasdaq-100, Dow Jones Industrial Average, and proprietary strategies |
American Equity is a good annuity company. Current company materials list A financial-strength ratings from AM Best, Fitch, and Standard & Poor’s. That comfortably exceeds our A- minimum. Our recommendation therefore depends on the competitiveness of the IncomeShield payout and product terms—not concern about the insurer’s financial strength.

How the Income Account Value Works
The IncomeShield 10 tracks both a contract value and an Income Account Value.
- Contract Value: The actual account value used for withdrawals, surrender, and the standard death benefit.
- Income Account Value: A separate calculation value used to determine lifetime income under the rider.
The IAV receives guaranteed daily growth while lifetime income is deferred, subject to the rider’s time limits. The payout factor also increases with each completed contract year before income begins.
Once lifetime income starts, American Equity applies the locked payout factor to the applicable IAV or contract value under the rider formula.
Do not confuse IAV growth with investment growth. A larger IAV can produce more guaranteed income, but it is not money the owner can take as a lump sum.
When Can Lifetime Income Begin?
Lifetime income can generally begin after the first contract year once the owner reaches the applicable minimum age.
The longer the buyer waits, the more time the IAV has to grow and the higher the payout factor may become.
This gives the product legitimate flexibility for someone who wants income soon as well as someone planning several years ahead.
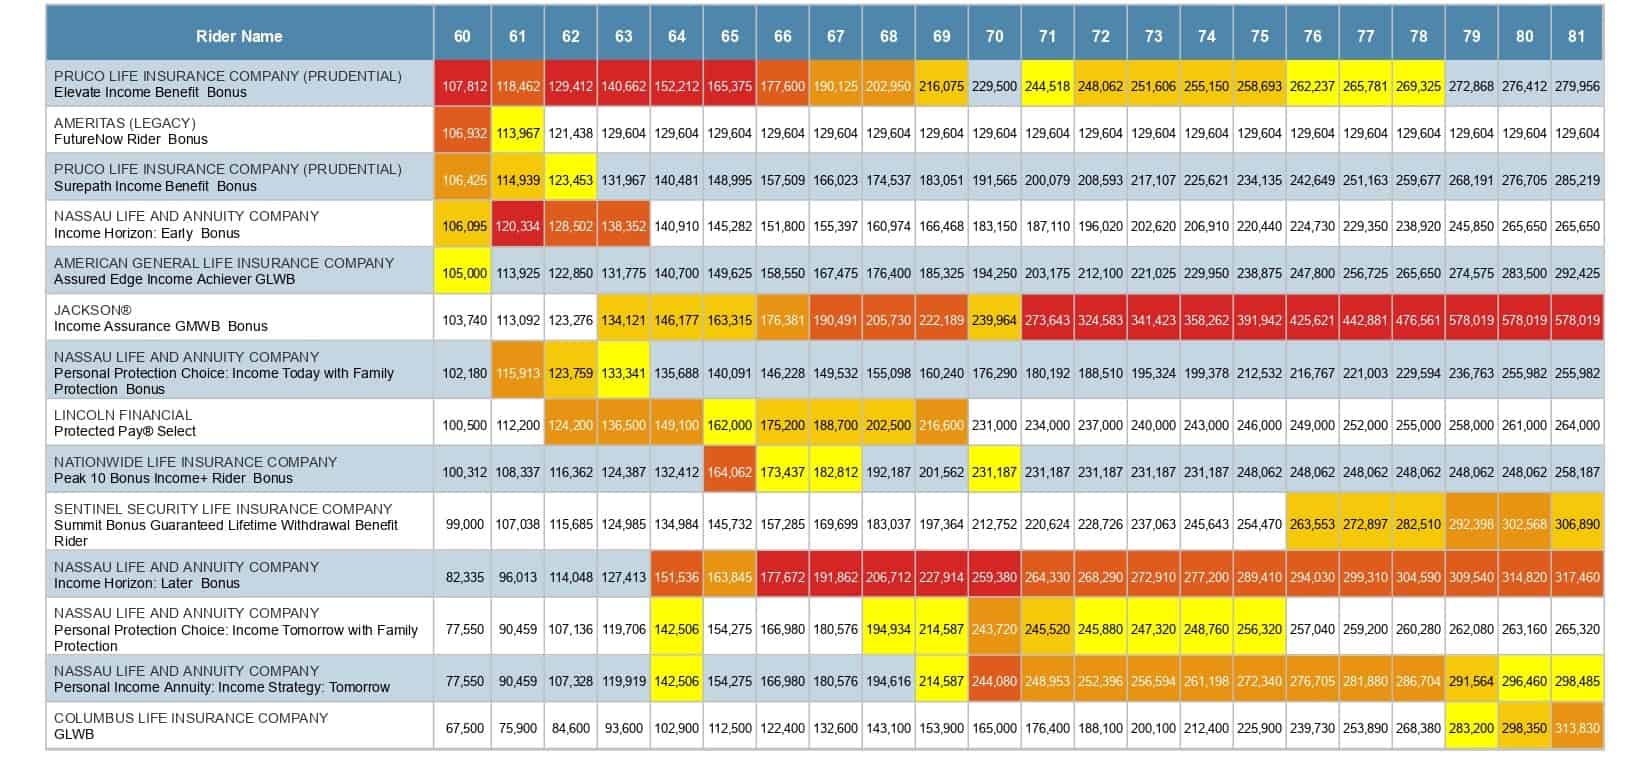
Compare IncomeShield 10 Payouts
The payout determines whether IncomeShield 10 is a good purchase. Compare the actual guaranteed annual income against the entire A- or better-rated annuity market.
Contact us for a custom annuity income heat map based on your age, state, premium, income start date, and single- or joint-life needs.
IncomeShield 10 Growth Potential
IncomeShield 10 offers a fixed-interest strategy and several index-linked crediting options.
The traditional index menu includes the true S&P 500, Nasdaq-100, and Dow Jones Industrial Average. Additional options use proprietary or volatility-controlled indexes from BlackRock, Nasdaq, NYSE, and S&P.
Crediting methods include caps, participation rates, performance triggers, and one- or multi-year strategy terms.
The current growth terms are respectable for an income annuity but not the best in the accumulation market. That is acceptable when the income payout is strong because the guaranteed income is the reason to own the contract.
American Equity can change future caps, participation rates, triggers, and the fixed-account rate. Buyers who want crediting terms that cannot be reduced should compare annuities designed to avoid renewal-rate drops.
Income Rider Fee
The Lifetime Income Benefit Rider charges an annual fee based on the IAV. The fee is deducted from contract value each year while the rider remains attached.
Because the IAV can grow faster than the contract value, the dollar amount of the fee can become larger over time.
We would accept that fee when the guaranteed lifetime-income payout is competitive. We would not pay it merely because the IAV illustration looks impressive.
Wellbeing Benefit
The Wellbeing Benefit can enhance lifetime income after the applicable waiting period when the owner is unable to perform at least two activities of daily living.
No confinement is required under the current product description. The enhanced income can continue for up to five years, subject to eligibility and annual certification.
The benefit can only be activated once. After the enhanced period ends, the normal guaranteed lifetime-income payment resumes.
Liquidity and Health-Related Access
After the first contract year, IncomeShield 10 generally permits annual penalty-free withdrawals of a portion of contract value.
Withdrawals above the free amount can be subject to surrender charges and a Market Value Adjustment.
The no-fee Enhanced Benefit Rider can provide a one-time withdrawal of contract value for qualifying nursing-home confinement or terminal illness after the applicable waiting period.
Buyers who prioritize access should compare the best annuities for liquidity before purchasing a ten-year income contract.
Death Benefit and Spousal Continuation
The standard death benefit is generally based on the contract value rather than the IAV.
A surviving spouse may be able to use spousal continuation to maintain the contract and continue the income plan.
If leaving the largest possible inheritance is the primary objective, compare products specifically designed for enhanced death benefits.
Retirement Accounts Accepted
- Non-Qualified Funds
- Traditional IRA
- IRA Rollovers and Transfers
- SEP IRA
- Roth IRA
- TSP Rollovers
- 1035 Exchanges
- Inherited IRAs
Who Should Consider IncomeShield 10?
- Someone Seeking Guaranteed Lifetime Income: Your primary goal is a contractual retirement paycheck you cannot outlive.
- Someone Deferring Income: You value guaranteed IAV growth and increasing payout factors while you wait.
- Someone Starting Income Soon: The current American Equity payout is competitive and you want income after the first contract year.
- Someone Who Wants a Balance of Income and Growth: You want better accumulation potential than many income FIAs without making growth the primary objective.
- Someone Who Values Health-Related Income: The Wellbeing Benefit is meaningful to your retirement plan.
- Someone With Adequate Liquidity Elsewhere: You can leave the money in a ten-year contract.
Who Should Probably Buy Something Else?
- Someone Seeking Maximum Safe Accumulation: An accumulation-focused FIA may provide stronger crediting terms.
- Someone Whose Income Quote Is Not Competitive: Another A- or better-rated carrier may provide more guaranteed lifetime income.
- Someone Who Dislikes Income-Base Fees: The rider charge is based on the IAV rather than only the contract value.
- Someone Who Wants a Cap Lock: Current traditional-index rates can change at renewal.
- Someone Focused Primarily on Legacy: The IAV is not an enhanced death-benefit value.
- Someone Needing Strong Early Liquidity: Normal penalty-free access begins after the first year.
What We Recommend
We recommend IncomeShield 10 when its guaranteed lifetime-income payout is comparable with or better than the rest of the A- or better-rated market.
We like the guaranteed IAV growth, increasing payout factors, ability to start income after one year, and above-average accumulation potential for an income-focused annuity.
We do not like the IAV-based rider fee, renewal-rate risk, engineered-index complexity, or the fact that the product is still weaker for accumulation than a dedicated growth FIA.
Buy IncomeShield 10 for lifetime income. Treat the relatively good growth rates as a secondary benefit, not the reason to purchase the annuity.
Contact The Annuity Expert for free quotes and a no-obligation comparison. We will compare the actual guaranteed payout, rider fee, index choices, liquidity, Wellbeing Benefit, and insurer strength.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Related Reviews
- Pacific Life Pacific Income Provider
- F&G Safe Income Advantage Annuity
- Midland Income Planning Annuity
- Integrity Life Income Source Annuity
- Symetra Freedom Income Annuity
- Lincoln Financial Insured Income Annuity
- Allianz Benefit Control Annuity
- Nationwide Income Promise Select Annuity
- American Equity Immediate Annuity
- Athene Agility Annuity