

Our Integrity Life Income Source Annuity Review
The Integrity Life Income Source Annuity has become popular for individuals seeking reliable retirement income and financial security. With the ever-growing concern of not having enough money to support their retirement, many people are turning to this annuity offered by Integrity Life Insurance Company and National Integrity Life Insurance Company.
This single premium immediate annuity provides a guaranteed stream of lifetime income, giving individuals peace of mind and eliminating the worry of running out of money in retirement. It offers flexible retirement income options, allowing individuals to choose different payout frequencies and options that align with their unique financial goals and needs.
How the IncomeSource SPIA Works
You make a one-time lump-sum payment and receive regular income starting within 30 days to one year. Income payments can be based on your lifetime, two lives, or for a certain period (e.g., 5–30 years). Once the contract is active, you cannot withdraw the premium, surrender the policy, or change the payment schedule.
The annuity offers two powerful enhancements:
- Commutation Benefit: Allows you or your beneficiaries to cash out a portion of future guaranteed payments under specific conditions.
- Guaranteed Increasing Payout Option (IPO): Choose annual increases of 1%–5% to hedge against inflation.
Types Of Retirement Accounts Accepted
- Non-Qualified
- IRA
- 401(K)
- IRA Transfer
- IRA Rollover
- SEP IRA
- IRA-Roth
- TSP
- Stretch IRA
- 403(B)
- 1035 Exchange
Pros and Cons
✅ Pros
- Lifetime Income: Offers dependable payments for life or for a set period.
- Inflation Hedge: The IPO boosts your income annually (up to 5%) without relying on market indexes.
- Commutation Access: You can access a portion of future payments for emergency liquidity.
- Issue Age Flexibility: Available up to age 95 depending on payout type.
- No Market Risk: Payments are unaffected by stock or bond performance.
- Carrier Strength: Backed by Western & Southern Financial Group’s financial stability.
❌ Cons
- Commutation Limitations: Not available with life-only or short-term (under 10 years) options.
- No Liquidity on Premium: Once you purchase it, your lump sum is inaccessible except through scheduled income.
- Irrevocable Contract: You cannot adjust the income stream after the contract begins.
- No Growth Potential: Fixed income—does not participate in market gains.
- IPO Reduces Initial Payouts: Choosing the increasing income feature lowers your starting income.
Who Needs the IncomeSource SPIA
- Early Retirees Under Age 59½ (Non-Qualified Funds): Especially those needing immediate income without a 10% IRS penalty—best used with a life-only SPIA paired with a permanent life insurance policy.
- Conservative Retirees: Who want simple, guaranteed income with no market exposure.
- Couples Seeking Joint Income: Joint life and survivorship options can secure income for both spouses.
- Those with a Defined Time Horizon: Such as bridging income to Social Security or RMDs.
Who Should Avoid This SPIA
- Those Needing Ongoing Flexibility: Payment terms and options are locked in once selected.
- People Who May Need the Principal: This product is illiquid—unsuitable if you may need the money later.
- Investors Looking for Growth: There’s no investment upside beyond optional income increases.
- Younger Individuals: Who would benefit more from tax-deferred growth or accumulation-based products.
Compare Integrity Life Annuity Income
Determine if Integrity Life annuities provide the highest income below.
Why You Must Compare Products First
Income annuities can vary dramatically in payout rates, features, and liquidity. Some offer higher income but no flexibility; others sacrifice income for access. It’s critical to compare quotes from multiple carriers to ensure you get the highest payout and best protection for your situation.
Other Insurance and Annuity Options to Consider
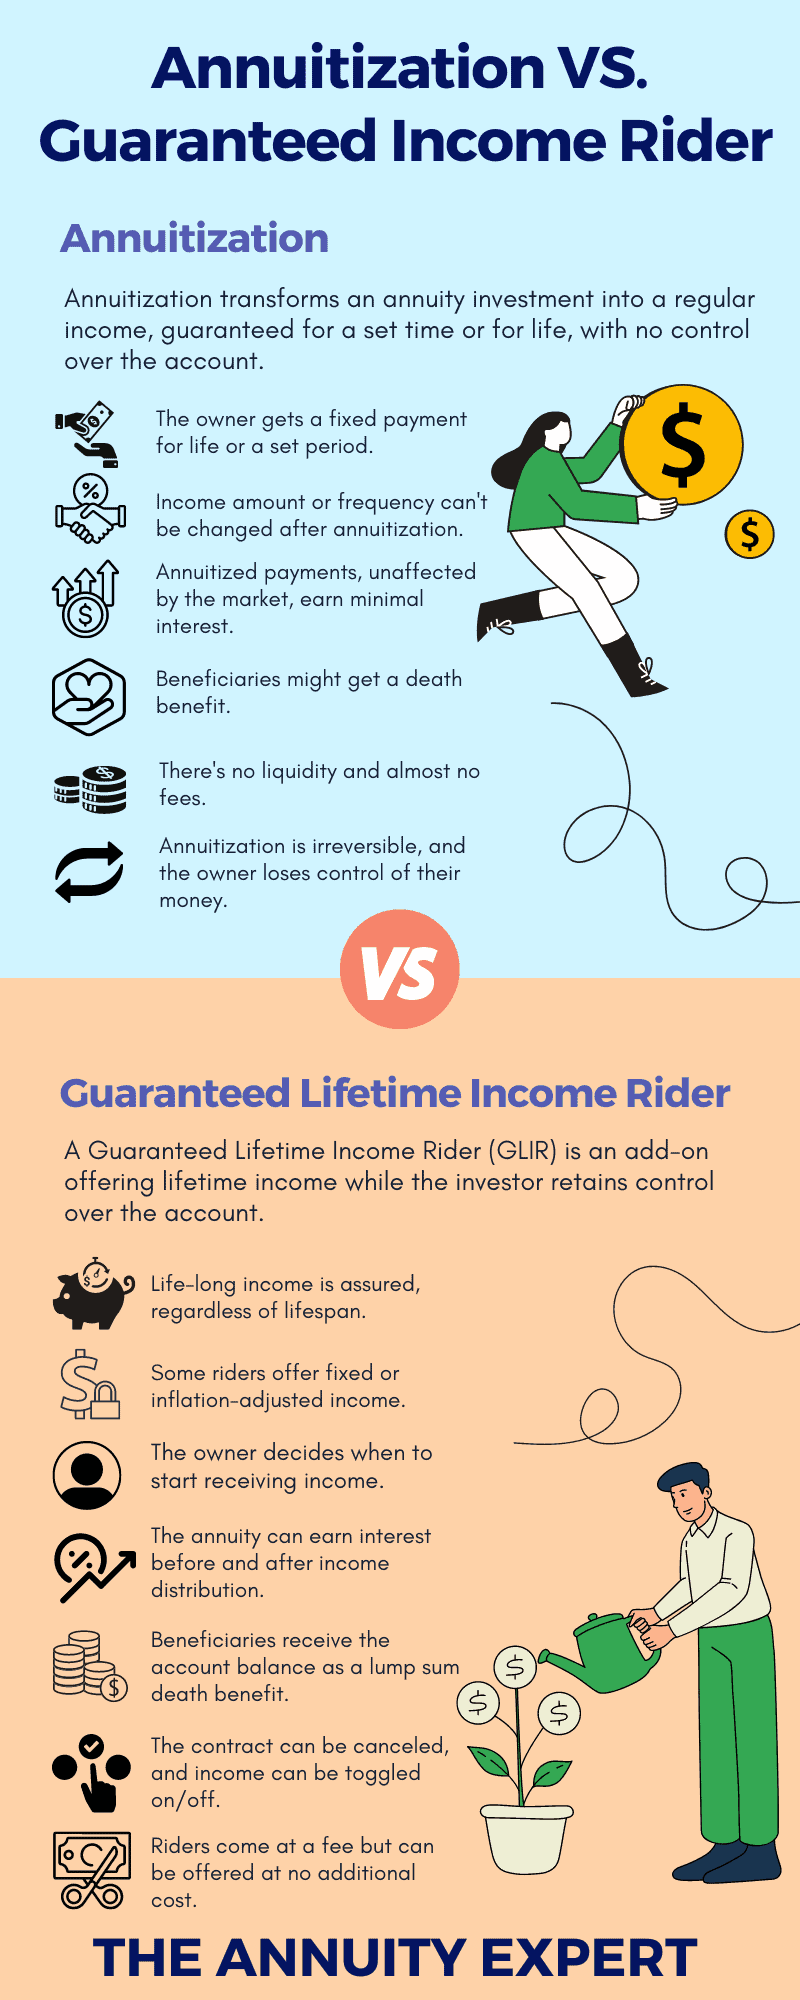
- GLWB Annuities (Guaranteed Lifetime Withdrawal Benefit): Offers lifetime income without giving up control of your money. Ideal for those needing future income with growth potential.
- Deferred Income Annuities (DIAs): Similar income benefits, but payments start later.
- MYGAs (Multi-Year Guaranteed Annuities): A fixed-interest alternative that provides guaranteed growth before converting to income.
- Life Insurance: Essential for those using life-only SPIAs to ensure beneficiaries receive value if the annuitant dies early.
Final Verdict
The IncomeSource SPIA works best for conservative retirees or early retirees needing immediate guaranteed income, particularly if they can pair it with a life insurance policy. But its rigidity, lack of growth, and loss of control make it a poor fit for many others. If you value flexibility and future-proofing, a GLWB annuity or a MYGA might be a better solution.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Related Reviews
- Are Canvas Annuities Any Good
- Pacific Life Pacific Income Provider
- Is Brighthouse Shield® Level Annuities Any Good?
- Is Nex Multi-Year Guaranteed Annuity (MYGA) by The Ohio State Life Insurance Company Any Good?
- Fidelity and Guaranty Safe Income Advantage Annuity
- Midland Income Planning Annuity
- Symetra Freedom Income Annuity
- Is Jackson Fixed Annuities Any Good?
- Lincoln Financial Insured Income Annuity
- Allianz Benefit Control Annuity
- Nassau Protection Choice Annuity
- Nationwide Income Promise Select Annuity
- EquiTrust Market Power Bonus Index Annuity
- Athene Agility Annuity
- Athene Max Rate Fixed Annuity
- TIAA
- Is The FERS Annuity a Good Idea
- Are Fidelity Annuities Any Good?
- Is The IncomeShield 10 Fixed Index Annuity Any Good?
- Transamerica Annuity Review
- Is the Allianz 222® Annuity Any Good?
- Is The Oceanview Fixed Indexed Annuity Any Good?
- Is Allianz Core Income 7® Annuity with Core Income Benefit Rider Any Good?
- American Equity Annuity Reviews
- Is Oceanview Life And Annuity A Good Annuity Company?
- Is Fidelity’s Immediate Annuity Any Good?