

Our Professional Opinion on the Guardian Fixed Target Annuity
We recommend the Guardian Fixed Target Annuity when its guaranteed rate is competitive. Guardian is one of the strongest insurance companies in the market, so company strength is not a concern with this product.
Fixed Target currently offers 3-, 4-, 5-, and 6-year guarantee periods. The rate can also vary by premium amount, with larger deposits generally receiving a better rate.
In today’s high-interest-rate environment, locking a competitive 5- or 6-year rate with a company like Guardian can be a great choice if you do not need the money. This is exactly where a longer MYGA can make sense: you know the rate, you know the term, and you reduce the risk of reinvesting at lower rates later.
Guardian also has very good liquidity. The current contract provides penalty-free access to a portion of the account beginning in the first contract year, which is better than many MYGAs.
One of our favorite features is what happens when the initial term ends. If you do nothing, the money moves into a one-year guaranteed interest period with no surrender charge. That is much better than an annuity that automatically starts another multi-year surrender schedule because you missed a short renewal window.
That one-year option gives you time to compare the market. If rates are still attractive, you can choose another available guarantee period. If another company is paying more, you can move the money without being trapped in a new long surrender schedule.
We also like the full account-value death benefit and spousal continuation provisions. Overall, this is a clean MYGA from an exceptionally strong insurer.
Bottom line: Guardian Fixed Target is a very good MYGA when the rate is near the top of the market. We especially like it for someone who wants strong insurer quality, first-year liquidity, and a consumer-friendly maturity process.
Compare Guardian Fixed Target with the current fixed annuity rates before selecting the guarantee period.
What We Like
- Excellent Insurance Company: Guardian is one of the strongest-rated annuity insurers in the market.
- 3-, 4-, 5-, and 6-Year Terms: Buyers can choose between flexibility and a longer rate lock.
- First-Year Penalty-Free Access: A portion of the account is available during the first contract year.
- Premium-Band Pricing: Larger deposits may qualify for stronger guaranteed rates.
- One-Year Default at Maturity: If you do nothing, the contract moves into a one-year period without restarting a long surrender schedule.
- Full Account-Value Death Benefit: Beneficiaries receive the accumulation value under the standard death-benefit provision.
- Spousal Continuation: A surviving spouse can continue the contract under the applicable rules.
What We Don’t Like
- The Rate Still Has to Win: We would not accept a materially lower rate solely because the insurer is Guardian.
- Premium Bands Matter: Smaller deposits may receive a lower guaranteed rate than larger contracts.
- Longer Terms Reduce Flexibility: The 5- and 6-year contracts only make sense when the money can remain untouched.
Guardian Fixed Target Annuity Overview
What Is The Guardian Fixed Target Annuity?
The Guardian Fixed Target Annuity is a single premium deferred annuity product. In simpler terms, you make a one-time payment, and your investment grows at a fixed interest rate over a specified period. After the initial term, you have the option to renew the contract for additional periods.
Purchase Payment
The minimum amount required to invest in the Guardian Fixed Target Annuity is $5,000. While this may be manageable for many, the maximum cap is set at $1 million without additional approval. It’s important to note that you cannot make additional payments after the initial investment, so careful consideration of your financial goals is crucial.
Guaranteed Interest Periods
The product offers flexibility in terms of the interest period. You can choose an initial period of three to six years. Once this period ends, you have the option to renew the contract for additional periods of one to ten years. This flexibility allows you to tailor the investment to your financial timeline.
Surrender Charges And Withdrawal Provisions
One key feature of this annuity is the surrender charge schedule, which applies to withdrawals beyond the allowed free amount. This charge decreases over time and varies between the initial and renewal periods. However, policyholders can withdraw up to 10% of the contract value annually without incurring a surrender charge. Waivers for nursing home confinement and terminal illness are included, providing financial relief without penalties in specific situations.
Death Benefit
In the event of your passing, the death benefit ensures that your beneficiaries receive the full value of the annuity as of the date of your death. This feature provides peace of mind that your investment will be passed on without loss.
Key Features Explained
Interest Rate Guarantees
- Guaranteed fixed interest during the initial term.
- Daily compounding.
- Higher interest rates may apply for contracts ≥$100,000.
Free Withdrawals
- 10% of your contract value per year.
- RMDs that exceed the free amount are also exempt from surrender charges.
- No carryover of unused free withdrawals.
Renewal Options
- Upon maturity, you can:
- Renew into a term (1–10 years, subject to availability),
- Surrender,
- Take a partial withdrawal and renew the balance,
- Annuitize for lifetime income.
- Automatic renewal into a 1-year term occurs if no action is taken.
Surrender Charge Schedules (Initial Periods)
- 3-Year: 7%, 7%, 7%
- 4-Year: 7%, 7%, 7%, 6%
- 5-Year: 7%, 7%, 7%, 6%, 5%
- 6-Year: 7%, 7%, 7%, 6%, 5%, 4%
Waivers
- Nursing Home Waiver: After 90 days of confinement (not available in year 1).
- Terminal Illness Waiver: Withdrawals penalty-free if diagnosed terminally ill during accumulation phase.
Death Benefit
- Full contract value paid as a lump sum.
Pros and Cons
Pros
- Guaranteed fixed interest with daily compounding.
- Optional renewal terms up to 10 years.
- Nursing home and terminal illness waivers.
- Flexible income options upon annuitization.
- High-quality insurance backing from Guardian (A++ AM Best via Guardian Life).
Cons
- No market-based or index-linked growth potential.
- Surrender charges are high (7% in early years).
- Only a single premium is allowed—no future contributions.
- No GLWB rider for guaranteed lifetime income without annuitization.
- Annuitization not allowed in the first year.
- Renewal interest rates are not locked in and may be lower.
What Happens After the Surrender Period?
Once the guaranteed period ends:
- You may withdraw funds penalty-free during a 31-day window.
- You can renew into a new term (new surrender charges apply unless it’s a 1-year renewal).
- If no action is taken, your funds default into a 1-year term with no surrender penalty.
- You may also annuitize or do a 1035 exchange into another annuity.
The Importance of Comparing Annuities
You should never buy a MYGA or fixed annuity without comparing:
- Surrender schedules.
- Liquidity features.
- Available waivers.
- Renewal rate policies.
- Income options (especially GLWBs).
Small differences in features can mean thousands of dollars in missed income or penalties.
Who Should Consider This Annuity?
You need it if:
- You want predictable, fixed interest over a specific time frame.
- You’re using non-qualified or qualified retirement funds and don’t need liquidity beyond 10%.
- You need a conservative solution outside the stock market, such as for RMD planning.
- You’re in or nearing retirement and want safety and interest certainty.
You don’t need it if:
- You want potential for higher growth through stock or index-based performance.
- You want a lifetime income without annuitization.
- You prefer products with flexible ongoing contributions.
- You’re under 59½ and may need to access funds early (IRS 10% penalty applies).
Alternatives To Consider
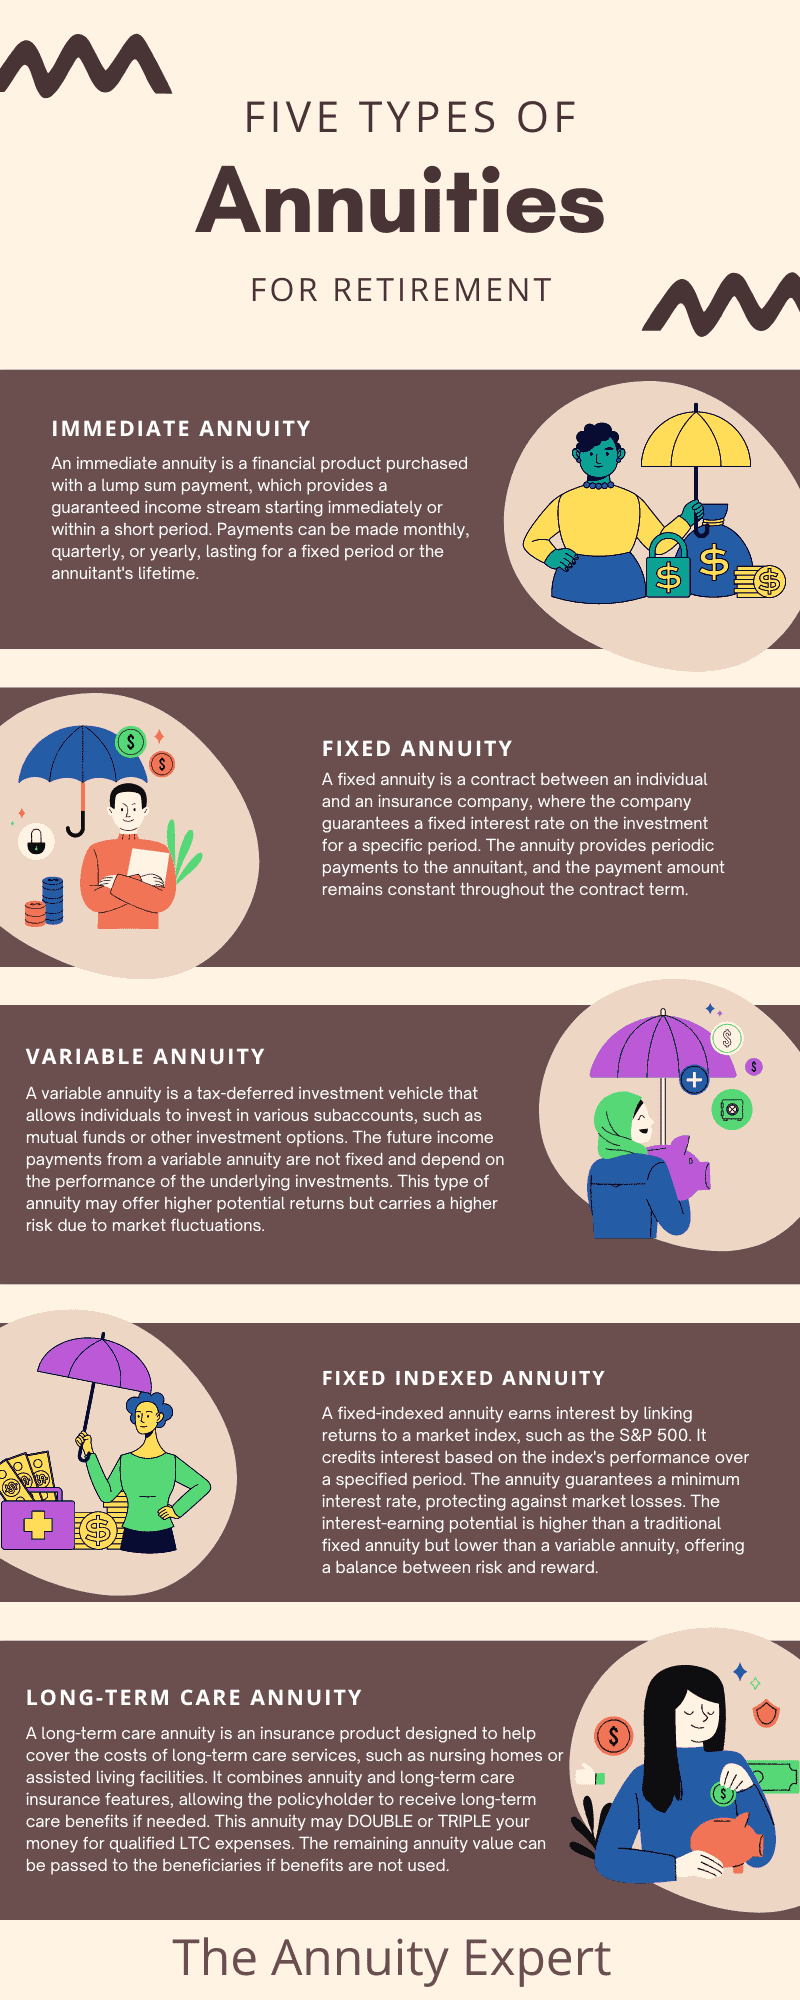
1. Multi-Year Guaranteed Annuities (MYGAs) from other carriers
Compare rates across carriers. Some offer higher interest, lower surrender charges, or flexible contribution options.
2. Fixed Indexed Annuities (FIAs)
These provide a declared fixed interest rate or index-linked returns with no market losses. Many offer GLWB riders, which provide guaranteed income for life without the need to annuitize.
3. Annuities With Income Riders (GLWB)
If your goal is income, a deferred annuity with a Guaranteed Lifetime Withdrawal Benefit rider provides lifetime income with flexibility and beneficiary protections.
4. Life-Only SPIA + Life Insurance
For early retirees under age 59½ who want income without IRS penalties, pair a non-qualified life-only SPIA with a life insurance policy to protect beneficiaries.
What We Recommend
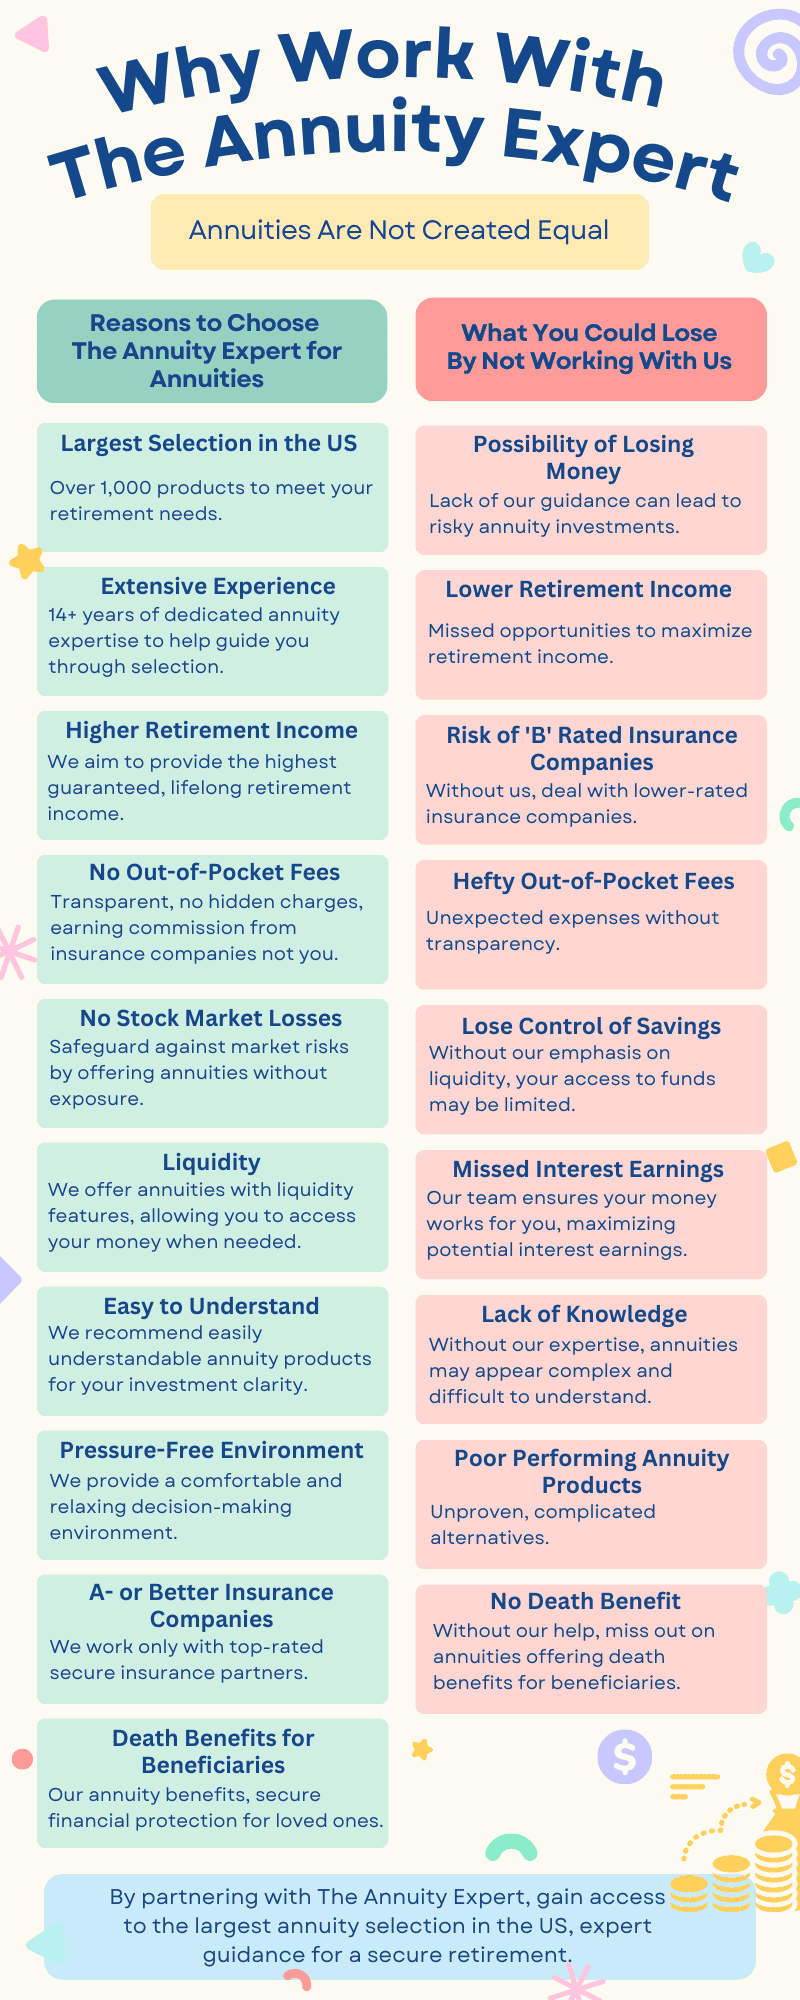
We recommend Guardian Fixed Target when its rate is competitive, especially for buyers who value company strength, first-year liquidity, and a clean maturity process. Contact The Annuity Expert for free quotes and a no-obligation comparison with current A- or better-rated MYGAs.
Book A Free Consultation
Get help from a licensed financial professional. This service is free of charge.
Let Us Answer Your Questions
Not quite ready for a meeting, but you have a question that needs answering? We’re happy to help. Leave an inquiry below, and one of our staff will respond via email.
Related Reviews
- Is Athene Ascent Pro 10 Any Good?
- American Equity Annuity Reviews
- Are Fidelity Annuities Any Good?
- Is The IncomeShield 10 Fixed Index Annuity Any Good?
- Is the Allianz 222® Annuity Any Good?
- Is Allianz Core Income 7® Annuity with Core Income Benefit Rider Any Good?
- Are North American Life Insurance And Midland National Reliable Annuity Companies?
- Is The USAA Protected Retirement Income Annuity Any Good?
- Is Nex Multi-Year Guaranteed Annuity (MYGA) by The Ohio State Life Insurance Company Any Good?
- Is NAC VersaChoice 10 Fixed Index Annuity Any Good?